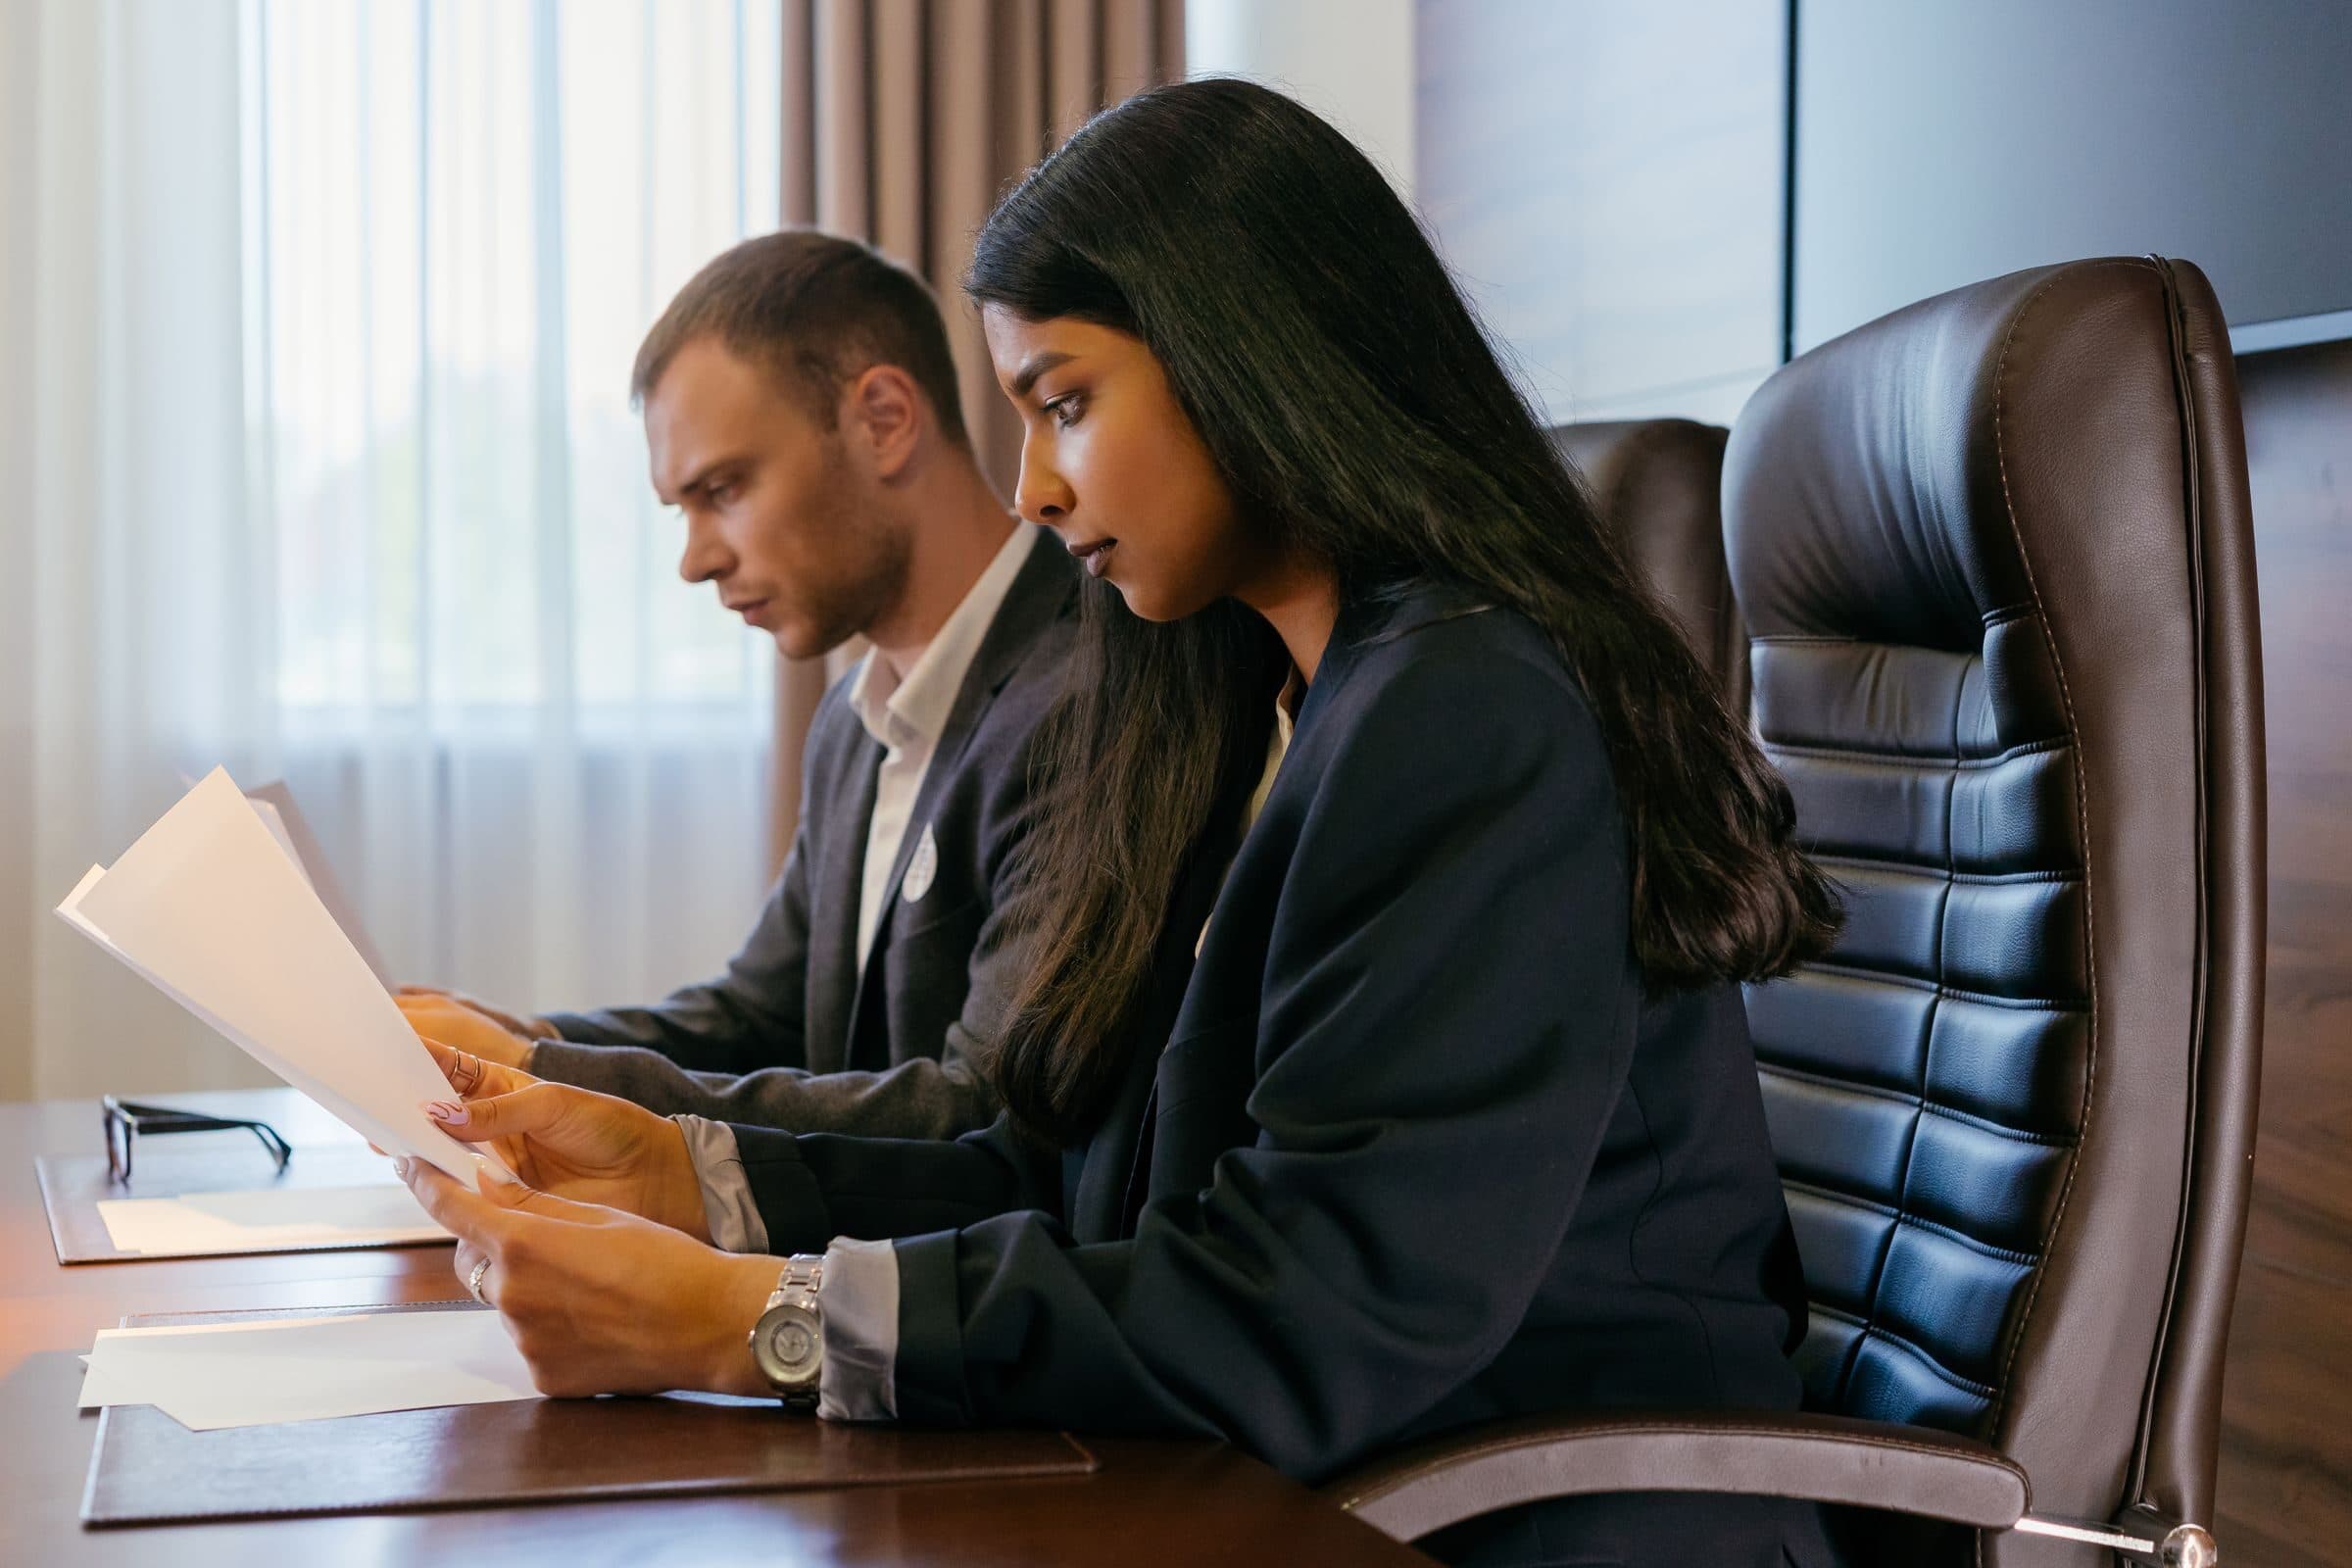
Errors and omissions
A client claims your advice or your work cost them money.
Firms that sell advice carry a different kind of risk. We size errors and omissions and cyber cover to your engagements.
Eight relevant markets are shown for comparison. Availability depends on the risk and location, and a logo does not imply a direct appointment.

Professional services
Professional liability

Management and professional liability

Small professional firms

Specialty professional liability

Professional liability
Professional services

Independent professionals
A few questions about your business or home.
We compare carriers and read the forms line by line.
We pick the best policy and get you covered.
There is no flat rate for this coverage. These are the inputs a carrier prices against, and they are the same things the quote form asks you for.
A client claims your advice or your work cost them money.
A breach exposes client data, triggering notification costs, liability, and downtime.
Clients require E&O limits before they sign, and you cannot start work without it.
Professional liability, also called errors and omissions, answers a claim that your advice or your work product cost the client money. It is written claims made, so the policy in force when the claim is reported responds, and only back to the retroactive date printed on the declarations. Changing carriers without carrying that date forward is how firms quietly lose years of prior acts.
The office itself still produces ordinary liability: a client injured in reception, damage you cause while working at a client's site, a delivery that goes wrong. General liability handles bodily injury and property damage and deliberately excludes the professional work. That exclusion is the reason both policies exist rather than one.
Property and general liability packaged for a professional office: tenant improvements, furniture, computers, the liability of the premises, and normally business income. Consulting, accounting, and advisory offices are a clean class for most carriers. It does not include errors and omissions or cyber, which stay on their own policies no matter how the package is built.
An umbrella adds limit above general liability and commercial auto and pays after those are exhausted. Whether it also sits over professional liability depends entirely on the schedule of underlying insurance, and on most forms it does not. Client contracts that name a total figure rather than a primary one are the usual reason a firm needs the layer at all.
July 10, 2026
What professional liability insurance covers, how E&O and professional indemnity insurance differ from general liability, who needs it, and what it costs.
Read guideThe right program depends on the operation, but the lines we most often evaluate are Professional Liability, General Liability, Business Owners Policy, and Commercial Umbrella. We confirm which exposures are present before recommending a policy, so you do not pay for a line simply because it appears on a standard checklist.
Have the services you provide, revenue, contracts, client types, requested limits, prior acts date, and loss runs ready. A complete submission lets carriers evaluate the account on the actual operation and reduces follow-up questions before they can quote.
Often, yes. A decline does not guarantee another carrier will quote, but it tells us where the standard market stopped. We review the reason, improve the submission where the facts support it, and approach specialty markets when they are appropriate.
We compare the coverage form, limits, deductibles, exclusions, carrier financial strength, binding requirements, and total cost. The lowest premium is not the best option when the form removes the protection the business needs.
Start a quote and a licensed broker takes it from there, or talk to one now.

