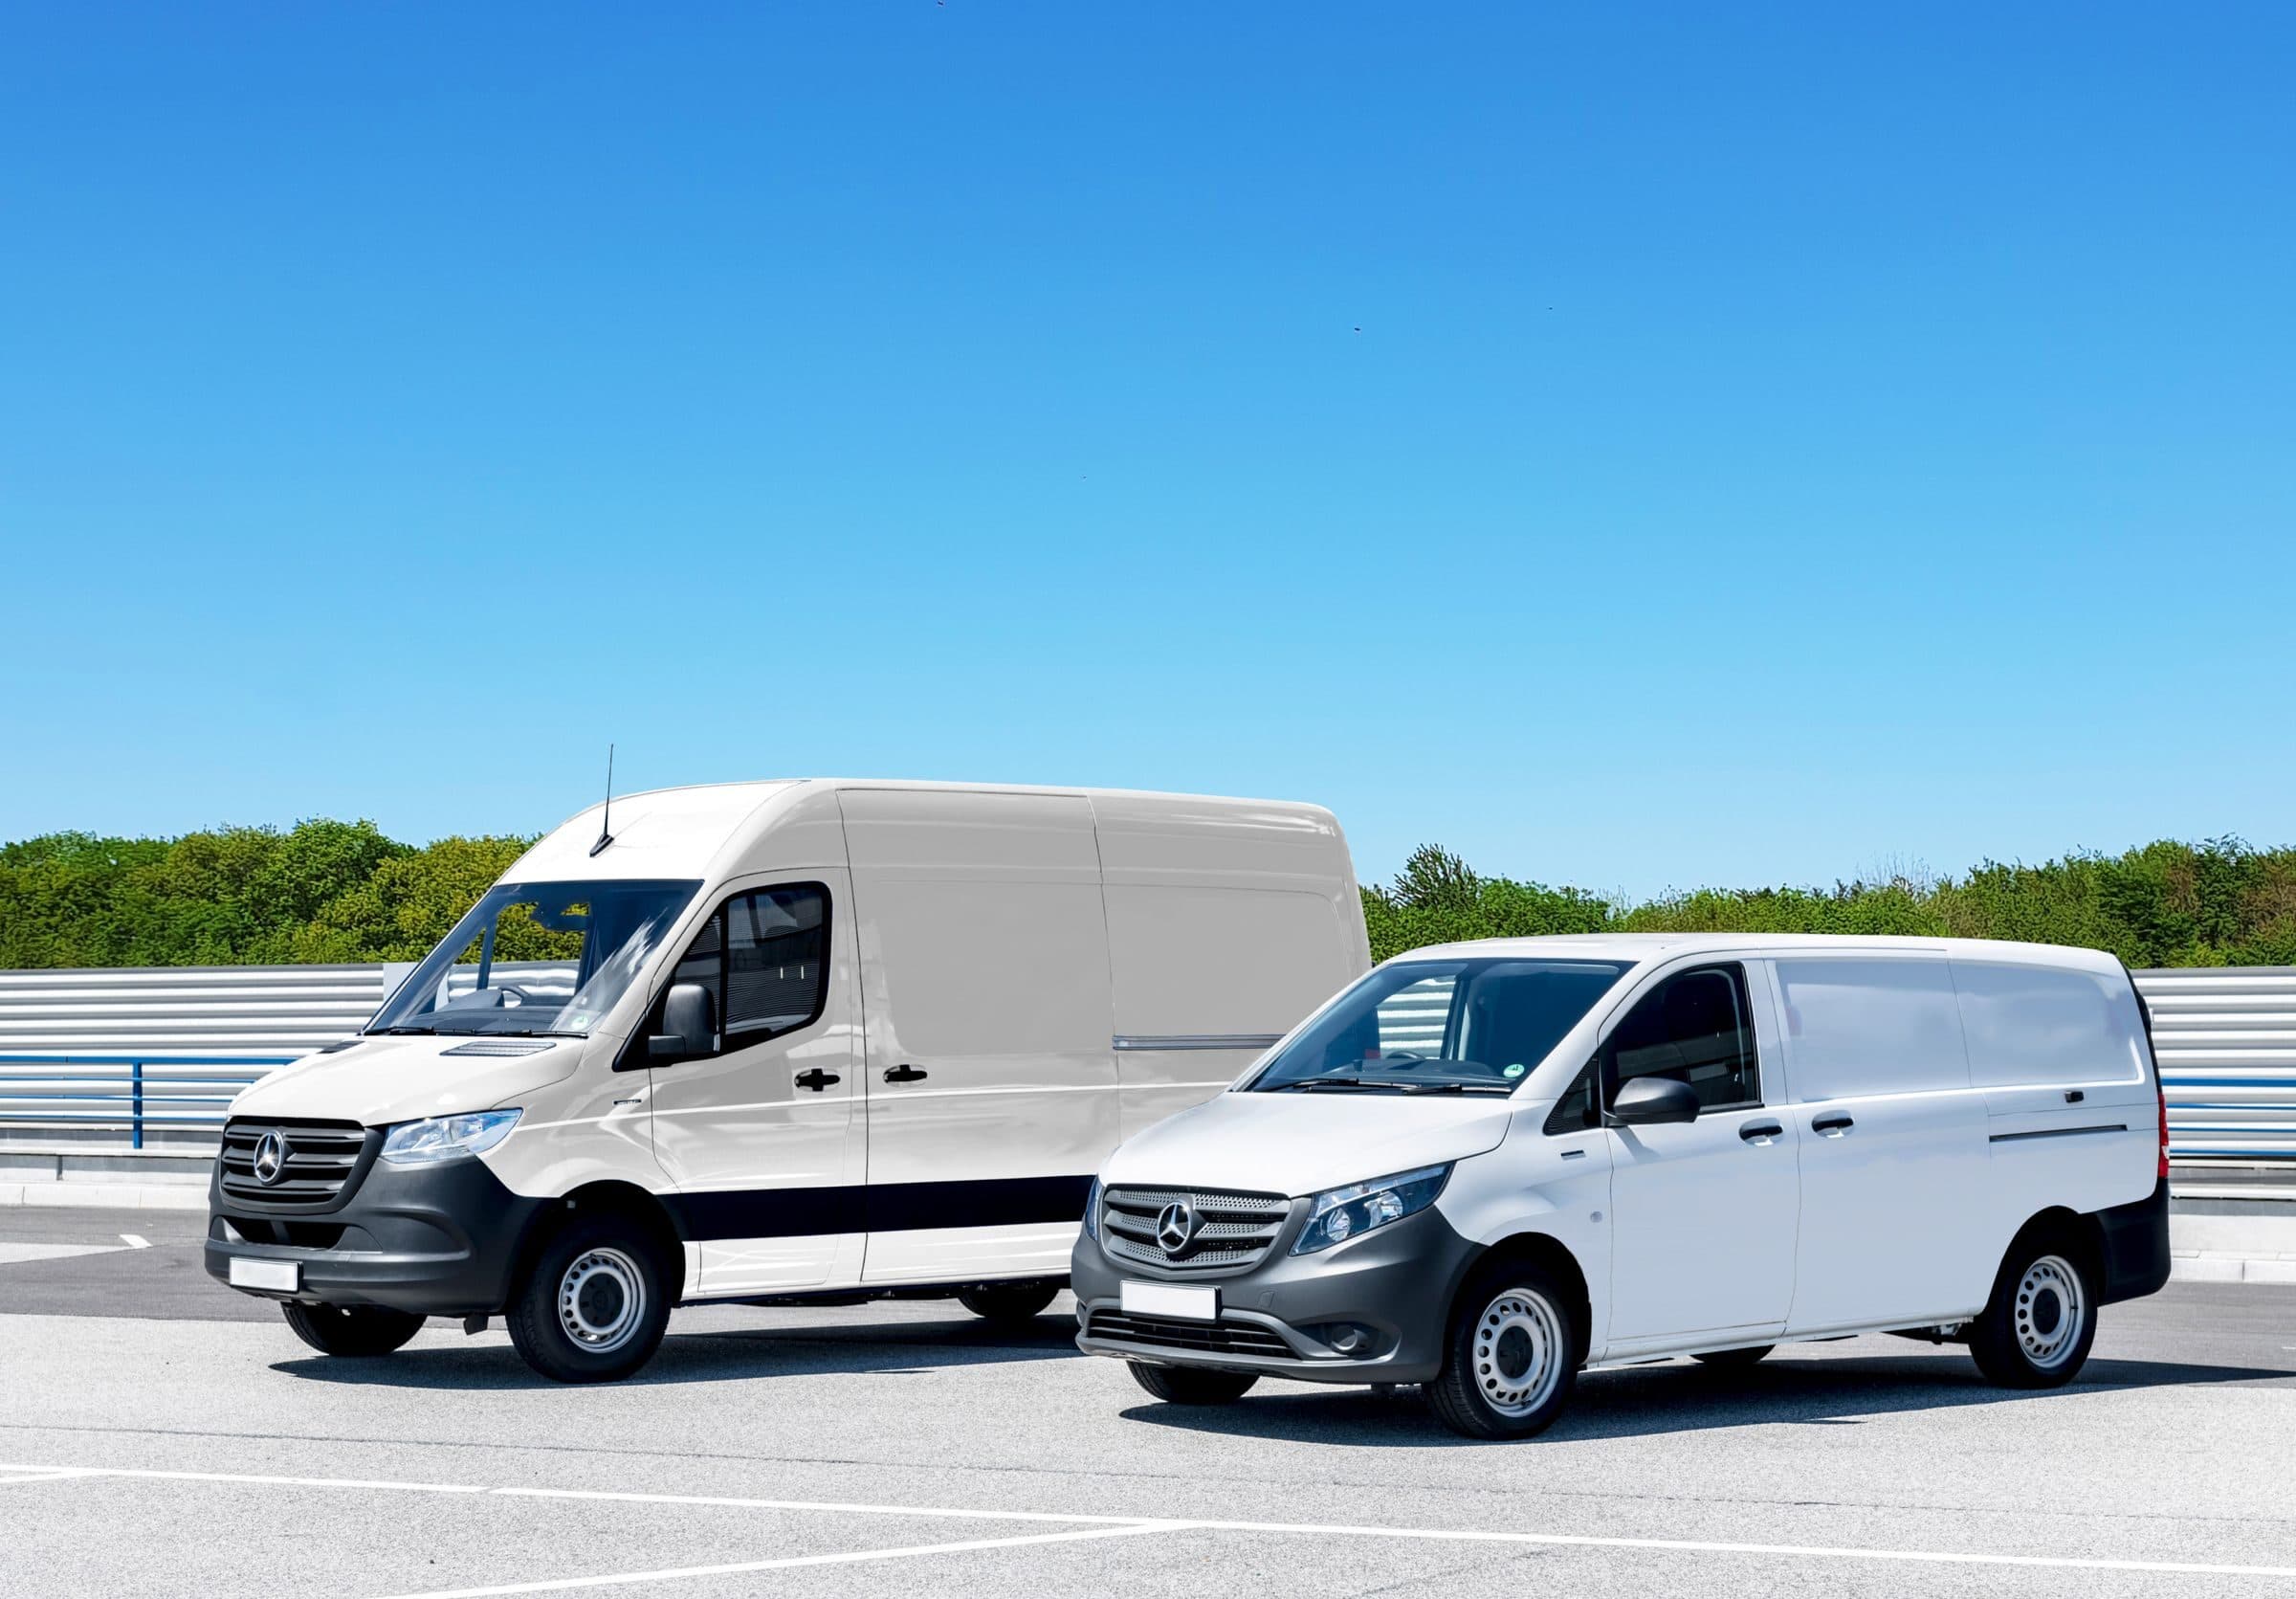
Commercial Auto Insurance
Insure the vehicles and drivers your business depends on. We shop carriers for coverage that fits how you use them.
We shop the market for you, no broker fees
For any operation that relies on vehicles
- Contractors and service fleets
- Delivery businesses
- Retailers with company vehicles
- Wholesalers and distributors
What changes your premium
These details help insurers assess your business and price the coverage. Terms and available options vary by insurer.
- The number, type and value of the vehicles
- What the vehicles are used for, and the radius they run
- Driver records for everyone who gets behind the wheel
- Whether you haul goods, and what the goods are
- Garaging location for each unit
- The liability limit and the physical damage deductibles
- Hired and non-owned exposure from employee vehicles
- Your loss history, including at-fault frequency
How it works
One short form
A few questions about your business or home.
We shop the market
We compare carriers and read the forms line by line.
Quote and bind
We pick the best policy and get you covered.
What this policy can cover
Liability
Injury and property damage you cause with a business vehicle.
A delivery van runs a light and injures two people. Medical bills, lost wages and a defense can pass what a small business is worth, and this is the coverage standing between that and the balance sheet.
Physical damage
Collision and comprehensive coverage for your own vehicles.
Hired and non-owned auto
Vehicles you rent or that employees drive for work but you do not own.
Medical and uninsured motorist
Optional coverage for medical costs and injuries from an uninsured driver. Uninsured motorist can be added, or rejected in writing where state rules allow.
How your limits and deductibles get set
Start with your contract requirements and potential losses. Then compare the cost of higher limits with what you could afford to pay yourself.
- 01
Start with the contract
Check the insurance limits and endorsements required by your lease, client agreements or project contract.
- 02
Then size the exposure
Consider property values, the work you do, possible injury claims and legal defense costs.
- 03
Then price the step up
Where available, compare more than one limit and deductible. A lower premium may leave you paying more after a loss.
- 04
Then review it at renewal
Review changes in revenue, payroll, property values and operations before renewing your coverage.
Questions we get asked
Do I need commercial auto insurance?
If you or your employees drive owned, rented, or personal vehicles for business, personal auto policies usually exclude that use and a commercial auto policy is needed.
What does commercial auto insurance cover?
It covers liability, physical damage, and often hired and non-owned auto, medical payments, and uninsured motorist coverage.
What is hired and non-owned auto coverage?
It covers liability from rented vehicles and from employees using their own cars for work, a gap many small businesses miss.
How much does commercial auto insurance cost?
Rating reflects vehicle type and use, driving records, radius, limits, and whether you run a single vehicle or a fleet.
Are there state filing requirements?
Certain operations, like for-hire carriers, need state or federal filings. We handle the filing that matches your authority.
Will my personal auto policy cover me if I use the car for work?
Often it will not. Personal policies commonly exclude business use, and delivery or rideshare use almost always. If the vehicle is central to how you make money, it belongs on a commercial policy.
Does it cover employees driving their own cars for work?
Only if hired and non-owned coverage is on the policy. The employee's personal insurance is primary, but your business is routinely named in the suit anyway, and this is the endorsement that answers.
Does it cover the cargo I am hauling?
No. Damage to the goods you carry is motor truck cargo coverage, which is written separately.
Does it cover an employee's injuries in a work crash?
Their medical care and lost wages come from workers' compensation. The auto policy handles the vehicle and what you owe the other party.
Start your quote online.
Fill in one short form or call us. No broker fees.