Jewelry and Engagement Ring Insurance
Insure an engagement ring, watch or heirloom at an agreed value against loss, theft and damage beyond typical homeowners or renters sublimits.
We shop the market for you, no broker fees
Eight relevant markets are shown for comparison. Availability depends on the risk and location, and a logo does not imply a direct appointment.


What this policy can cover
Your ring and fine jewelry
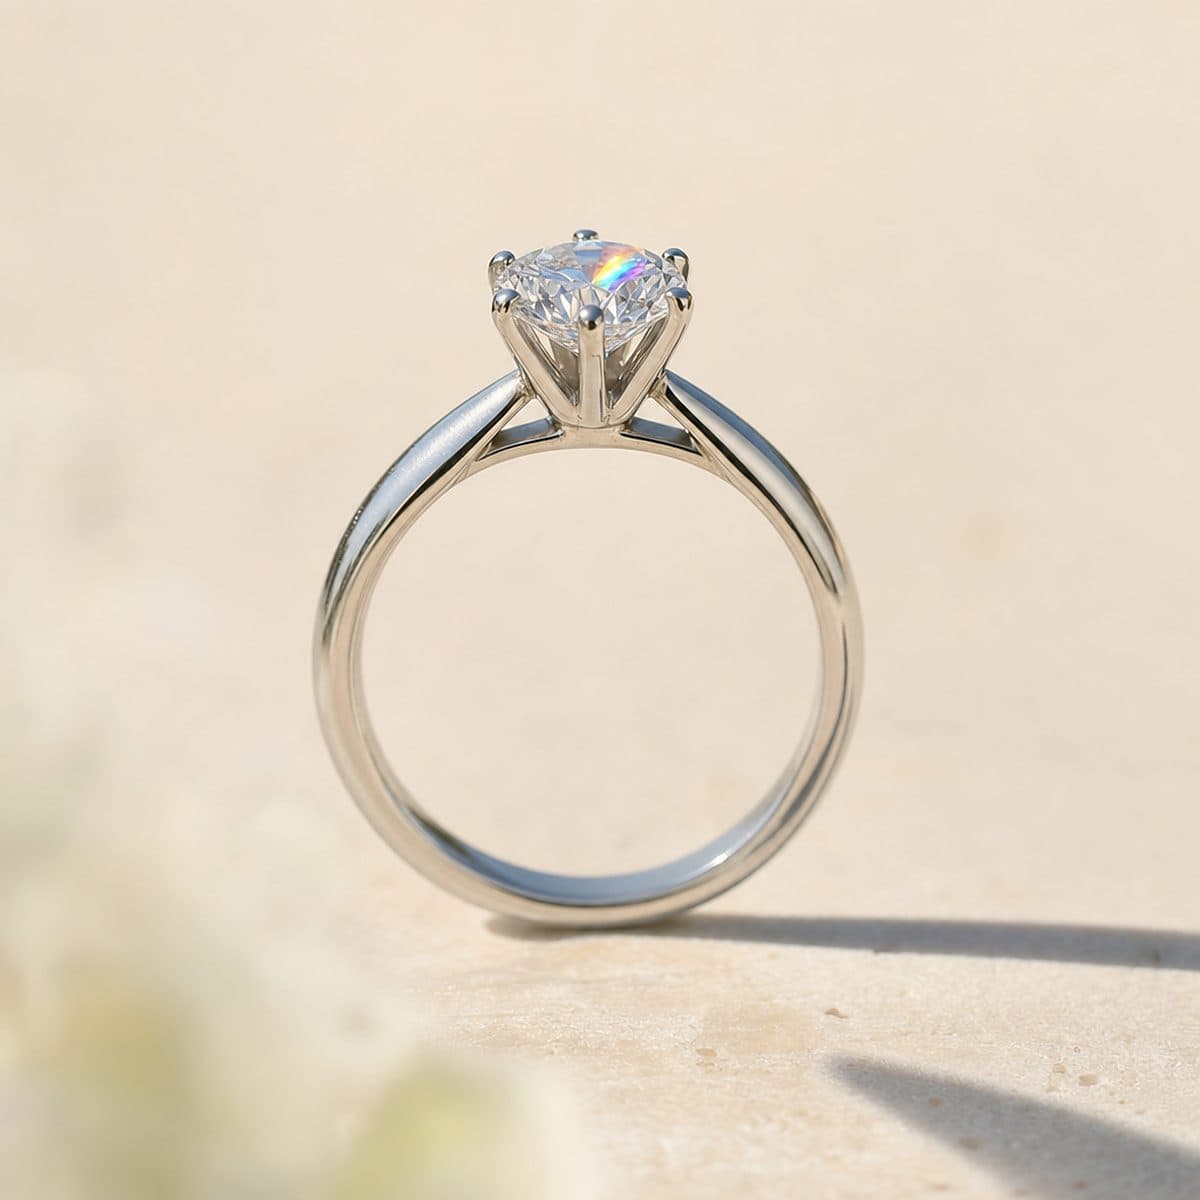
Engagement rings, watches, and heirloom pieces, insured for an agreed or appraised value.
Loss and mysterious disappearance
Coverage that includes simply losing a piece, which a homeowners policy typically does not.
Damage and theft
A cracked setting, a lost stone, or a stolen piece, usually with no deductible on a scheduled policy.
Worldwide protection
Coverage travels with you, at home or abroad, subject to the policy terms.
Built for meaningful pieces
- A newly purchased engagement or wedding ring
- Inherited or heirloom jewelry
- Fine watches and designer pieces
- Anyone whose ring exceeds their policy sublimit
Coverages that pair with this
Homeowners Insurance
The structure, everything inside it, and your liability as the owner of the place it happened.
Renters Insurance
Your belongings and your liability in a building whose policy covers the landlord rather than you.
Umbrella Insurance
Extra liability limit sitting above the home and auto policies you already carry, for a fraction of what raising each one costs.
Frequently asked questions
How do I insure an engagement ring?
The most reliable way is a scheduled personal property policy, sometimes called a jewelry floater, that lists the ring at an agreed or appraised value. You provide a recent appraisal or the receipt, and the piece is covered for loss, theft, and damage, usually with no deductible. We can set it up as a standalone policy or an endorsement.
Isn't my ring already covered by homeowners or renters insurance?
Partly, and usually not enough. Homeowners and renters policies cap jewelry theft at a low sublimit, often around 1,500 dollars, and they generally do not cover simply losing a ring. Scheduling the piece raises the limit to its full value and adds the perils the base policy leaves out.
Do I need an appraisal to insure jewelry?
For higher-value pieces, usually yes. Carriers want a recent appraisal or a detailed sales receipt to set the insured value. For newer purchases the store receipt is often enough. We tell you what a given carrier needs before you buy.
What is scheduled personal property?
It is coverage that lists a specific valuable item at an agreed amount, above the standard sublimits of a homeowners or renters policy. Jewelry, watches, art, and instruments are common examples. Scheduling adds broader perils, like mysterious disappearance, and typically removes the deductible for that item.
How much does jewelry insurance cost?
A common range is roughly 1 to 2 percent of the item's value per year, though it depends on the piece, where you live, and the carrier. A ring appraised at several thousand dollars often costs a modest amount annually. We quote it against the actual appraisal.
Does jewelry insurance cover a lost stone?
A scheduled jewelry policy usually covers a lost or damaged stone, including a diamond that falls out of its setting, which a homeowners policy typically will not. Gradual wear that loosened the setting over time can be a gray area, so the cause matters. We walk through the terms before you rely on them.
Does this policy cover gradual wear?
Everyday deterioration, loose prongs over time, and general aging are maintenance, not a covered loss.
Does this policy cover undisclosed or unappraised value?
A piece worth more than you scheduled is only covered up to the amount on the policy.
Does this policy cover intentional damage?
Damage you cause on purpose is never covered.
Does this policy cover pieces excluded at underwriting?
Items a carrier declines to schedule, or that fall outside the agreed inventory, are not covered.
Can you write this where I live?
We are currently licensed in California only. Start a quote if the business or risk is in California, and we will confirm eligibility before you spend time on it.
What happens after I start a quote?
Tell us about the coverage you need and complete the application. We use those details to approach suitable markets and may ask follow-up questions. Requesting a quote does not put coverage in force.
Get a jewelry insurance quote
Tell us about the piece and share a recent appraisal or receipt. We compare carriers and confirm the agreed value and perils fit.