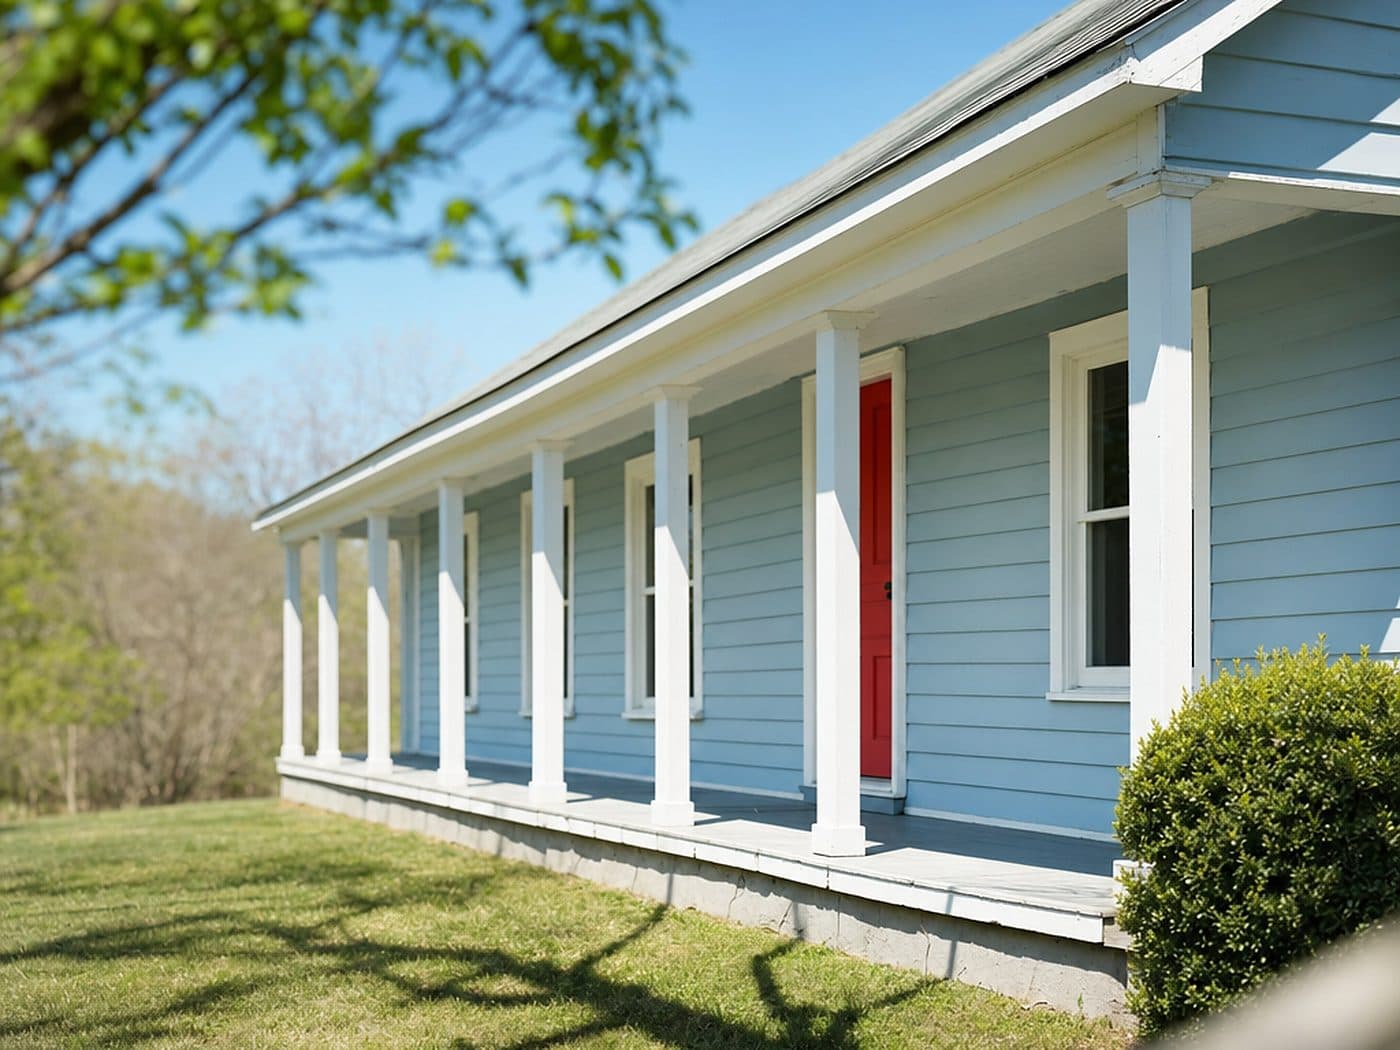
Homeowners Insurance
Protect your house, belongings and liability, insured for what it costs to rebuild. We shop top carriers for the right coverage.
We shop the market for you, no broker fees

What this policy can cover
Your house
Rebuilding or repairing the structure after a covered loss like fire or wind.
Your belongings
Furniture, clothes, and electronics, at home or with you when you travel.
Personal liability
If a guest is hurt on your property or you accidentally damage someone else's.
Somewhere to stay
Additional living expenses if a covered loss makes the house unlivable while it is repaired.
Why does the rebuild figure matter more than what I paid?
Because a policy pays to rebuild, not to re-buy. What a house sells for includes the land, the street and a market. What it costs to put back after a fire is labour, materials and code compliance on the day of the loss, and in many places the second number has been moving faster than the first.
What does a home policy leave out?
Flood and earthquake, on every standard form, in every state. Both are bought separately or added back by endorsement, and in a quake state the deductible is a percentage of the insured value rather than a flat figure. Anyone who tells you the home policy has those covered has not read it.
Built for homeowners
- First-time buyers closing on a loan
- Families upgrading coverage after a remodel
- Owners in wildfire-affected areas weighing options
- Anyone whose renewal jumped without explanation
What changes your premium
These details help insurers assess your business and price the coverage. Terms and available options vary by insurer.
- The cost to rebuild the house today, which is not its market price
- Age, construction, roof age and any recent updates
- Wildfire, flood and quake exposure at the address
- Distance to a fire station and to a hydrant
- The deductible you pick, including any percentage deductible
- Claim history at the property and on your own record
Coverages that pair with this
Auto Insurance
Liability, damage to the car, and the other driver who turns out to have no insurance at all.
Umbrella Insurance
Extra liability limit sitting above the home and auto policies you already carry, for a fraction of what raising each one costs.
Life Insurance
What the household lives on if your income stops.
Questions we get asked
How much dwelling coverage do I need?
Enough to rebuild the house at today's construction costs, which is not the same as its market price or your loan balance. We estimate rebuild cost from the home's size, age, and features, and we review it at renewal because construction costs move.
Is wildfire covered?
Fire, including wildfire, is a core covered peril on standard homeowners policies. The real issue is availability: in higher risk areas some carriers decline to write, and the FAIR Plan plus a wrap policy can be the fallback. We walk you through the realistic options for your address.
What is the difference between replacement cost and actual cash value?
Replacement cost pays to repair or replace with new materials of similar kind and quality. Actual cash value subtracts depreciation, so older items and roofs pay out less. Where the choice exists, we quote both so you can see the tradeoff.
Will filing a claim raise my rate?
It can, and claim history follows you between carriers through shared databases. For borderline losses close to your deductible it is often worth talking it through before filing. We help clients think that through honestly.
Does my policy cover my home office?
A desk and a laptop are usually fine. Regular client visits, inventory, or business equipment beyond policy limits generally are not, and may need an endorsement or a small business policy. Tell us how you work and we will match the coverage to it.
Does this policy cover flood?
Flood damage needs a separate flood policy. Standard homeowners policies exclude it.
Does this policy cover earthquake?
This is a separate policy or endorsement, often through a state earthquake program.
Does this policy cover wear and maintenance?
A roof at the end of its life or a slow leak you knew about is upkeep, not a covered loss.
Does this policy cover business activity at home?
Regular business use of the home usually needs its own coverage.
Can you write this where I live?
We offer coverage in the states where we are licensed. Begin a quote with the address of your business or risk, and we'll let you know which markets can write that location before you spend much time on the questions.
What happens after I start a quote?
Tell us about the coverage you need and complete the application. We use those details to approach suitable markets and may ask follow-up questions. Requesting a quote does not put coverage in force.
Start your quote online.
Fill in one short form or call us. No broker fees.