Manufactured Home Insurance
Protect the manufactured home you live in, visit seasonally or rent out. Tell us how you use it and we request quotes.
A manufactured home can be insured whether you live in it, use it seasonally or rent it out. The dwelling program we use writes manufactured homes after an underwriting review. If no insurer will take the home, the California FAIR Plan writes manufactured homes permanently anchored to a foundation for fire and other named perils.
- Who qualifies
- Manufactured homes used as a primary home, a seasonal home or a rental, by underwriting review
- Programs we use
- A specialty dwelling program that writes manufactured homes, and the California FAIR Plan when no insurer will take the home
- FAIR Plan rule
- The home must be permanently anchored to a foundation, and the FAIR Plan pays fire and other named perils without replacement cost for mobile homes
Our commitment
Committed to doing insurance right, and doing it fast. Our vision: every property and project properly covered in minutes, with every rule followed.
Eight brokers, one team
Our eight brokers work together as one Menlo team, so you can reach a person who understands your account.
Independent brokerage
We hold appointments with multiple carriers, so the quote is shopped rather than served from one shelf.
Start with the home itself
A manufactured home can be insured as an owner, tenant, seasonal or vacation rental home. Start with owner, tenant, shared owner-and-tenant, seasonal or vacation-rental occupancy. The dwelling program documents manufactured homes; its underwriting review determines the available coverage for your home.
Home type
Have the year, manufacturer and home type available.
Use and location
Describe whether the home is a primary residence, seasonal home or rental, and where it is located.
Requested protection
Have the dwelling value, foundation details and prior insurance information ready.
A review, not a promise
Choosing a home type starts a review. Availability depends on the property, location and underwriting.
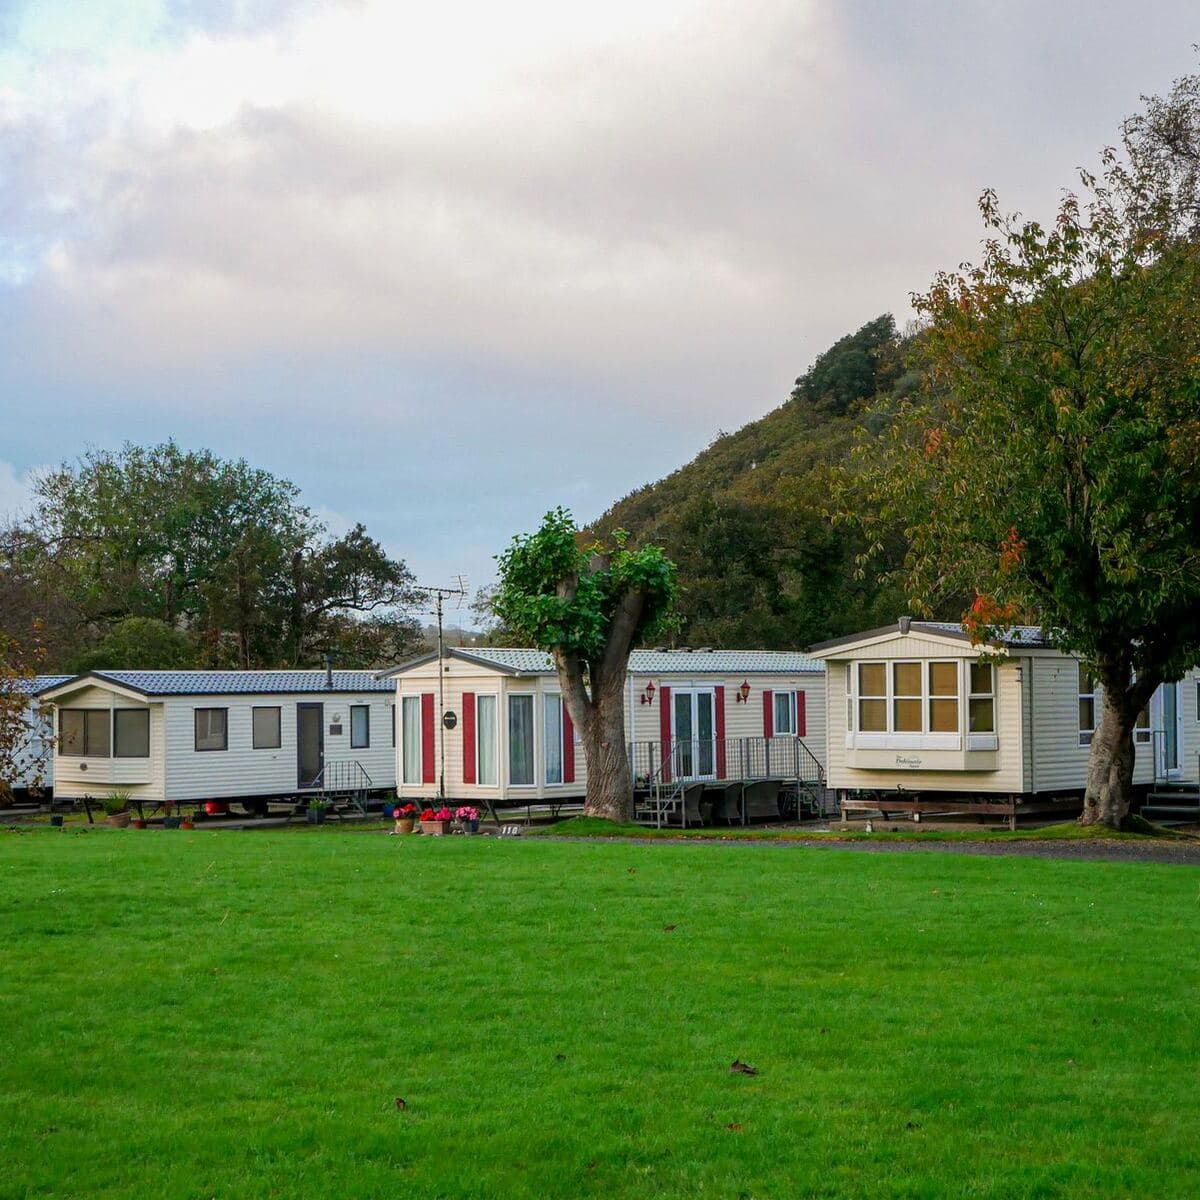
On the California FAIR Plan
If no insurer will take the home because of wildfire risk, the FAIR Plan dwelling policy is the fallback.
Anchored to a foundation
The FAIR Plan writes mobile and manufactured homes permanently anchored to a foundation. Homes that are not are not eligible.
Fire, with DIC beside it
It covers named perils such as fire and smoke, without replacement cost for mobile homes. A DIC policy can add theft, water damage and liability.
What to have ready
- Have the year, manufacturer and home type available.
- Describe whether the home is a primary residence, seasonal home or rental, and where it is located.
- Have the dwelling value, foundation details and prior insurance information ready.
What changes your premium
These details help insurers assess your business and price the coverage. Terms and available options vary by insurer.
- Home type, age and dimensions
- Location, occupancy and foundation
- Dwelling value and requested settlement basis
Questions we get asked
Are all types accepted?
Not every home is accepted, since availability depends on the property, location and underwriting. Selecting a type starts a review and does not confirm eligibility.
Review your coverage options.
A licensed broker can review eligibility and policy terms with you.