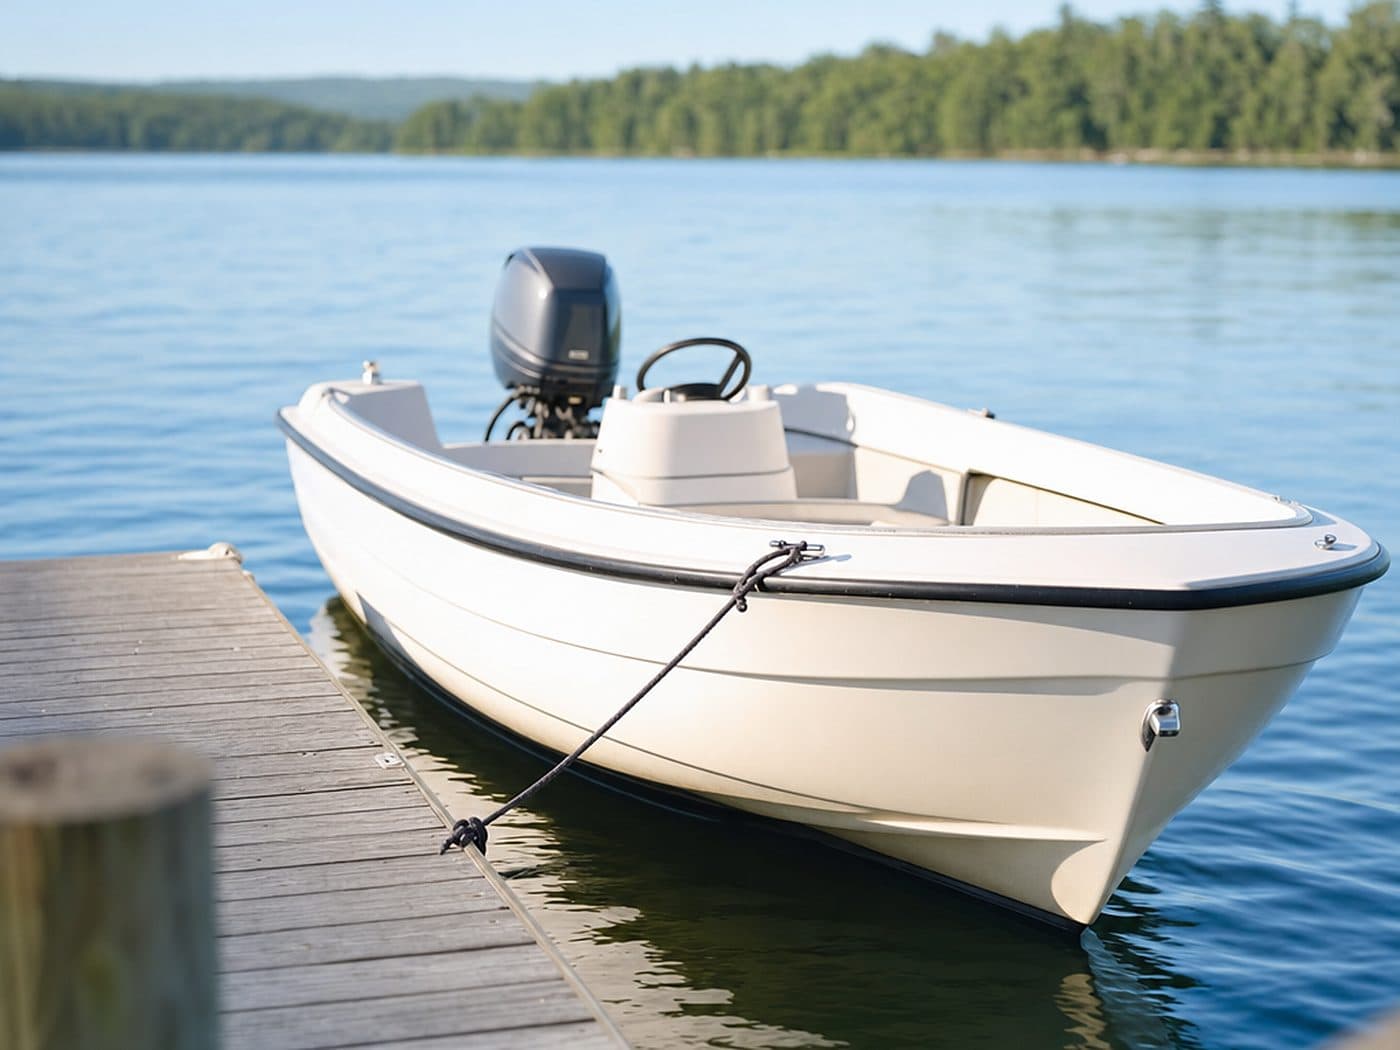
Boat and Watercraft Insurance
Insure your boat's hull and motor, your liability on the water and towing. We shop carriers for the right coverage.
Licensed in California
Menlo Insurance Services is the filed name of Opero Labs Inc. California license #6020106.
Eight brokers, one team
Our eight brokers work together as one Menlo team, so you can reach a person who understands your account.
Independent brokerage
We hold appointments with multiple carriers, so the quote is shopped rather than served from one shelf.
What this policy can cover
Physical damage to the boat
The hull, motor, and equipment after a covered loss like collision, storm, fire, or theft.
Liability to others
Injury or property damage you cause on the water, which a homeowners policy rarely covers for larger boats.
On-water towing and assistance
Towing to shore after a breakdown or grounding, when the coverage is included.
Uninsured boaters and medical payments
Optional coverage for injuries when another boater is at fault or uninsured.
Built for boat owners
- Owners of a powerboat, sailboat, or cruiser
- Anyone financing a boat a lender insures
- Boaters a marina requires liability from
- Owners who trailer and store in the off-season
Coverages that pair with this
Homeowners Insurance
The structure, everything inside it, and your liability as the owner of the place it happened.
Auto Insurance
Liability, damage to the car, and the other driver who turns out to have no insurance at all.
Umbrella Insurance
Extra liability limit sitting above the home and auto policies you already carry, for a fraction of what raising each one costs.
Questions we get asked
Which watercraft can I describe in this application?
The application includes motorboats, sailboats, houseboats, pontoons, small non-powered craft and personal watercraft. It collects boat and yacht details for review, not automatic acceptance. Very large yachts with a full-time paid captain may need a different application.
Does finishing the form produce an instant quote?
No. The form collects your vessel, operator, location and coverage information. A completed carrier application and supporting documents still need broker handling. An intake confirmation is not proof of a completed carrier upload, a quote or coverage in force.
Which supporting documents might be needed?
Depending on your answers, the application calls for an operator's Coast Guard license copy, a paid captain's résumé and license copy, or details of other commercial use. Your broker will identify the documents and any later signature requirements that apply.
Do I need boat insurance?
It is rarely required by state law, but a lender will require it on a financed boat, and many marinas require liability coverage to rent a slip. Beyond the requirements, a boat is a significant asset and on-water liability can be serious, so most owners carry it by choice.
Does my homeowners policy cover my boat?
Sometimes, for small, low-powered boats, and only to a limited extent. Larger boats, faster boats, and on-water liability are usually excluded or capped, and the coverage that does apply is narrow. A dedicated boat or watercraft policy is built for the exposure and closes those gaps.
What does boat insurance cover?
Typically physical damage to the hull, motor, and equipment, liability for injury or damage you cause, and often on-water towing, medical payments, and uninsured boater coverage. Personal effects and trailer coverage can usually be added. The exact form depends on the boat and how you use it.
How much does boat insurance cost?
Cost reflects the boat's value, type, and horsepower, where and how far you cruise, your boating experience and claims history, and whether it is laid up in the off-season. A small runabout costs far less than a large powerboat. We quote it against your actual boat and usage.
What is agreed value versus actual cash value for a boat?
Agreed value pays a set amount you and the carrier fix at the start, with no depreciation at claim time. Actual cash value subtracts depreciation and pays the boat's current market value, which costs less but pays less after a total loss. We show both where they are available.
Is my boat covered on the trailer and off-season?
Usually yes. Most policies cover the boat while trailering and during winter layup or storage, and trailer coverage can often be added for the trailer itself. Some policies reduce the premium during a defined lay-up period. We confirm the navigation and storage terms fit how you use the boat.
Does this policy cover wear, corrosion, and marine life?
Gradual deterioration, rot, and damage from marine organisms are maintenance, not a covered loss.
Does this policy cover manufacturing and design defects?
A defect in the boat itself is generally excluded, though resulting damage may be covered.
Does this policy cover unconfirmed racing or commercial use?
Do not assume these uses are covered. Racing, charter and other commercial activities require specific underwriting review.
Does this policy cover use outside the navigation limits?
Cruising beyond the geographic area on the policy can fall outside coverage.
Can you write this where I live?
We are currently licensed in California only. Start a quote if the business or risk is in California, and we will confirm eligibility before you spend time on it.
What happens after I start a quote?
Tell us about the coverage you need and complete the application. We use those details to approach suitable markets and may ask follow-up questions. Requesting a quote does not put coverage in force.
Start your quote online.
Fill in one short form or call us. No broker fees.