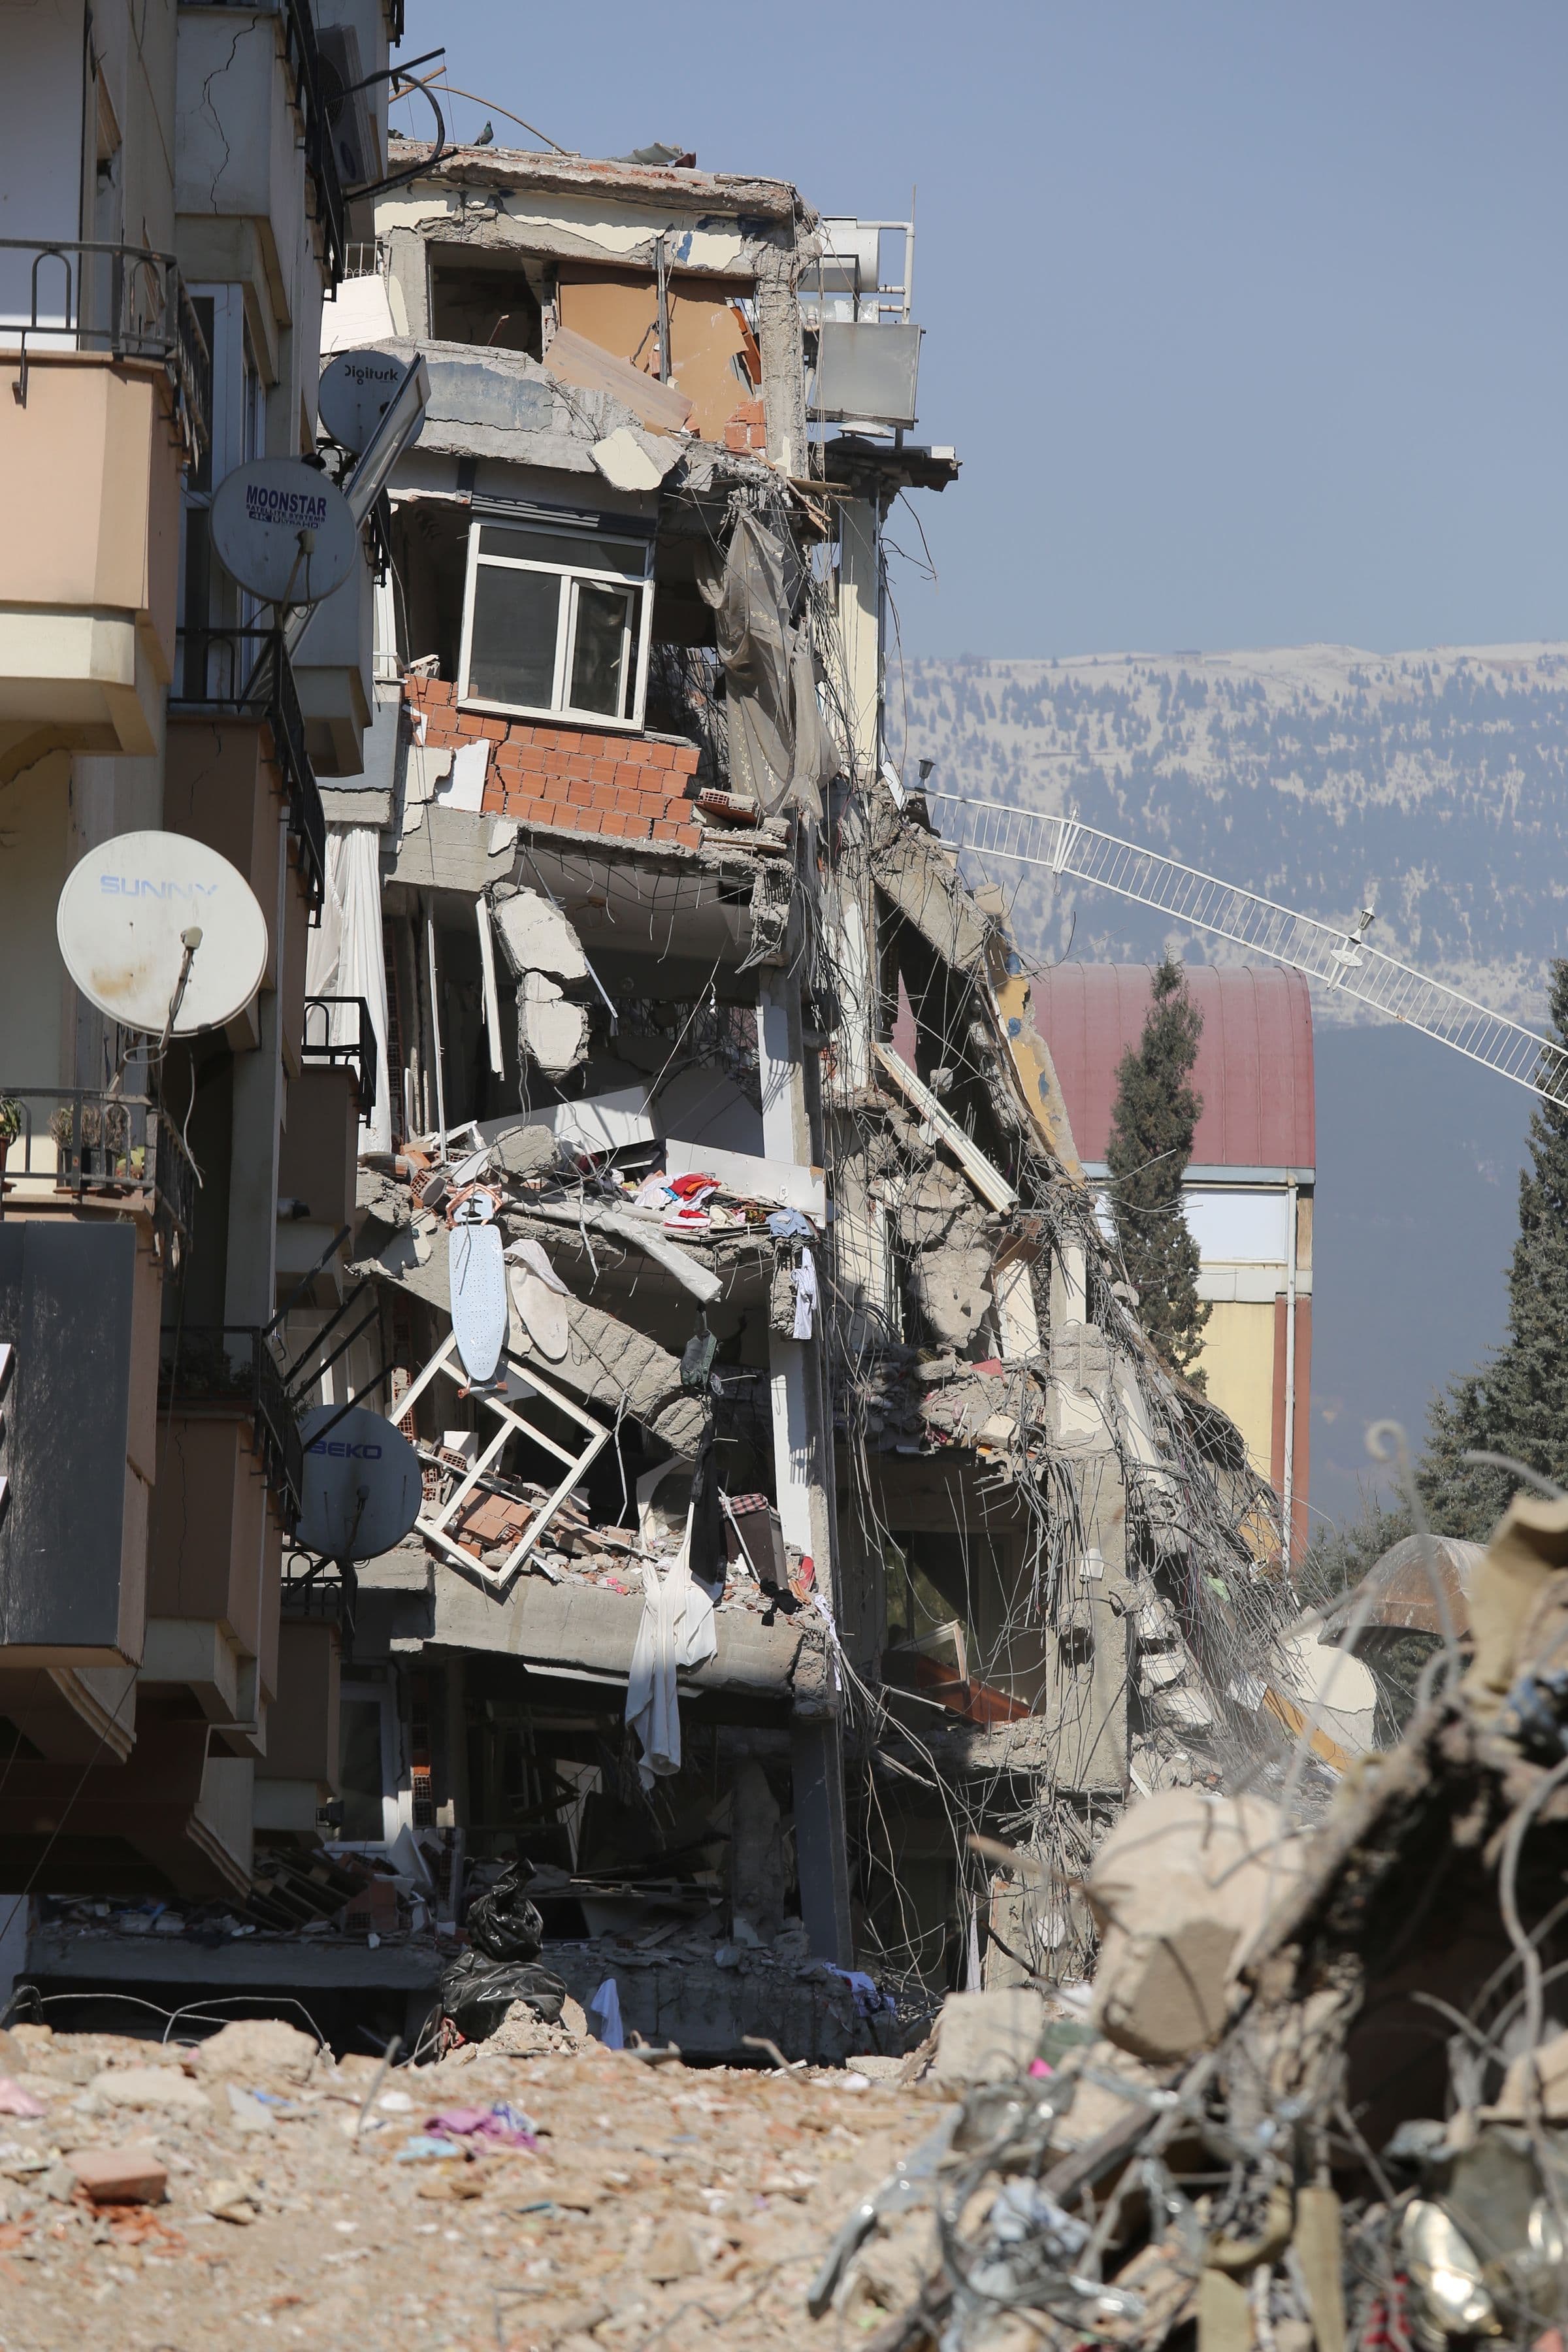
Commercial Earthquake Insurance
Add earthquake coverage for your commercial buildings. We review each building and request standalone quotes.
We shop the market for you, no broker fees
How it works
One short form
A few questions about your business or home.
We shop the market
We compare carriers and read the forms line by line.
Quote and bind
We pick the best policy and get you covered.
The building schedule is the earthquake submission
Construction, occupancy, year built and replacement value determine how the property responds to shaking. The intake keeps those facts attached to each location instead of flattening them into one estimate.
Construction is recorded precisely
Frame, masonry, concrete, steel and mixed construction do not behave the same way. The broker confirms the closest captured construction class for each building.
Values stay with each location
Building, contents and business income values are collected with the property they belong to so the schedule can be reviewed as a whole.
Deductible choices remain visible
The applicant can state a deductible preference while the licensed broker confirms which options are available for the final structure.
Written separately
Earthquake is often excluded or limited on the property policy. A separate placement lets you choose how to insure it.
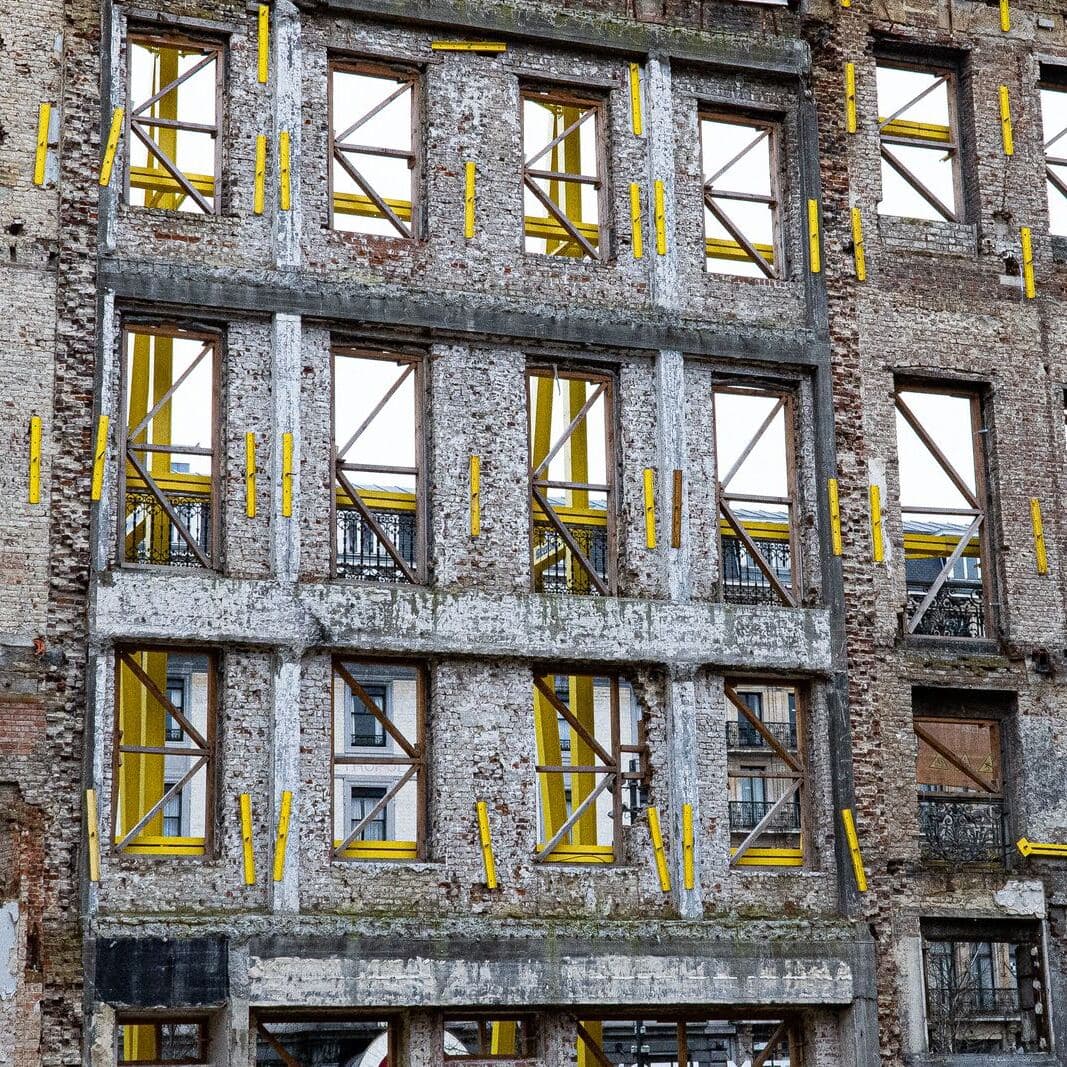
Commercial properties this intake can describe
- Retail and office buildings
- Habitational and mixed use schedules
- One building or a scheduled group of locations
- Owner occupied and tenant occupied commercial property
- Buildings requiring standalone earthquake review
What changes your premium
These details help insurers assess your business and price the coverage. Terms and available options vary by insurer.
- Property address and earthquake territory
- Occupancy and construction type
- Year built and number of stories
- Building, contents and business income values
- Requested deductible and optional coverages
Questions we get asked
Why is earthquake written separately from the property policy?
Earthquake is commonly excluded or limited under the permanent property program. A separate placement lets the applicant choose whether and how to insure that catastrophe exposure.
What values should I have ready?
Have the replacement value for each building, contents values and the business income amount that would be at risk after a covered loss.
Can you write this where my business is?
We offer coverage in the states where we are licensed. Begin a quote with the address of your business or risk, and we'll let you know which markets can write that location before you spend much time on the questions.
What happens after I start a quote?
Tell us about the coverage you need and complete the application. We use those details to approach suitable markets and may ask follow-up questions. Requesting a quote does not put coverage in force.
Start your quote online.
Fill in one short form or call us. No broker fees.