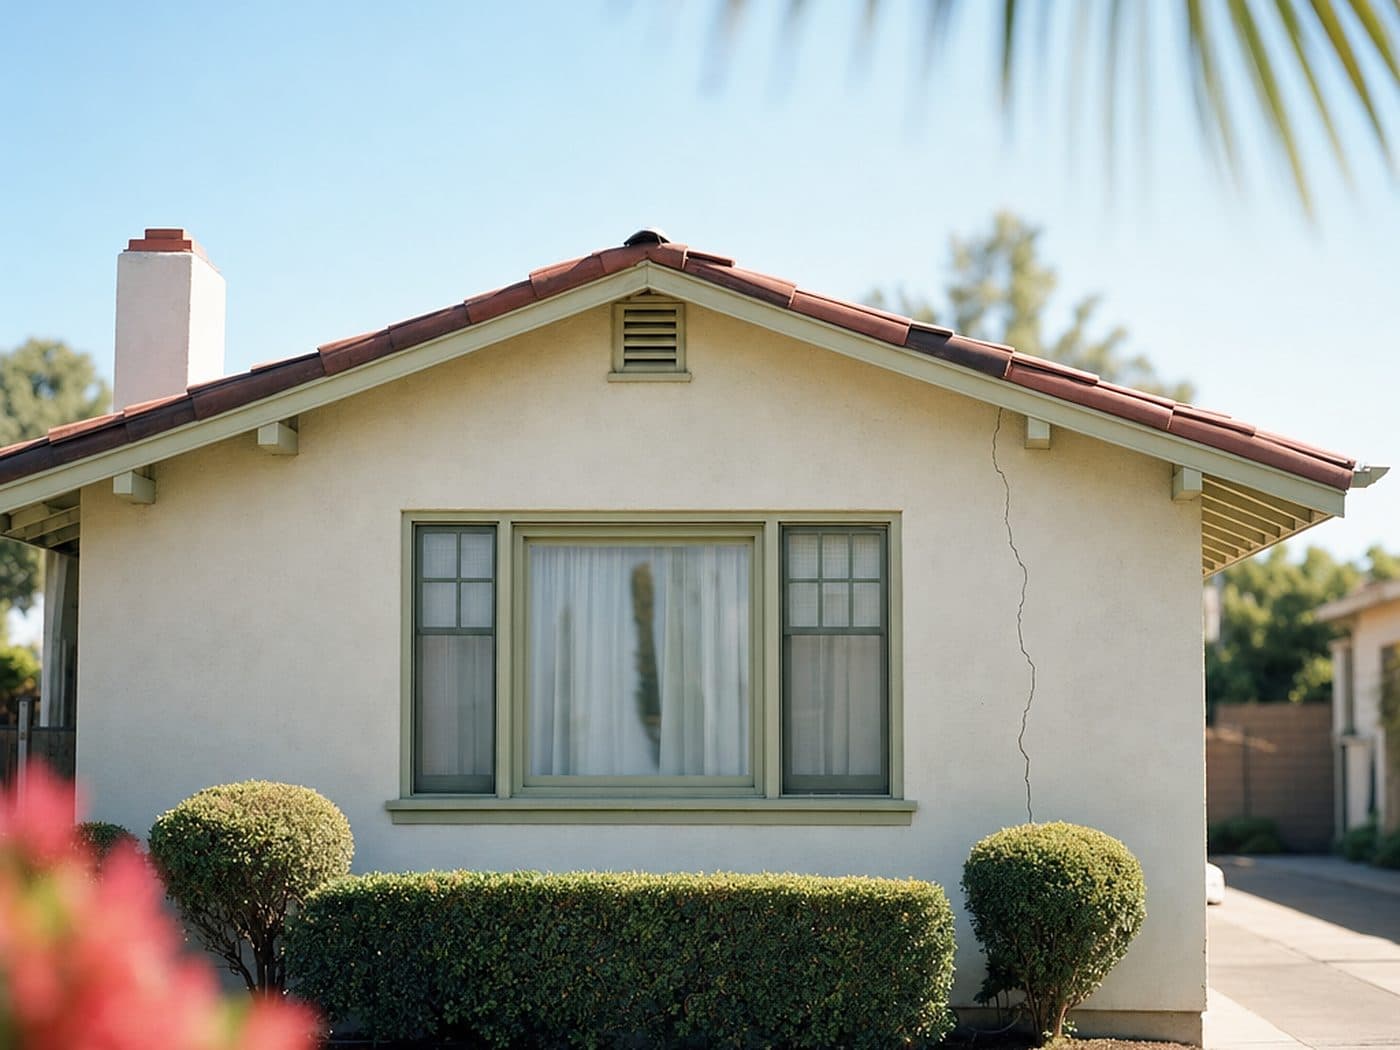
California Earthquake Insurance
Protect your California home from earthquake damage. We compare private carriers on price, deductibles and terms.
We shop the market for you, no broker fees
What this policy can cover
The structure
Repairs to the home itself after earthquake shake damage, subject to your deductible.
Personal belongings
Coverage for your contents, usually as a limit you choose alongside the dwelling.
Loss of use
Additional living expenses if quake damage makes the home uninhabitable during repairs.
Private earthquake markets
Coverage through the private earthquake carriers we shop, compared on price, deductible and terms. A CEA policy is sold through a participating homeowners insurer, not through this request.
Built for California homeowners
- Owners near an active fault or on fill soil
- Anyone who could not afford to rebuild alone
- Older homes without a seismic retrofit
- Owners comparing a private policy with the quote they already hold
Earthquake with the California FAIR Plan
The FAIR Plan does not cover earthquake. A California Earthquake Authority policy can be written alongside it.
A companion CEA policy
The CEA policy is written as a companion to your FAIR Plan policy and needs its policy number. We quote it with the FAIR Plan.
Coverages that pair with this
Homeowners Insurance
The structure, everything inside it, and your liability as the owner of the place it happened.
Flood Insurance
Excluded from every standard home policy in every state, so it is bought separately or not at all.
Umbrella Insurance
Extra liability limit sitting above the home and auto policies you already carry, for a fraction of what raising each one costs.
Questions we get asked
Do I need earthquake insurance in California?
No law requires it, and standard homeowners policies exclude earthquake damage entirely. Given California's seismic risk, the question is whether you could afford to rebuild out of pocket. For many owners the answer makes the coverage worth pricing, even with a high deductible.
What is the difference between CEA and private earthquake insurance?
The California Earthquake Authority is a publicly managed, privately funded provider whose policies are sold through participating homeowners insurers. Private carriers also write earthquake coverage, sometimes with different deductibles, limits, or extras. We quote the private earthquake carriers we shop, and we tell you when a CEA quote from your homeowners insurer is worth setting beside them.
Why is the earthquake deductible so high?
Earthquake policies use a percentage deductible, often 10 to 25 percent of the dwelling limit, rather than a flat dollar amount. On an expensive home that is a large number, which is why the coverage is designed for a catastrophic rebuild rather than minor cracks. Lower deductible options exist at a higher premium.
Does homeowners insurance cover earthquakes?
No. Earthquake shake damage is a standard exclusion on homeowners policies across California. You need a separate earthquake policy or endorsement. Fire that follows a quake is the exception, since fire is a covered peril on the homeowners policy itself.
How much does earthquake insurance cost?
Cost depends on your home's location and soil, its age and construction, the dwelling limit, and the deductible you choose. Older homes and those near active faults generally cost more, while retrofitting can lower the premium. We quote it against your actual property.
Does earthquake insurance cover my belongings and living expenses?
Most policies let you add personal property and loss of use coverage alongside the dwelling limit. Personal property helps replace contents damaged in the quake, and loss of use pays additional living expenses while the home is repaired. The limits are yours to choose.
Can I get earthquake insurance for my condo?
Yes. Condo policies exclude earthquake too, and a private earthquake policy for a condo unit is priced on the personal property limit of your current condo policy. The association's master policy decides what happens to the building itself, so check whether it carries earthquake before you choose your limits.
Does this policy cover fire following a quake?
Fire is covered by your homeowners policy, not the earthquake policy, even when a quake starts it.
Does this policy cover land itself?
The land, and costs to stabilize or regrade it, are generally excluded.
Does this policy cover exterior features?
Pools, fences, and detached masonry are often limited or excluded, depending on the policy.
Does this policy cover flood or tsunami?
Water damage from flooding or a tsunami needs separate flood coverage.
Can you write this where I live?
We are currently licensed in California only. Start a quote if the business or risk is in California, and we will confirm eligibility before you spend time on it.
What happens after I start a quote?
Tell us about the coverage you need and complete the application. We use those details to approach suitable markets and may ask follow-up questions. Requesting a quote does not put coverage in force.
Start your quote online.
Fill in one short form or call us. No broker fees.