Farm buildings
Barns, outbuildings and other farm structures.
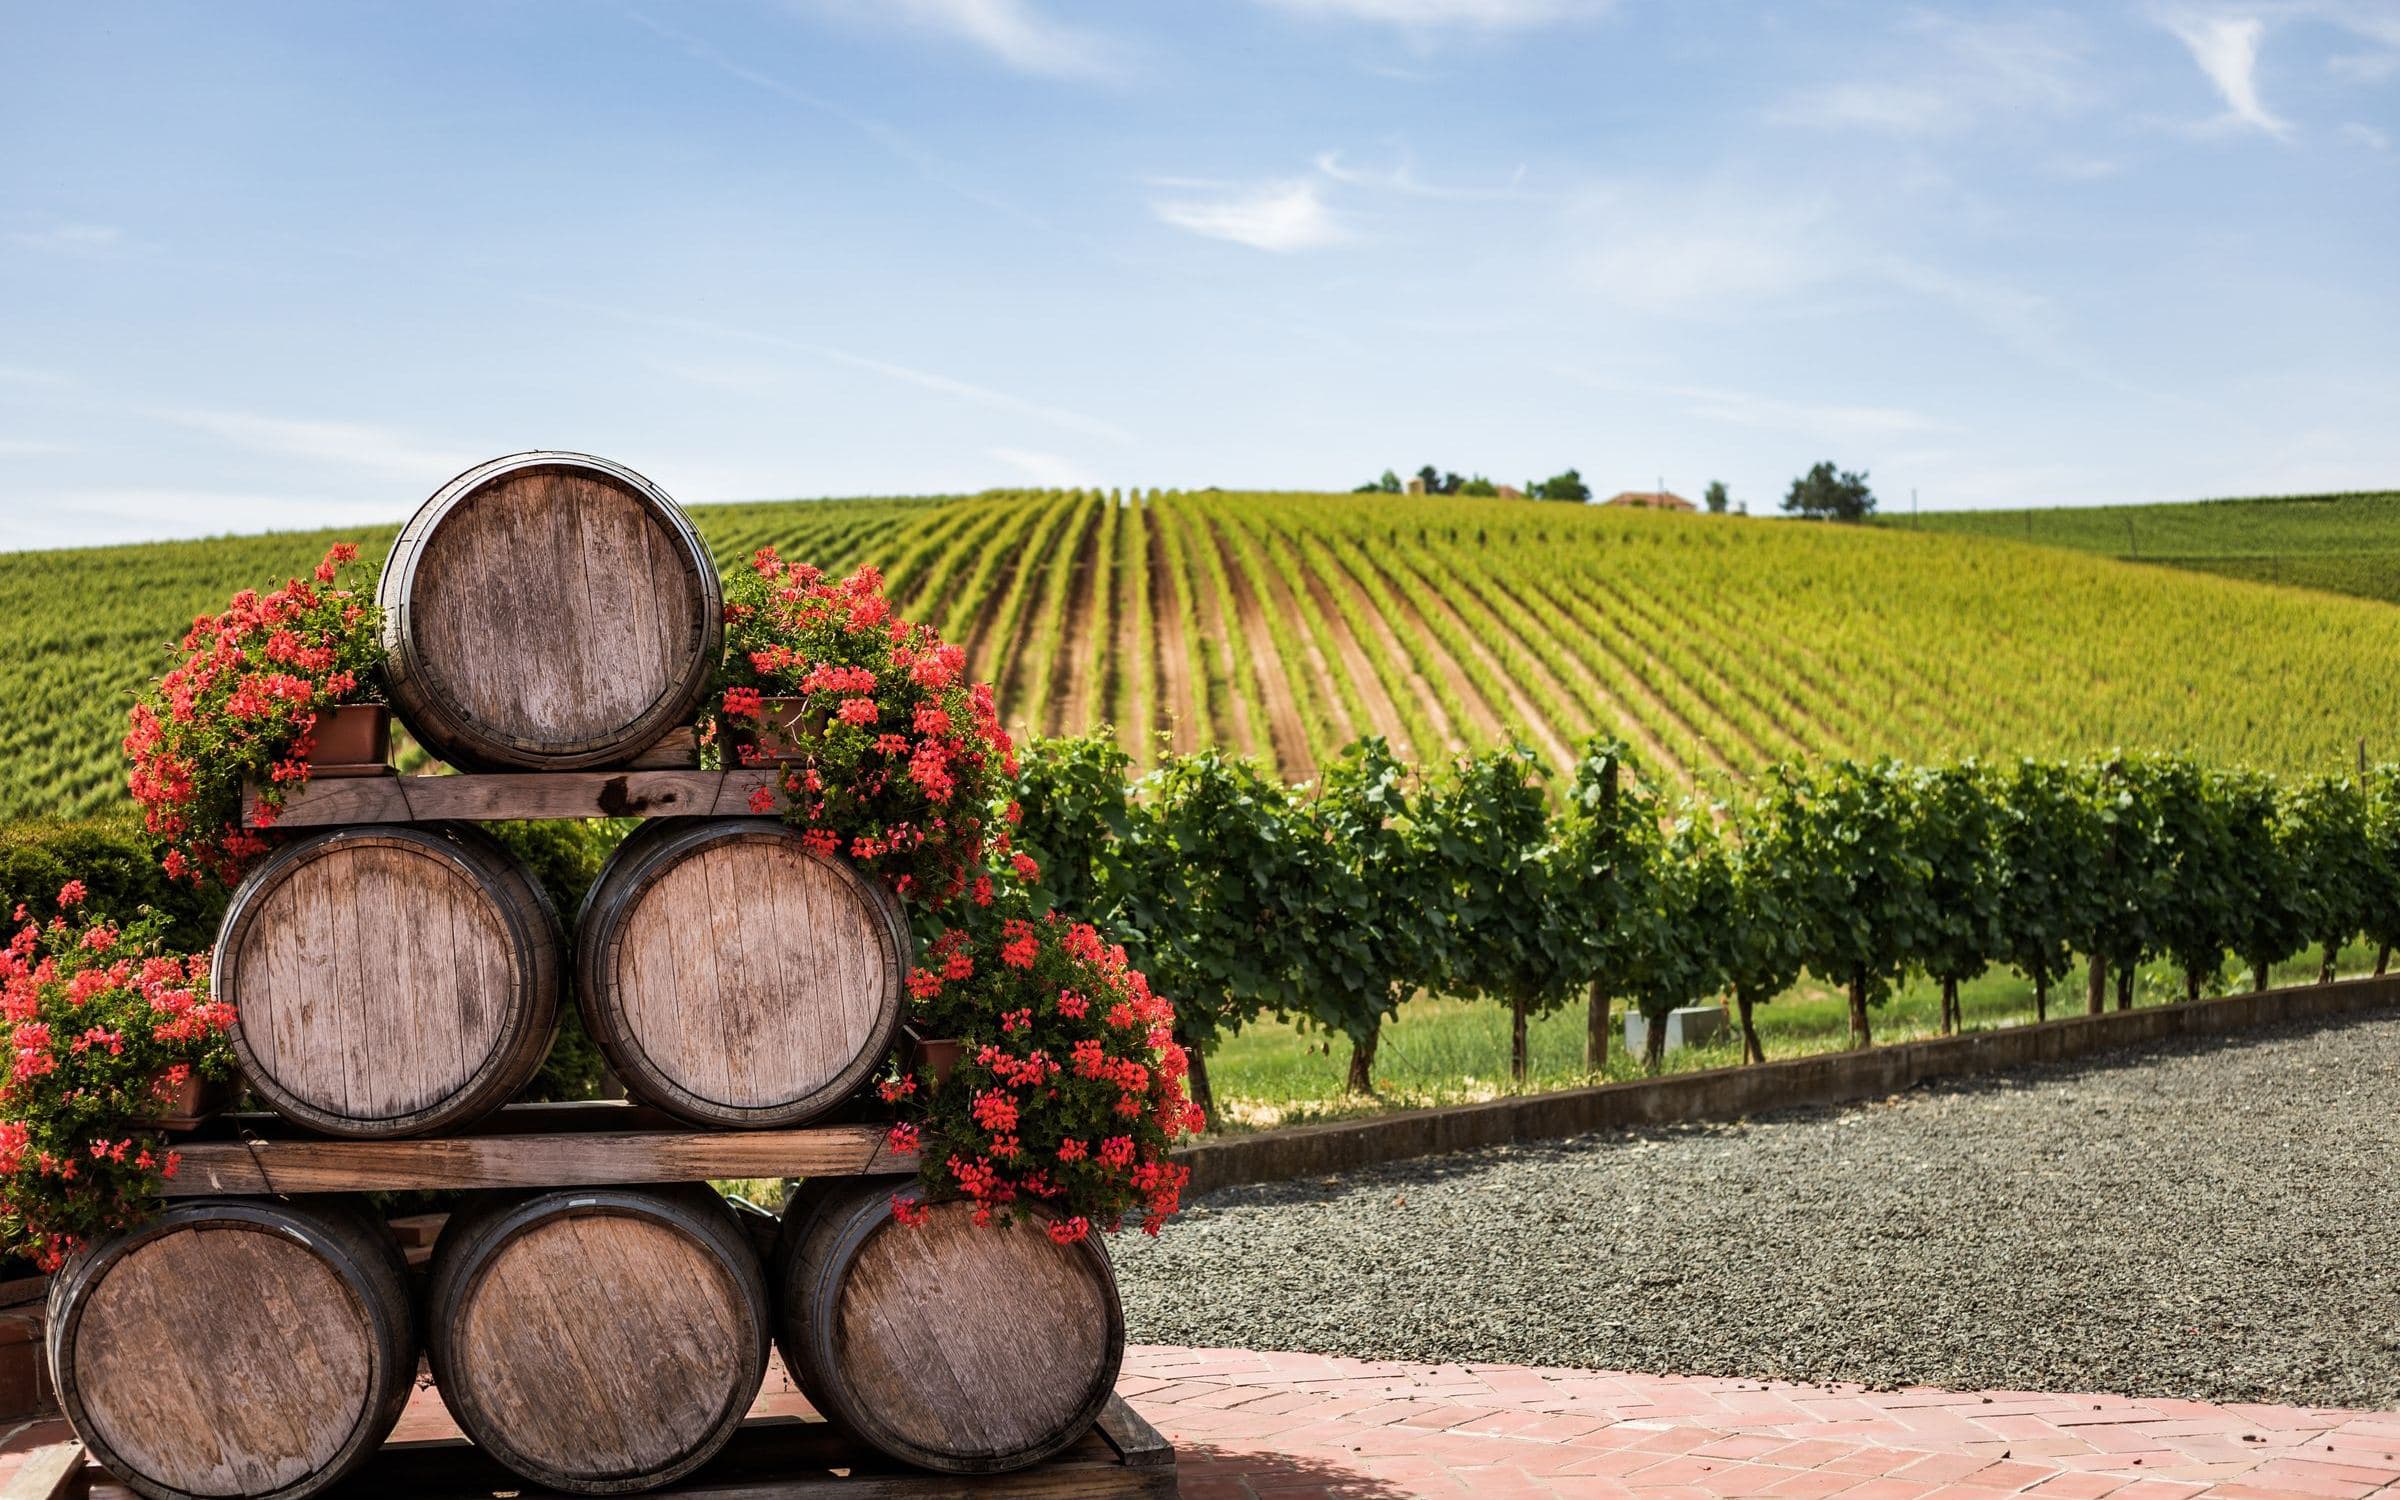
Barns, winery buildings and farm structures in fire country can go on the California FAIR Plan commercial fire policy. It covers the buildings, not crops, livestock or equipment.
Licensed in California
Menlo Insurance Services is the filed name of Opero Labs Inc. California license #6020106.
Eight brokers, one team
Our eight brokers work together as one Menlo team, so you can reach a person who understands your account.
Independent brokerage
We hold appointments with multiple carriers, so the quote is shopped rather than served from one shelf.
Barns, outbuildings and other farm structures.
Winery buildings, their contents and the income they earn.
Crops, livestock and farm equipment are not eligible on the FAIR Plan.
And up to $100 million per location.
Production, storage and tasting buildings.
With peak season limits for harvest and inventory.
Lost income while a covered loss is repaired.
Up to $20 million.
Up to $100 million.
$500 to $75,000, or 1% to 15% of the value.
A winery holds far more in the weeks after harvest. The FAIR Plan can raise the contents limit for those dates.
A higher business property limit between the dates you choose.
The income you lose while a covered loss is repaired.
A photo of each building and a diagram of the property.
Every FAIR Plan policy, from homes to commercial buildings.
Other business buildings, owned or leased.
The farmhouse you live in, on the FAIR Plan with DIC.
No. Crops, livestock and farm equipment are not eligible. The FAIR Plan covers the buildings and the business property inside them.
Fire, with extended coverage, vandalism and sprinkler leakage optional.
From $500 to $75,000, or 1% to 15% of the value.
No. The FAIR Plan insures property only. Liability is a separate policy.
We are currently licensed in California only. Start a quote if the business or risk is in California, and we will confirm eligibility before you spend time on it.
Tell us about the coverage you need and complete the application. We use those details to approach suitable markets and may ask follow-up questions. Requesting a quote does not put coverage in force.
A licensed broker can review eligibility and policy terms with you.