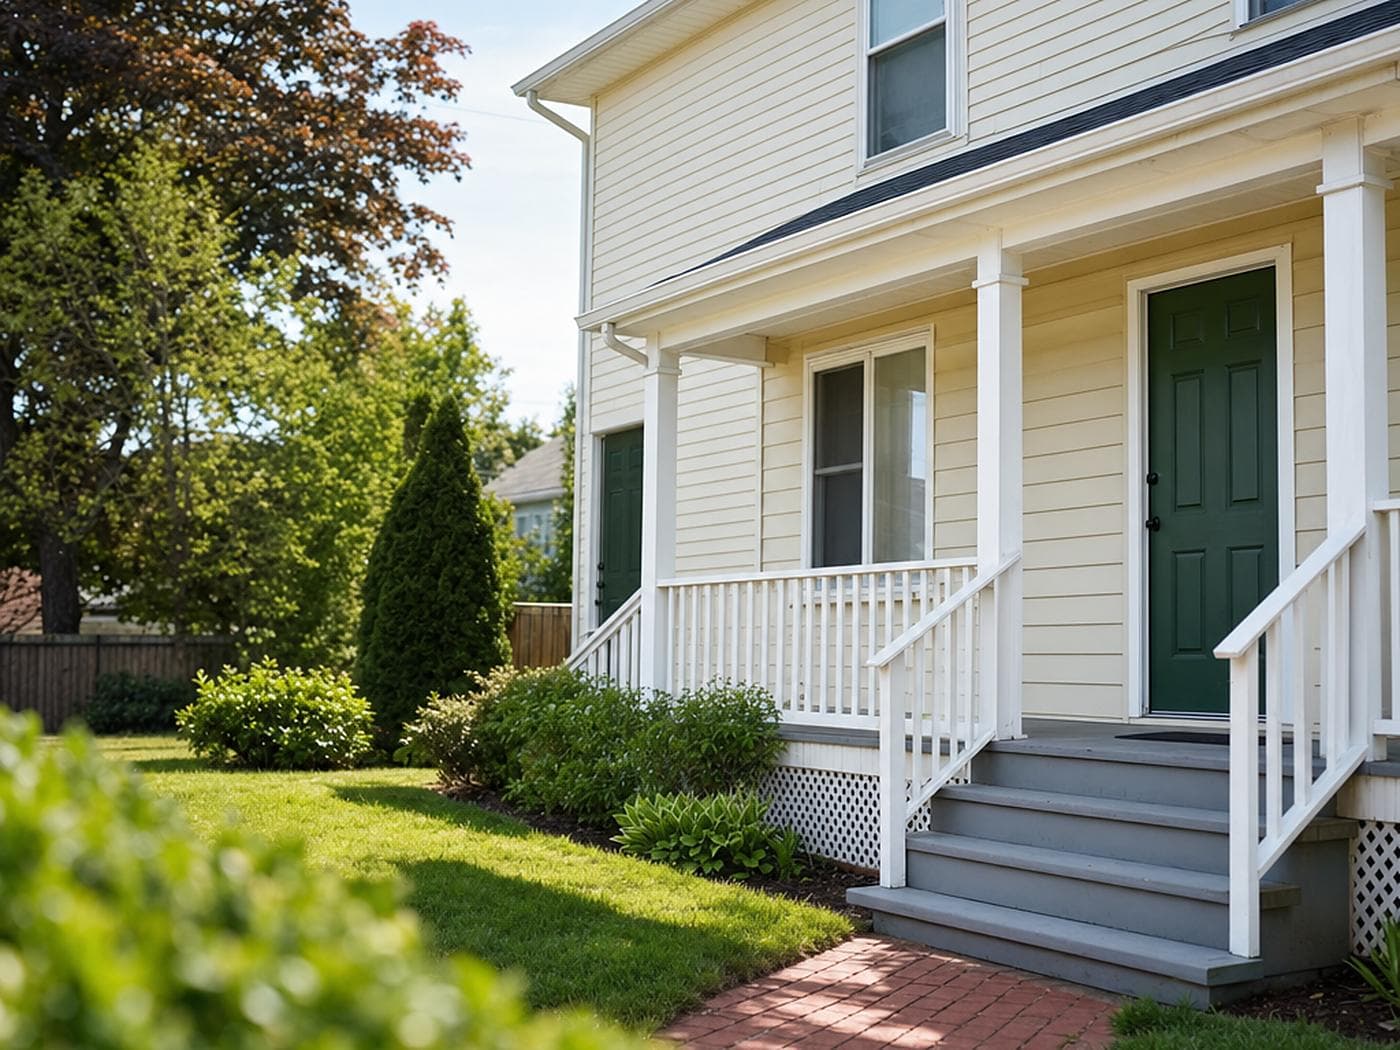
Landlord Insurance
Insure the home you rent out, the rent it earns and your liability. We shop carriers for the right coverage.
We shop the market for you, no broker fees

What this policy can cover
The building
Repairing or rebuilding a rental dwelling after fire, wind, and other covered losses, at today's construction costs.
Lost rental income
The rent you would have collected while a covered loss makes the unit unlivable during repairs.
Liability as an owner
If a tenant or visitor is injured on the property and you are found responsible.
Other structures
Detached items on the lot like a garage, fence, or shed.
When you need landlord insurance
You rent out a home
A homeowners policy assumes you live there.
Your lender requires it
No California law does, but a lender almost always will.
A small multi unit building
Quoted on the property's actual details.
Short term or seasonal
Reviewed through the dwelling fire market.
What changes your premium
These details help insurers assess your business and price the coverage. Terms and available options vary by insurer.
- The rebuild cost of the building
- How many units and how they are occupied
- Whether the rental is long-term or short-term
- Loss of rents coverage and how long it runs
- The deductible and any catastrophe deductible
Coverages that pair with this
Homeowners Insurance
The structure, everything inside it, and your liability as the owner of the place it happened.
Umbrella Insurance
Extra liability limit sitting above the home and auto policies you already carry, for a fraction of what raising each one costs.
Auto Insurance
Liability, damage to the car, and the other driver who turns out to have no insurance at all.
Questions we get asked
What is landlord insurance?
It is property and liability coverage for a home or unit you rent to someone else. It insures the building, the rent you would lose after a covered loss, and your liability as the owner. It is not the same as homeowners insurance, which assumes you live there.
How is landlord insurance different from homeowners insurance?
A homeowners policy assumes the owner occupies the home and covers their personal belongings. A rented property carries different risks, so a homeowners policy can be the wrong fit or even void a claim. Landlord insurance is built for the rental use and usually adds loss of rent.
How much does landlord insurance cost?
It depends on the property's location, age, construction, the coverage limits, and whether it is a single unit or a small multi-unit. Landlord policies often run somewhat higher than a comparable homeowners policy because of the added liability and loss-of-rent coverage. We quote it against your actual property rather than a flat rate.
Do I need landlord insurance in California?
No law requires it, but a lender almost always does, and renting a property on a standard homeowners policy risks a denied claim. For most owners it is the difference between a covered loss and paying out of pocket.
Should I require my tenants to carry renters insurance?
Yes, and you can make it a lease requirement. Your landlord policy does not cover a tenant's belongings, and renters insurance also carries liability that can keep small tenant-caused incidents off your policy. We can explain how to word the requirement.
Does landlord insurance cover loss of rent?
Most policies include fair rental value coverage, which pays the rent you would have received while a covered loss makes the unit uninhabitable during repairs. It does not cover rent lost because a tenant stops paying. We confirm the limit fits your actual rent.
Does this policy cover the tenant's belongings?
Your policy does not cover a renter's furniture or possessions. That is their renters policy, which you can require in the lease.
Does this policy cover flood and earthquake?
Both are excluded from a standard landlord policy and need separate coverage, which matters in California.
Does this policy cover wear, aging, and neglect?
Deferred maintenance and gradual deterioration are upkeep, not an insured loss.
Does this policy cover vacancy beyond policy limits?
A unit left empty for an extended period can change or suspend coverage. Tell us if it will sit vacant.
Can you write this where I live?
We are currently licensed in California only. Start a quote if the business or risk is in California, and we will confirm eligibility before you spend time on it.
What happens after I start a quote?
Tell us about the coverage you need and complete the application. We use those details to approach suitable markets and may ask follow-up questions. Requesting a quote does not put coverage in force.
Start your quote online.
Fill in one short form or call us. No broker fees.