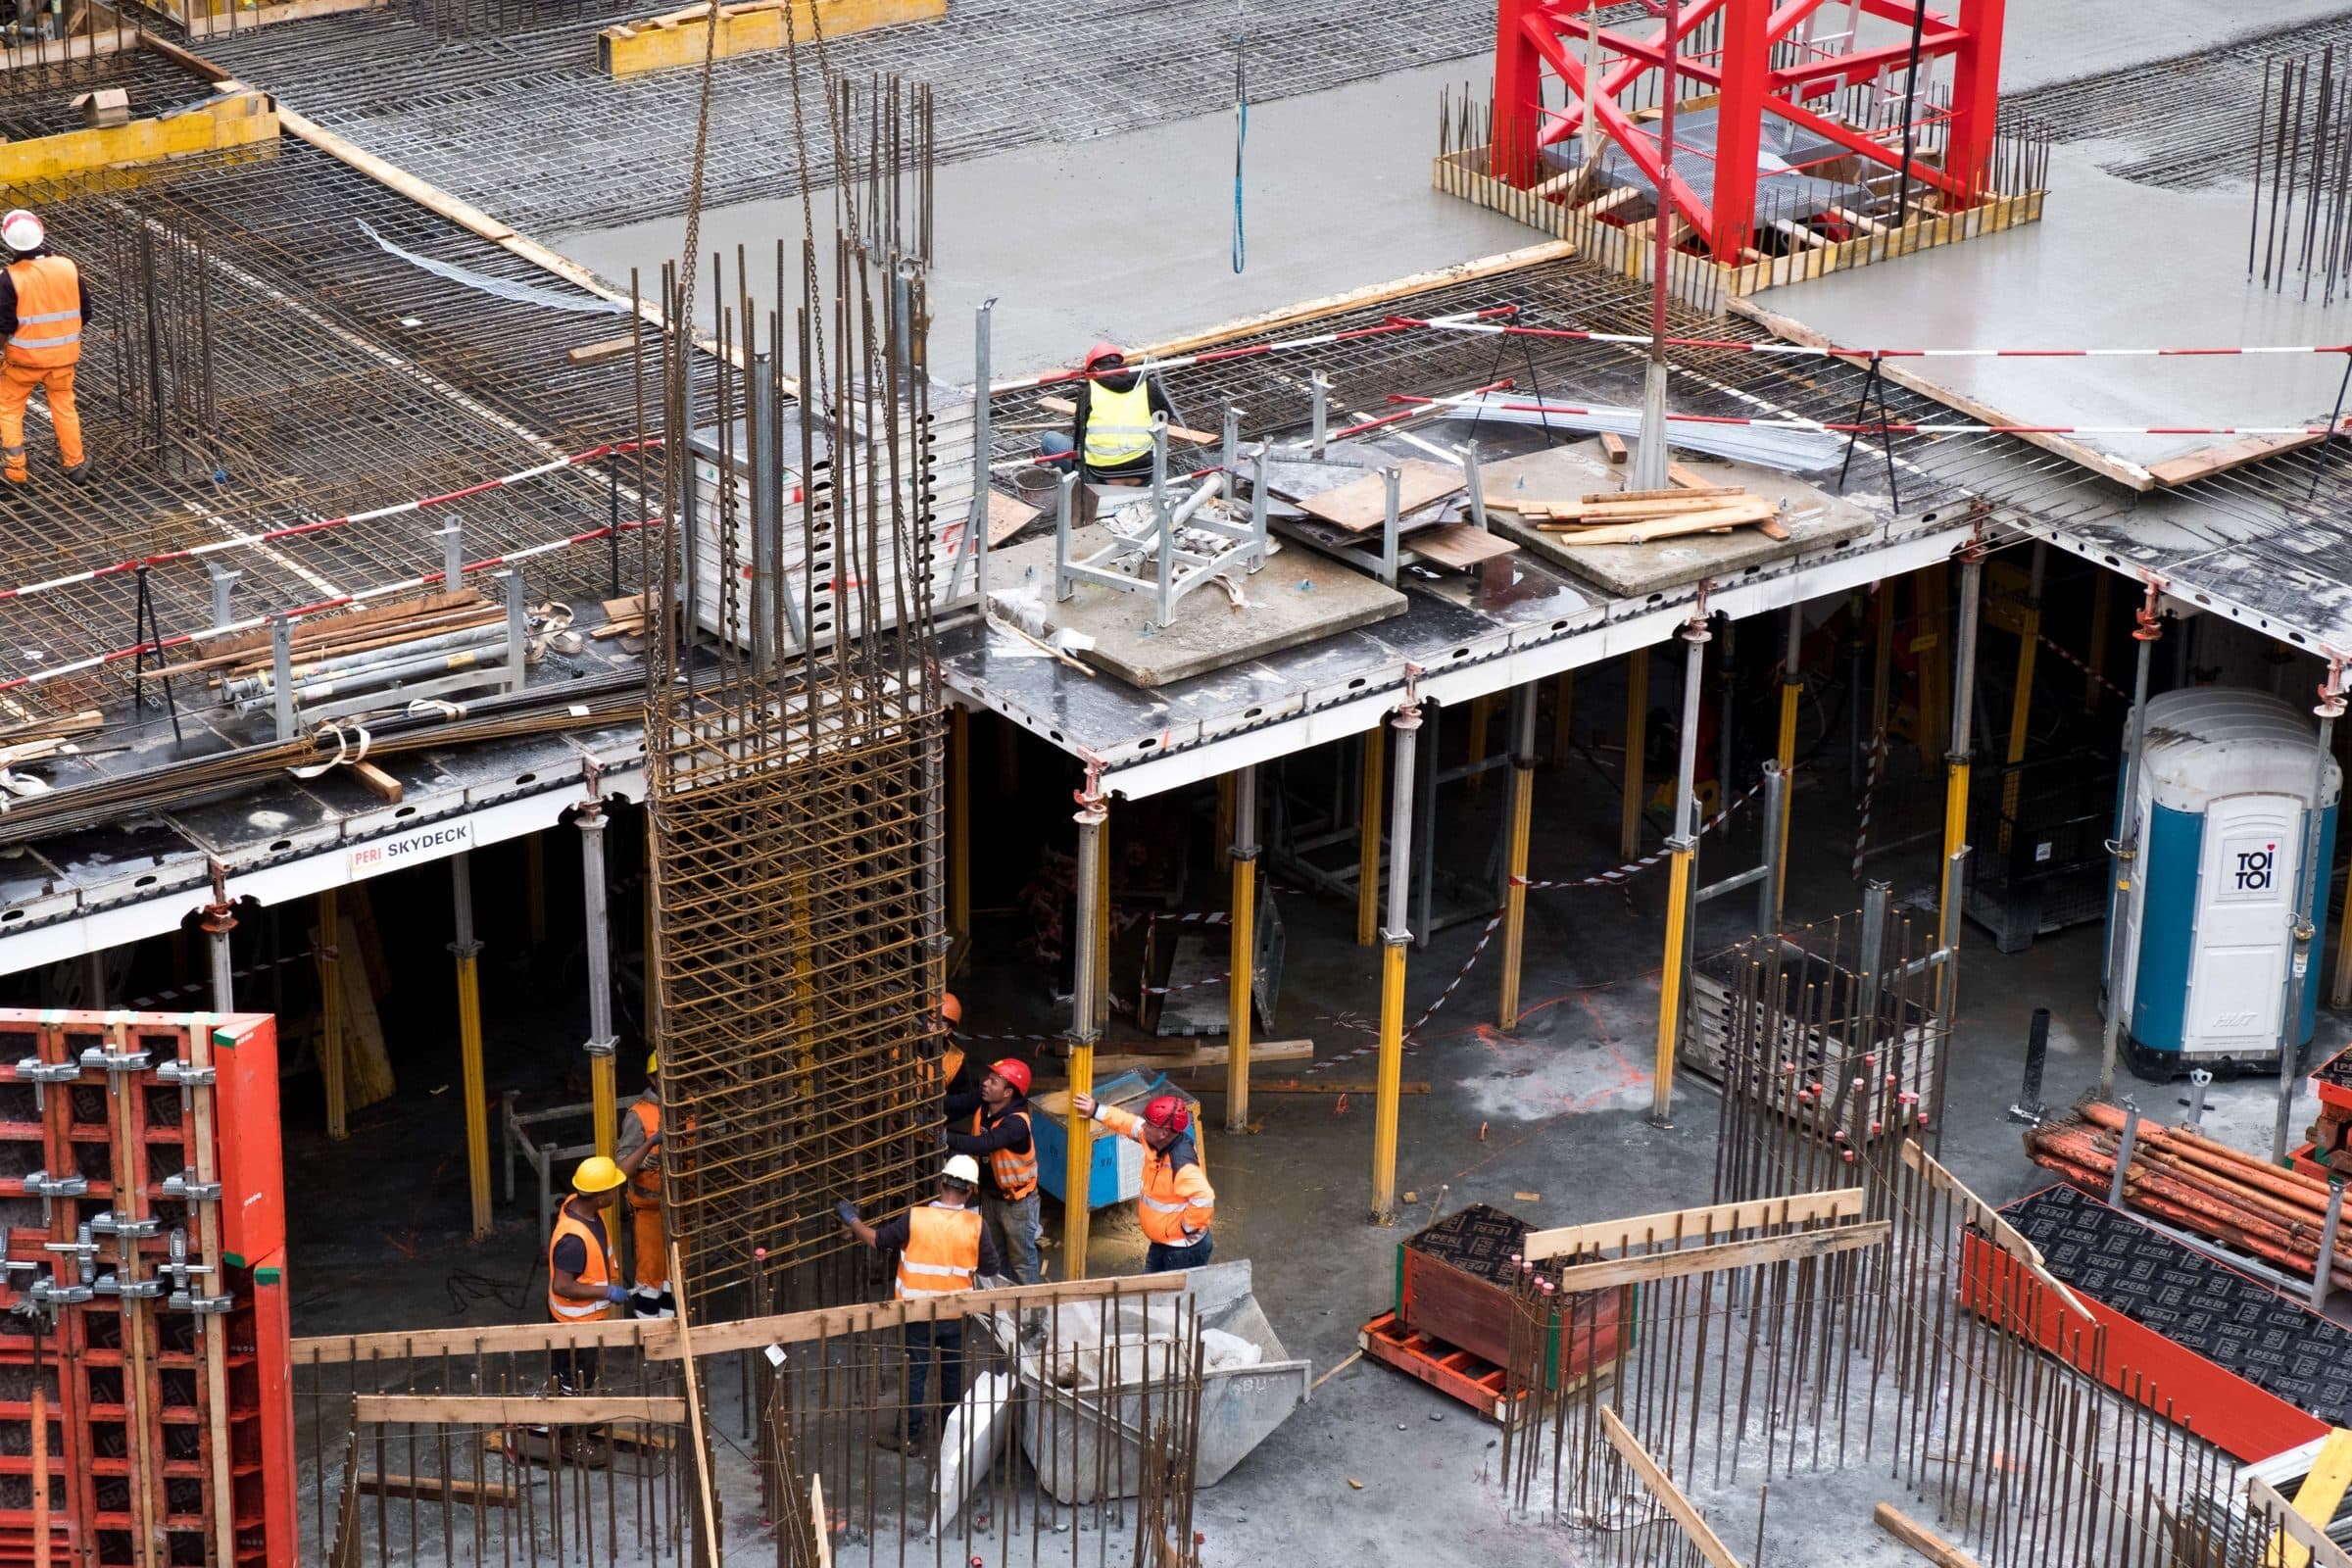
California workers' comp is priced per $100 of payroll, so the cost follows your payroll and the classification of each employee. Across the market, insurers collected an average of $1.56 per $100 of payroll in 2025, and the Insurance Commissioner's advisory pure premium rate for policies starting on or after September 1, 2026 is $1.65, up 6.6%.[1][2] At the 2025 average, an employer with $300,000 of payroll would pay about $4,680 a year, but actual rates vary greatly with the work: a clerical office pays much less than the average and a roofer much more.
This guide is for a California employer pricing a first policy, a renewal or a quote that looks too high. It explains how the premium is figured, what the 2026 numbers mean, the penalties for going without coverage, which insurers write small employers and how the audit settles your final cost. When you're ready, request a workers' comp quote and we'll price it with several insurers.
How is workers' comp premium calculated in California?
Every employee's payroll goes into a class code, and each class has a rate per $100 of payroll. The basic formula:
Premium = (payroll ÷ 100) × class rate × experience mod × schedule adjustments, plus small state assessments.
The class code does most of the work. The WCIRB publishes an advisory pure premium rate for each of about 500 classes, which includes both expected claims and the cost of handling them.[1] Each insurer then adds its own expenses and profit and files its own rates, and those filed rates are what you're charged. "The adopted rate is advisory, meaning that insurance companies are not bound by it and are free to set their own rates."[2]
Two adjustments come after the rate. Larger employers get an experience modification that compares their claims with others in the same classes. Insurers also apply schedule credits or debits for safety programs, experience and management. Our guides to California class codes and the experience mod explain both.
What do the 2026 numbers mean for my premium?
They show the direction of the market. For policies starting on or after September 1, 2026, the Commissioner adopted an average advisory pure premium rate of $1.65 per $100 of payroll, a 6.6% increase over 2025, while the WCIRB had proposed 10.4%.[2]
What employers actually pay has stayed lower. The Department of Insurance reports an average charged rate of $1.56 in 2025, down from $1.58 in 2024 and $1.60 in 2023. That was about 37.1% below the industry average filed manual rate of $2.48 as of January 1, 2026, which shows how much schedule rating and other credits discount the filed rates.[1]
Those credits may not be around forever. The Department reports accident-year combined ratios above 100% for six years, and 129% for accident year 2025, the highest since 2002.[1] When insurers lose money on claims, credits shrink at renewal even if the advisory rate doesn't change much.
Here is what each average would cost on $300,000 of payroll. These are statewide averages across all classes, not your rate:
| Rate used | Per $100 of payroll | Annual premium on $300,000 |
|---|---|---|
| 2025 average charged rate[1] | $1.56 | $4,680 |
| 2026 advisory pure premium rate[2] | $1.65 | $4,950 |
| Average filed manual rate, January 1, 2026[1] | $2.48 | $7,440 |
A clerical class sits well below these averages and construction classes far above them. That's why one wrong class code can move your premium more than any credit.
Do I need workers' comp if I have only one employee?
Yes. Labor Code section 3700 requires every employer except the state to secure workers' compensation, either through an authorized insurer or a certificate of consent to self-insure.[6] The number of employees does not affect this obligation.
There can be significant penalties. When the state issues a stop order, it also assesses $1,500 per employee, or twice the premium you should have paid if you were uninsured for more than one week in the past year, whichever is greater.[3] Knowingly failing to insure is a misdemeanor punishable by a fine of at least $10,000 and up to double the premium that was due.[4]
Contractors are subject to additional requirements. A licensed contractor must keep a workers' comp certificate on file with the CSLB, and C-8, C-20, C-22, C-39 and D-49 licensees need one regardless of whether they have employees.[7] From January 1, 2028, that requirement extends to almost every licensee.[7]
Which insurers write small employers in California?
Several admitted insurers in Menlo's market take small California employers online, which means quick quotes for common classes:
| Insurer | What it publishes |
|---|---|
| AmTrust | More than 500 eligible classes, over 350 bindable online. New ventures eligible in most classes. Pay-As-You-Owe billing[8] |
| Chubb Small Business | Nearly 400 classes. Up to $1 million employer's liability limits. Owner/officer inclusion or exclusion, waiver of subrogation[9] |
| THREE (Berkshire Hathaway) | One policy "that includes all of the coverage a business needs," issued by Berkshire Hathaway Direct Insurance Company, for small businesses in its target industries[10] |
| Pie | Pay-as-you-go with no initial deposit, billed on actual payroll[5] |
Businesses that small-business insurers decline, and larger accounts, go to the full market, including the State Compensation Insurance Fund.
How does the audit change my final cost?
The premium you initially pay is calculated from your estimated payroll. Once the policy expires, the insurer audits your actual payroll by class and then sends you either a bill or a refund for the difference. If you hired or gave raises during the year, expect a bill. Our workers' comp audit guide walks through it.
Pay-as-you-go billing avoids the surprise. According to Pie, it means no upfront deposit and premiums based on "your actual payroll, not an estimate," deducted automatically, so there's no additional bill after the audit if you grow.[5] AmTrust offers a similar Pay-As-You-Owe plan.[8]
How can I lower my workers' comp cost?
Get the classes right first. Clerical staff who never go to the field belong in the clerical class, not your main trade class, and the payroll split should be documented. Then:
- Keep payroll records by class so the auditor can see the split.
- Report owners correctly. Officers and owners may include or exclude themselves under the rules for their entity.
- Start a written safety and return-to-work program. It supports schedule credits and fewer claims.
- Report injuries quickly. Early care keeps claims small, and claims drive the experience mod.
- Compare several insurers every renewal, because each files its own rates and credits.
You can estimate a premium with our workers' comp calculator before you ask for quotes.
Frequently asked questions
How much is workers' comp per employee in California?
It depends on each employee's pay and class. At the 2025 average charged rate of $1.56 per $100, an employee earning $50,000 costs about $780 a year, but a clerical employee costs far less and a construction worker far more.[1]
Why did my California workers' comp rate go up in 2026?
Is the advisory pure premium rate what I pay?
No. It covers expected losses and claims handling only, and insurers aren't bound by it. You pay the insurer's filed rate after its credits and any experience mod.[2]
What is the cheapest workers' comp in California?
There is no single cheapest insurer, because each files its own class rates and credits. Accurate classes and payroll, a clean claims record and quotes from several insurers give the lowest price.
This guide is general information based on California law and Department of Insurance data published in 2026. Rates are set by each insurer's filings, and your policy's terms control. Menlo Insurance Services (CA license 6020106) is a licensed broker that may earn a commission on a placement.
References
- 1.California Department of Insurance. “Proposed Decision: September 1, 2026 Workers' Compensation Claims Cost Benchmark and Advisory Pure Premium Rates, REG-2026-00002.” Accessed 2026-09-27. https://www.insurance.ca.gov/0400-news/0100-press-releases/2026/upload/Workers-Comp-Proposed-Decision-7-10-26.pdf ↩
- 2.California Department of Insurance. “Commissioner Lara takes action to maintain stable workers' compensation market amid rising costs (July 10, 2026).” Accessed 2026-09-27. https://www.insurance.ca.gov/0400-news/0100-press-releases/2026/release024-2026.cfm ↩
- 3.California Legislative Information. “Labor Code section 3722.” Accessed 2026-09-27. https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?sectionNum=3722.&lawCode=LAB ↩
- 4.California Legislative Information. “Labor Code section 3700.5.” Accessed 2026-09-27. https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?sectionNum=3700.5.&lawCode=LAB ↩
- 5.Pie Insurance. “Pay-as-you-go with Pie Insurance.” 2022. https://6041899.fs1.hubspotusercontent-na1.net/hubfs/6041899/Carrier%20Store%20Resources/Pie/Pie-Insurance-Pay-as-You-Go.pdf ↩
- 6.California Legislative Information. “Labor Code section 3700.” Accessed 2026-09-27. https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?sectionNum=3700.&lawCode=LAB ↩
- 7.California Legislative Information. “Business and Professions Code section 7125 (current version and version operative January 1, 2028).” Accessed 2026-09-27. https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?sectionNum=7125.&lawCode=BPC ↩
- 8.AmTrust. “Workers' Compensation sell sheet (MKT5403).” 2024. https://6041899.fs1.hubspotusercontent-na1.net/hubfs/6041899/Carrier%20Store%20Resources/AmTrust/ANA_Workers-Compensation_Sell-Sheet_MKT5403.pdf ↩
- 9.Chubb. “ChubbSmallBusiness.com: Workers' Compensation.” 2026. https://6041899.fs1.hubspotusercontent-na1.net/hubfs/6041899/Chubb%20Commercial/ChubbSmallBusiness.com_WC_2_13.pdf ↩
- 10.THREE by Berkshire Hathaway. “Target Industries.” Accessed 2026-09-27. https://www.dropbox.com/scl/fi/2xs8qqoep4ikzbl1w6px7/THREE-s-Target-Industries.pdf?rlkey=8acznhbtbu9p4h0pbb88yx62m&st=0g7ir7dn&e=2&dl=0 ↩