Built 1950 or later
Wood frame, brick veneer, reinforced masonry, steel and reinforced concrete buildings qualify from 1950 onward, and concrete tilt up from 1980. Buildings on the historic registry are placed through a different market.
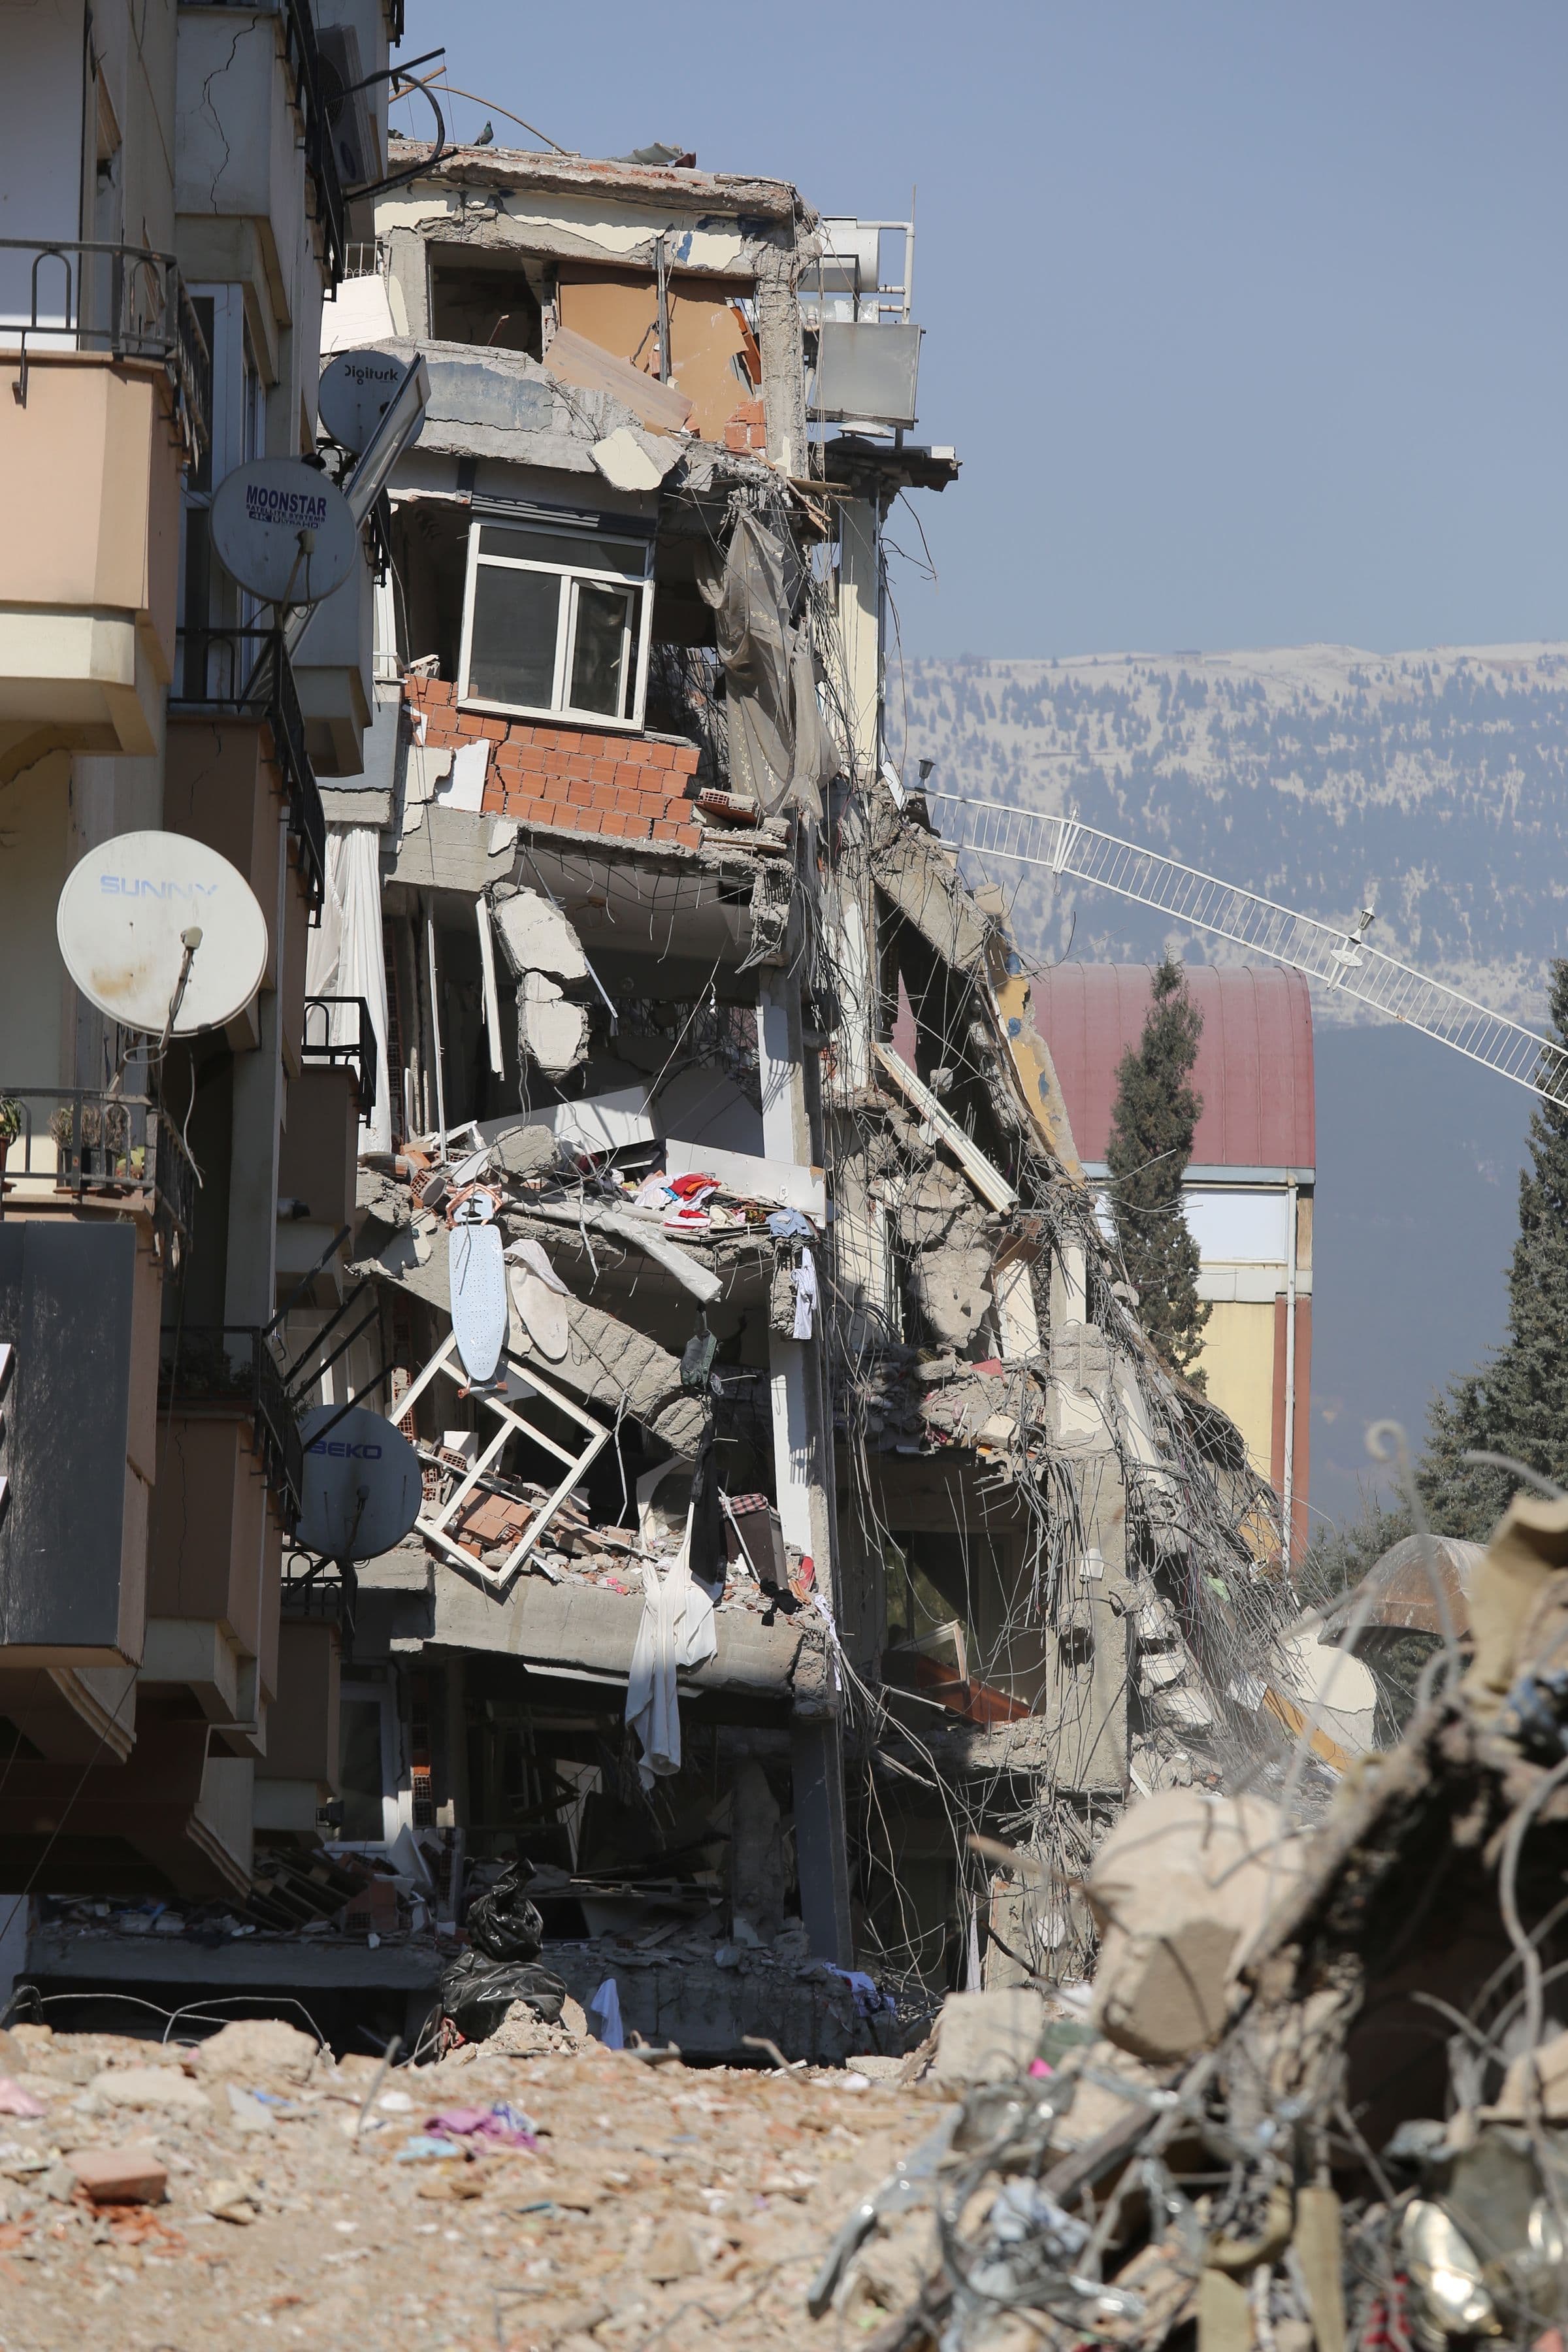
Add the earthquake coverage your association's master policy leaves out. We request quotes for condo associations and HOAs.
Wood frame, brick veneer, reinforced masonry, steel and reinforced concrete buildings qualify from 1950 onward, and concrete tilt up from 1980. Buildings on the historic registry are placed through a different market.
Building and contents values are listed at 100 percent of replacement cost, and policies are written at full limits with no coinsurance. It is the single most common reason a submission stalls, so the broker checks every value first.
Schedules up to about 21 to 24 million dollars in total insured values, depending on where the buildings sit. Larger communities are split across additional markets by the broker.
Written as a difference in conditions policy that picks up earthquake, sprinkler leakage, ensuing loss and foundations, with optional flood outside the highest risk flood zones.
A few questions about your business or home.
We compare carriers and read the forms line by line.
We pick the best policy and get you covered.
A typical association master policy covers fire and the other perils it lists and leaves earthquake out. Until that gap is either covered by insurance or formally declined, it stays with the board, and owners, buyers and lenders are increasingly asking which one it is.
Your master policy stops at earthquake damage, but the buildings still have to be rebuilt either way. A separate earthquake policy closes that gap, with its own limit and a percentage deductible that in this market runs from 2 to 20 percent.
No law forces an association to buy earthquake insurance, but the board still answers for the choice at budget meetings and in disclosure packets. A real quote on your actual buildings turns that conversation into a documented decision, whether you bind the coverage or decline it.
An underwriter prices the year built, the construction type, the number of buildings and units, and building values at full replacement cost. Values set below replacement cost stall more submissions than anything else, so your broker checks them before anything goes to a market.
A unit owner's interior, contents and loss assessment go on a personal earthquake policy beside the HO 6. It works best when the association carries a master earthquake policy.
Concrete tilt up from 1980.
Building and contents, no coinsurance.
About $24M. Depending on where the buildings sit.
These details help insurers assess your business and price the coverage. Terms and available options vary by insurer.
Almost never. The basic association master policy excludes earthquake damage, which is why HOA earthquake insurance is purchased as a separate placement with its own limit and percentage deductible.
No law requires an association to purchase it. The board assesses the exposure, and a documented quote supports the decision either way, in budget meetings and in disclosure packets.
The policy form commercial earthquake coverage is typically written on. A DIC policy sits alongside the master policy and covers the perils the standard forms exclude, earthquake most commonly, often with earthquake sprinkler leakage and optional flood on the same form.
Year built, construction type, the number of buildings and units, and building values at replacement cost. A licensed broker reviews each value before anything is submitted, since undervalued buildings are one of the most frequent reasons a submission stalls.
Association earthquake policies use a percentage deductible, ranging from 2 to 20 percent of the insured values. The board picks the point on that scale that fits its reserves, and the quote prices the options side by side.
The association still owes the rebuild its governing documents assign to it, so damage from the quake usually comes back to the owners as a special assessment, with each owner paying a share of the repair costs. A real quote turns that scenario into a number the board can act on before the first tremor.
No. A unit owner covers interior improvements, contents and earthquake loss assessment through a personal earthquake policy purchased alongside the HO 6, and that loss assessment coverage works best when the association carries a master earthquake policy above it. Call the number provided above and a licensed broker will route it properly.