One to four family dwellings others decline
Dwelling fire writes seasonal and secondary homes, short term and vacation rentals, tenant occupied houses and older dwellings that standard carriers shy away from because of occupancy, age or size.
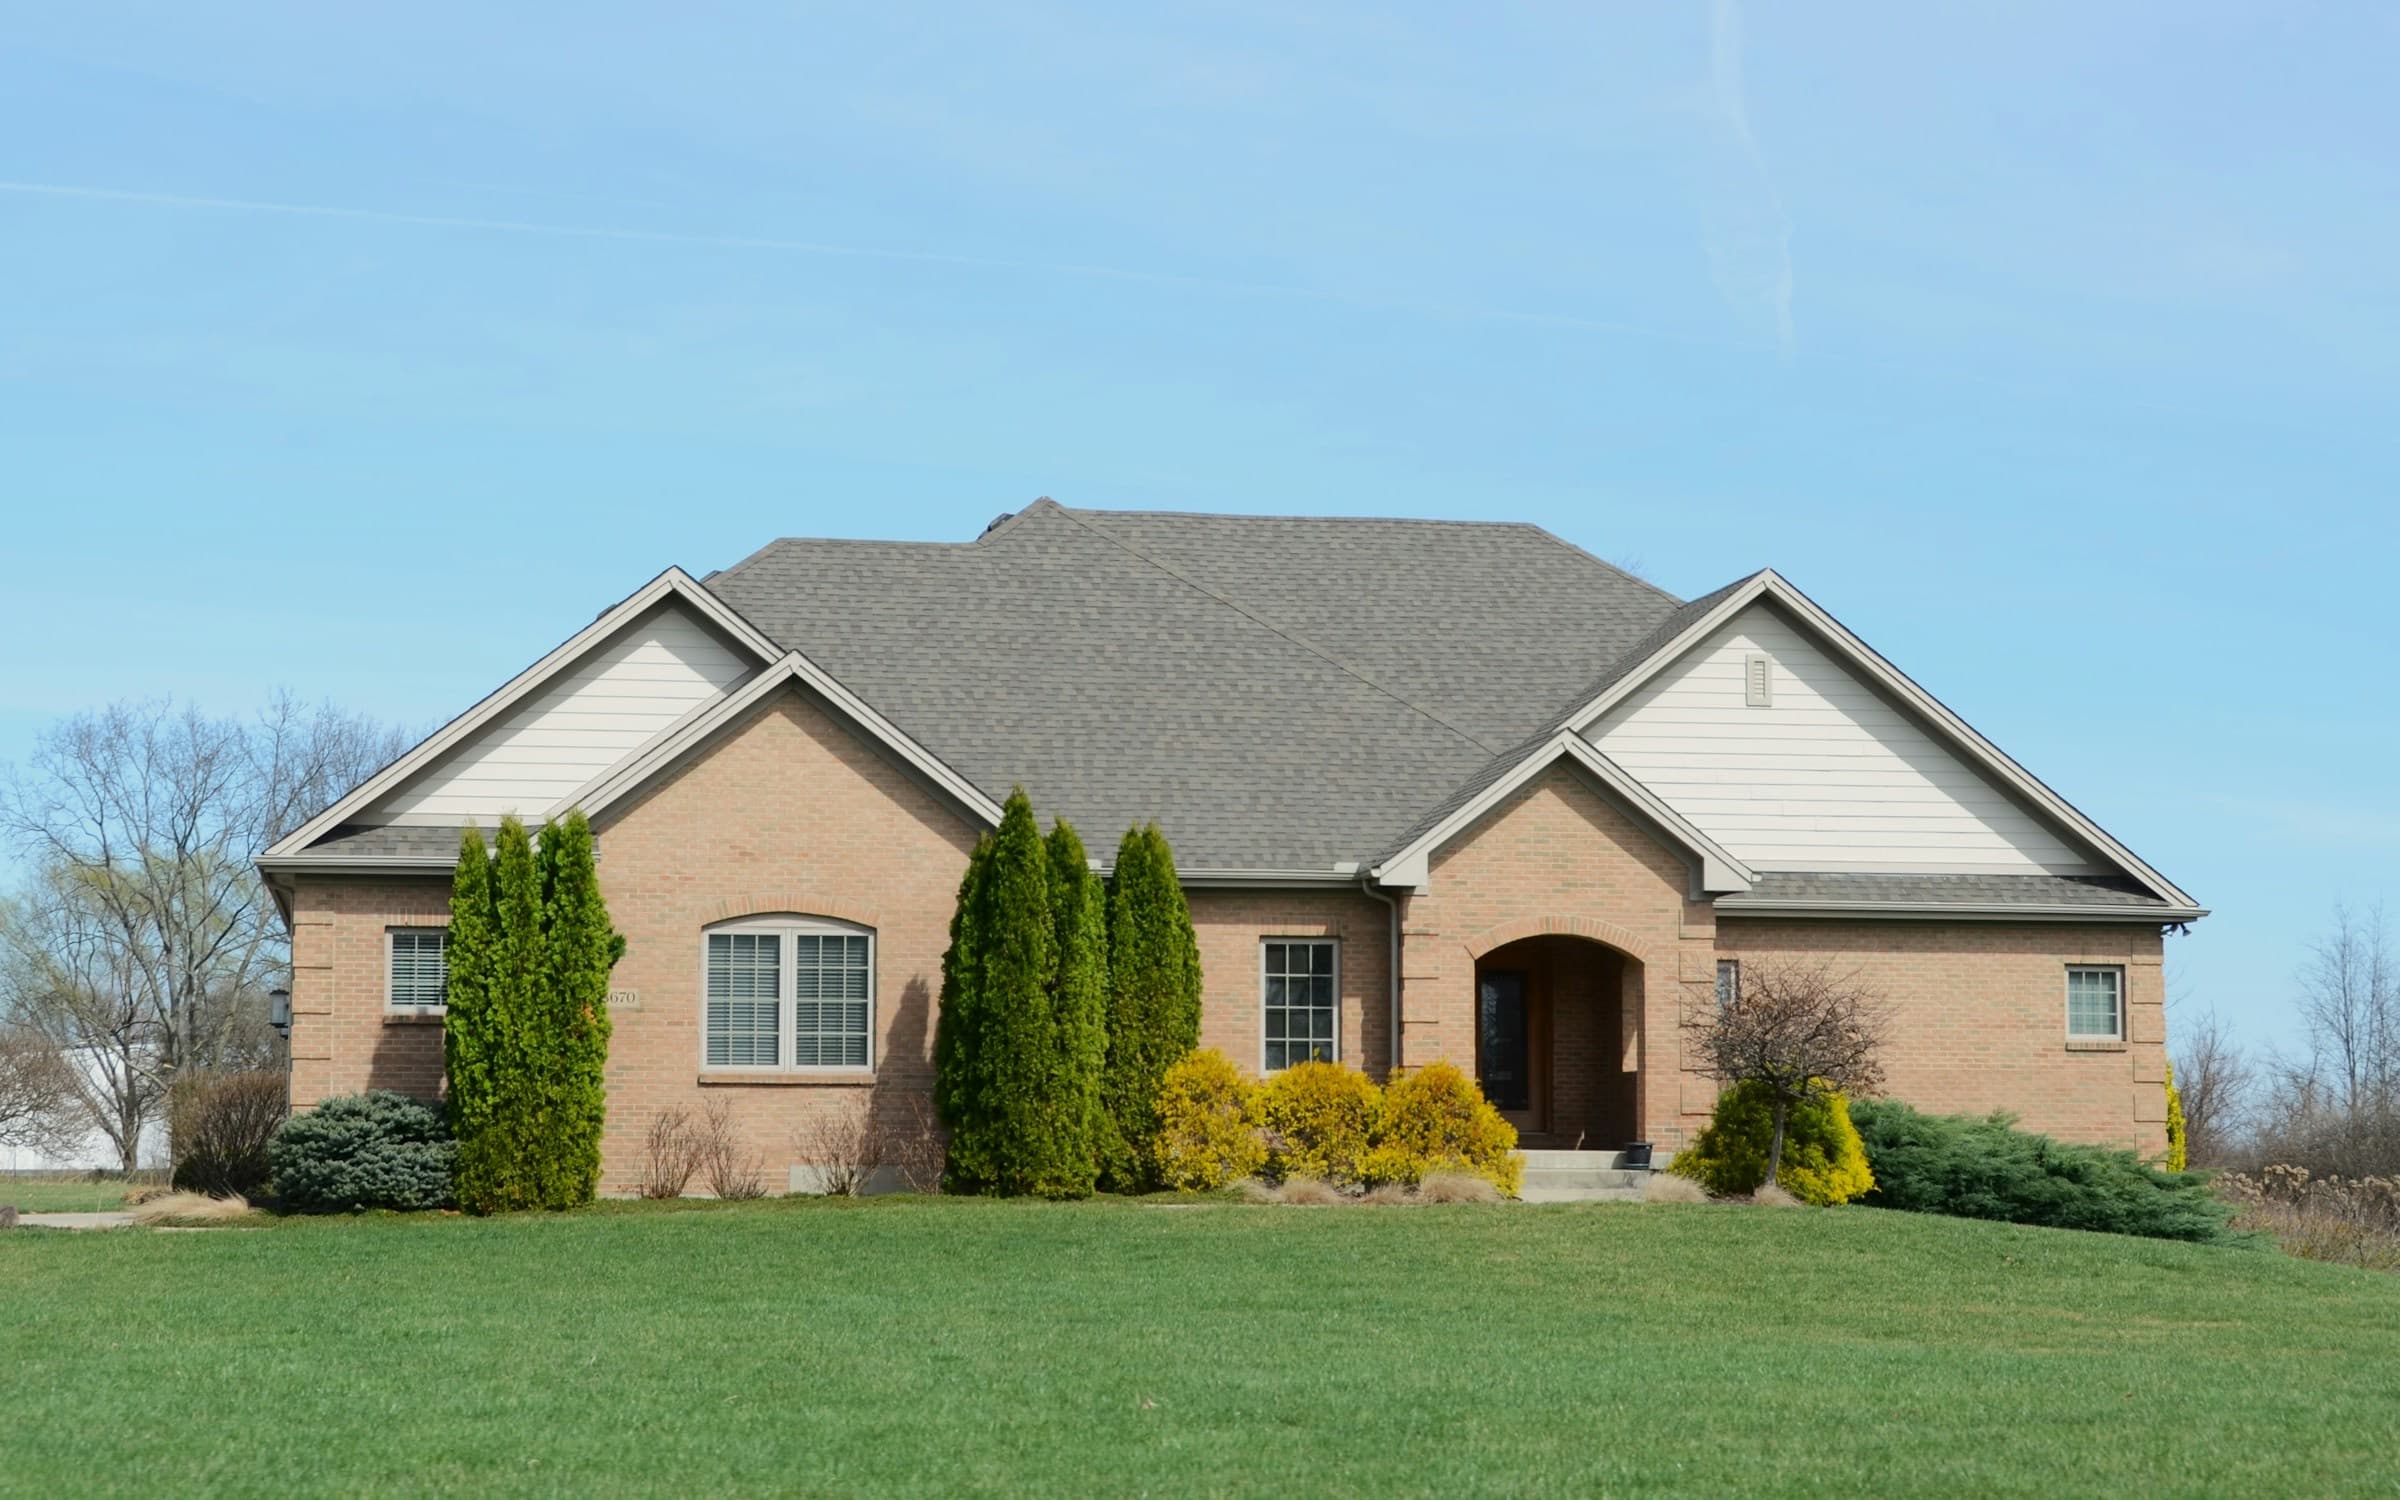
Insure the rental, second home or older house that standard insurers decline. We request quotes for you.
Dwelling fire insurance covers a house you do not live in full time, such as a rental, a second or seasonal home, a short term rental or an older home that standard insurers decline. It comes on the basic DP1 or the broader DP3 form, and liability can be added. One program we use writes dwellings up to $1.25 million.

Dwelling fire writes seasonal and secondary homes, short term and vacation rentals, tenant occupied houses and older dwellings that standard carriers shy away from because of occupancy, age or size.
Policies come on the basic DP1 form or the broader DP3 form. Liability for injuries on the property can be added, which makes a dwelling fire policy more complete than a bare landlord policy.
Plumbing, wiring, fuse panels, condemnation and existing structural damage can restrict individual programs. The broker checks them before choosing the market rather than applying one carrier's rule to every quote.
A dwelling fire policy can cover Coverage A dwelling, other structures, personal property, fair rental value and additional living expenses, with vandalism, theft, water damage and mold sublimit ladders on the DP3 form.
A few questions about your business or home.
We compare carriers and read the forms line by line.
We pick the best policy and get you covered.
Standard home policies decline a dwelling that is not your primary residence, is rented short term, or is simply old, the moment any one fact misses. Dwelling fire exists for exactly those facts.
Standard homeowners and landlord policies exclude short term rental activity, and a vacation rental gap needs a form written for it. The non-standard occupancy market we shop reviews the occupancy instead of declining it outright.
Galvanized plumbing, 100 amp panels or a roof past its life end most standard quotes. The specialty market prices those systems with age bands and deductible choices instead of a flat no.
Owner, tenant, seasonal, or short term rental each write differently, and the wrong occupancy on a standard policy can void a claim. The broker matches the occupancy to the form first.
Premises liability packages onto the property policy, with limits from $25,000 to $1 million.
This request quotes the FAIR Plan dwelling policy next to the other dwelling fire markets.
The FAIR Plan writes 1 to 4 unit homes that are tenant occupied, seasonal, or vacant for up to a year, up to $3 million per location.
Fair rental value can be added up to 50% of the dwelling limit. Landlord liability needs a separate policy, such as DIC.
On the basic DP1 or the broader DP3 form.
Detached structures on the lot.
Your belongings kept at the dwelling.
The rent you lose while a covered loss is repaired.
1 to 4
DP1 or DP3
$1K to $10K. Usually, depending on the market.
These details help insurers assess your business and price the coverage. Terms and available options vary by insurer.
The DP3 is the broad dwelling property form: it covers the dwelling against open perils, and it is the form that carries options like theft, vandalism and water damage sublimits. The DP1 is the basic form covering a named list of perils.
Yes, it can be reviewed. Short term and vacation rental occupancy goes to the non-standard occupancy market we shop, which is the occupancy standard landlord policies exclude. A dedicated vacation rental market is not yet available online, so declare the occupancy honestly and expect the broker to confirm which market can quote it.
Yes, it can. Premises liability packages onto the property policy with limits from 25 thousand dollars to one million, plus medical payments from one to ten thousand.
Condemnation and serious existing damage are the strongest shared barriers. Plumbing, wiring, fuse panels, occupancy and wildfire exposure vary by market, so those answers guide routing instead of automatically ending the quote.
If a covered loss makes the dwelling unrentable, the fair rental value coverage pays the rent you lose while it is repaired, which a bare property policy does not do.
The California FAIR Plan writes a named peril fire policy for 1 to 4 unit homes that standard insurers decline, including in wildfire areas. A DIC policy can cover what it leaves out, such as theft, water damage and liability.
We offer coverage in the states where we are licensed. Begin a quote with the address of your business or risk, and we'll let you know which markets can write that location before you spend much time on the questions.
Tell us about the coverage you need and complete the application. We use those details to approach suitable markets and may ask follow-up questions. Requesting a quote does not put coverage in force.
Fill in one short form or call us. No broker fees.