Existing buildings under renovation
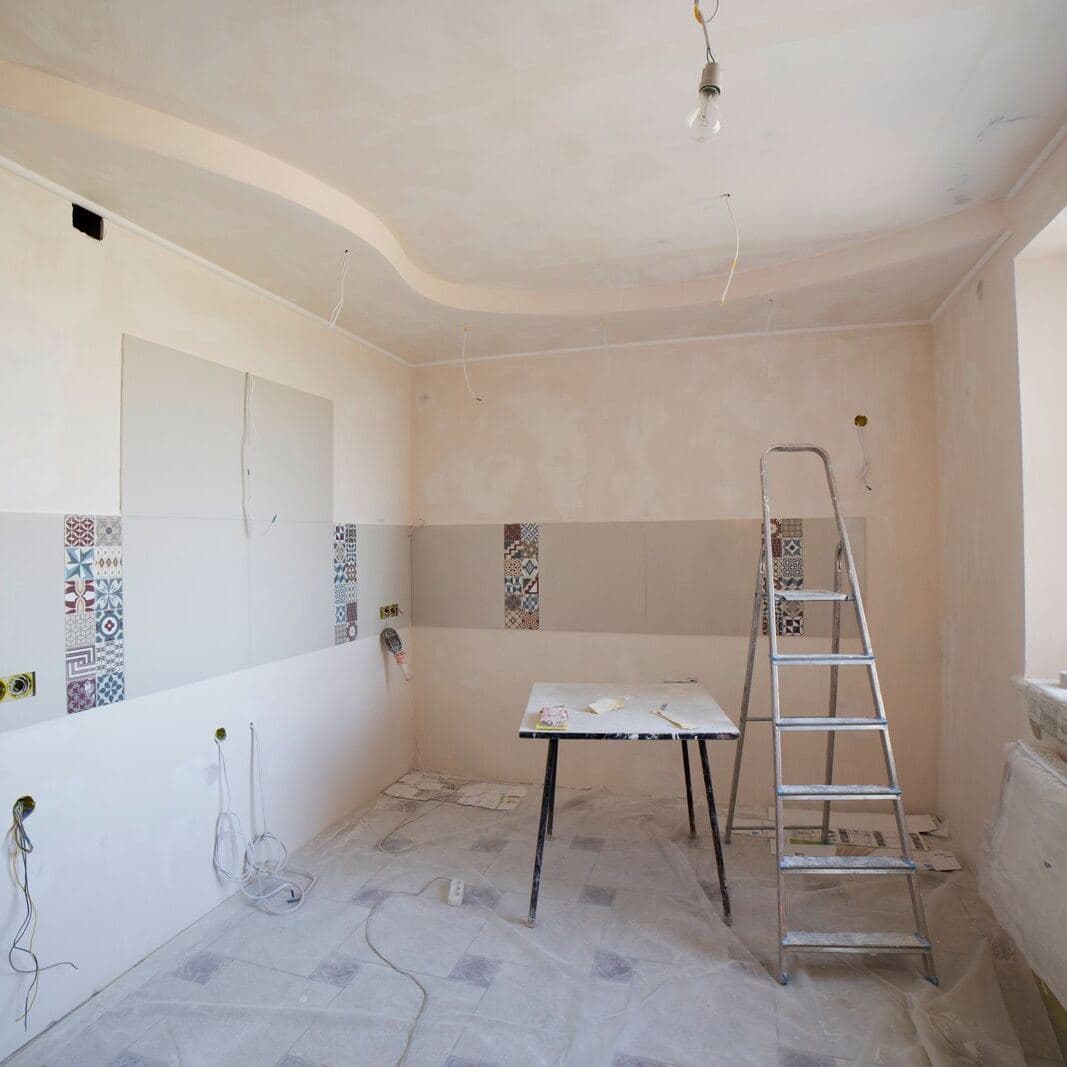
It covers residential and commercial buildings undergoing structural or non structural renovation, for the building owner or the contractor performing the work.
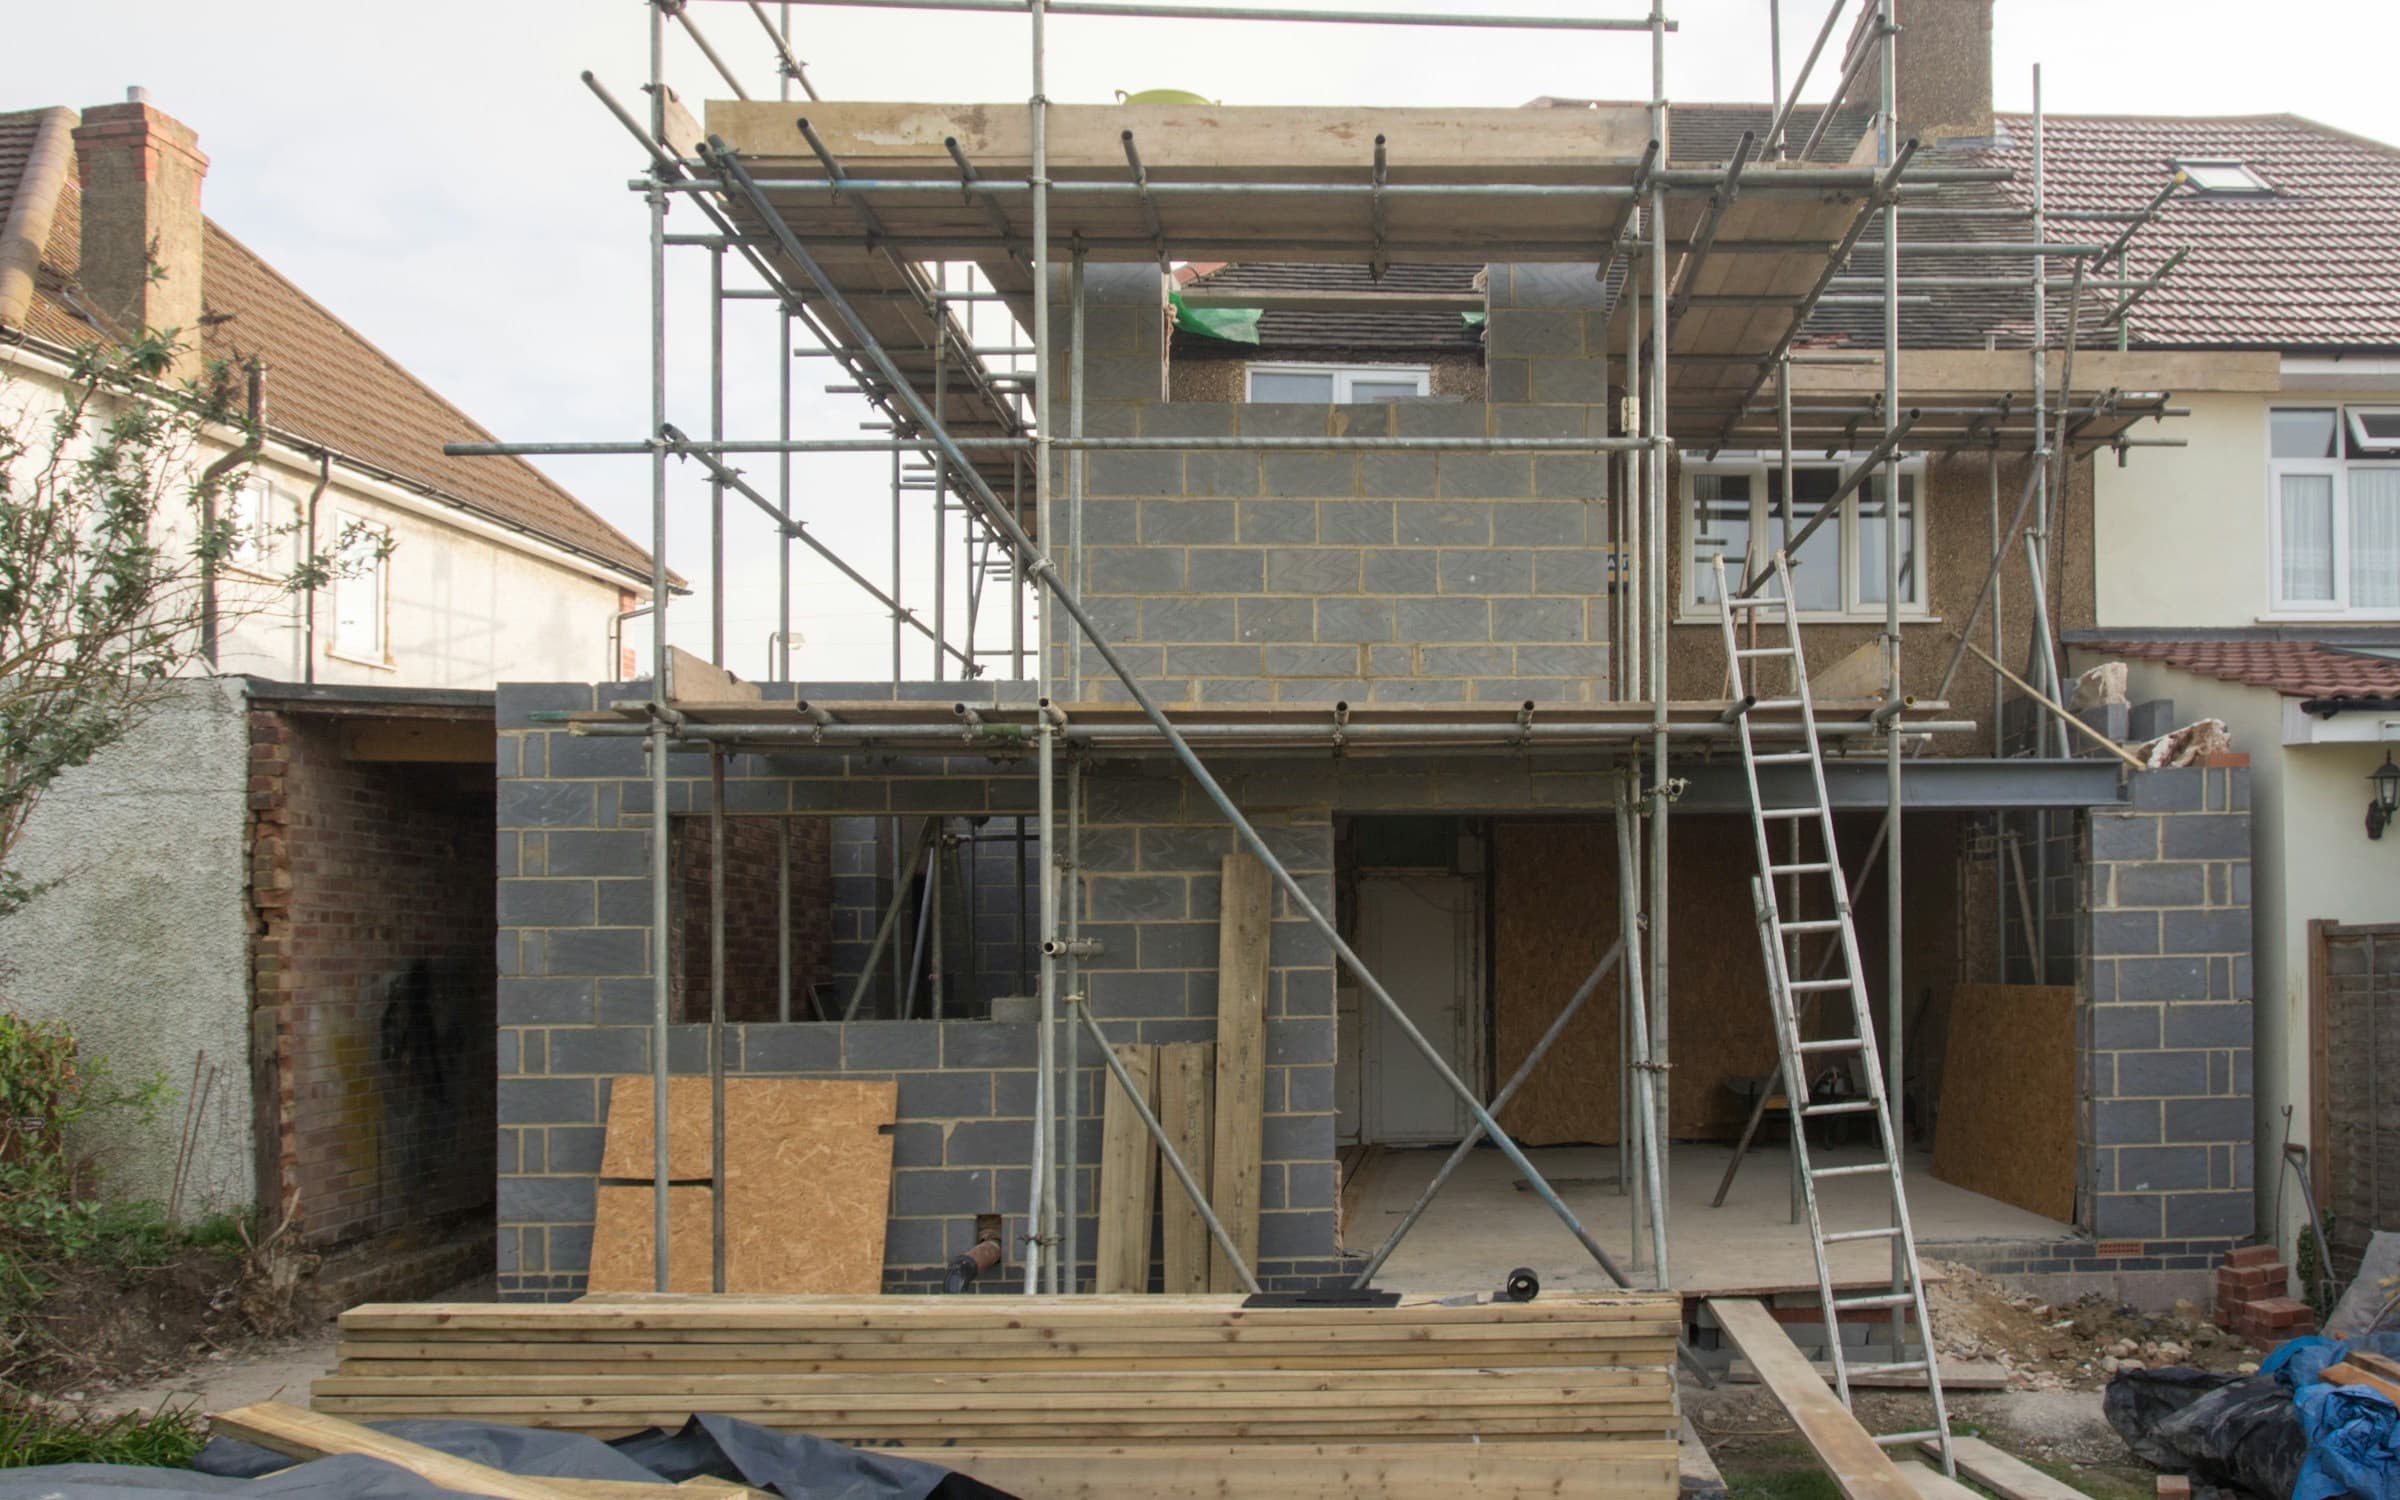
Protect the existing building and the new work while you renovate. We request quotes for your project.
Builders renovation insurance covers an existing building and the new work while it is being renovated, for the owner or the contractor doing the job. The programs we use write residential and commercial renovations, structural or not, including second story additions. One program writes renovation terms in one month steps up to 12 months.
It covers residential and commercial buildings undergoing structural or non structural renovation, for the building owner or the contractor performing the work.
Projects up to $5 million can be written, depending on the market, and terms and extensions vary by market. One program offers 3, 6, 9 and 12 month terms extendable to 18, with the renovation cost scheduled alongside the existing building limit.
The building's condition decides where it can go, and condemned or scheduled-for-demolition buildings are outside the current programs. Contractor licensing and who performs the work vary by market, so the broker routes those answers instead of applying one program's gate to all.
Renovation policies can include a replacement cost option on the existing building, theft of building materials, vandalism and malicious mischief, second story additions, post loss repair work, and project starts.
A few questions about your business or home.
We compare carriers and read the forms line by line.
We pick the best policy and get you covered.
A renovation is quoted on three facts: the value and condition of the building already there, the cost of the planned work and who will perform it. Those facts help a broker compare the terms each market can consider.
Provide the existing building value separately from the declared renovation cost. The requested coverage and proposed valuation terms need their own review.
Describe repairs, additions and structural changes. Identify who performs the work and whether the contractors hold the licenses required for it.
Have the planned start, expected completion and any work already underway ready. Policy terms and extensions depend on the market and require confirmation.
Describe the addition and any structural work. The broker reviews the scope with the available markets.
Start here for a new building or a construction project that needs a broader builders risk review.
Describe an empty commercial building and disclose any planned work during the vacancy review.
The national program that writes renovation terms month by month has a minimum premium of $400 per policy term. The existing building's value, the renovation cost and the term set the actual price above that.
Renovation insurance is builders risk for work on an existing building. Its application separates the existing building value from the project cost and asks about structural changes, occupancy and condition. For a new building, start with the builders risk request.
Either one can buy it, since the application can describe an owner or a contractor. Identify the applicant's role and the company performing the work so the broker can review the appropriate named insured and project requirements.
The term depends on the market and project, and one program writes renovation terms in one month steps up to 12 months. Provide your expected completion date and ask the broker to confirm the proposed term and extension conditions.
Materials theft can be covered, and it is a coverage to review with the broker. Ask which materials, locations, limits and deductibles the proposed policy includes before relying on that protection.
A second story addition can be requested: describe the addition and any structural work in the request. The broker reviews the scope, condition and timing with the available markets. Starting the application does not confirm acceptance of that project.
We offer coverage in the states where we are licensed. Begin a quote with the address of your business or risk, and we'll let you know which markets can write that location before you spend much time on the questions.
Tell us about the coverage you need and complete the application. We use those details to approach suitable markets and may ask follow-up questions. Requesting a quote does not put coverage in force.
A licensed broker can review eligibility and policy terms with you.