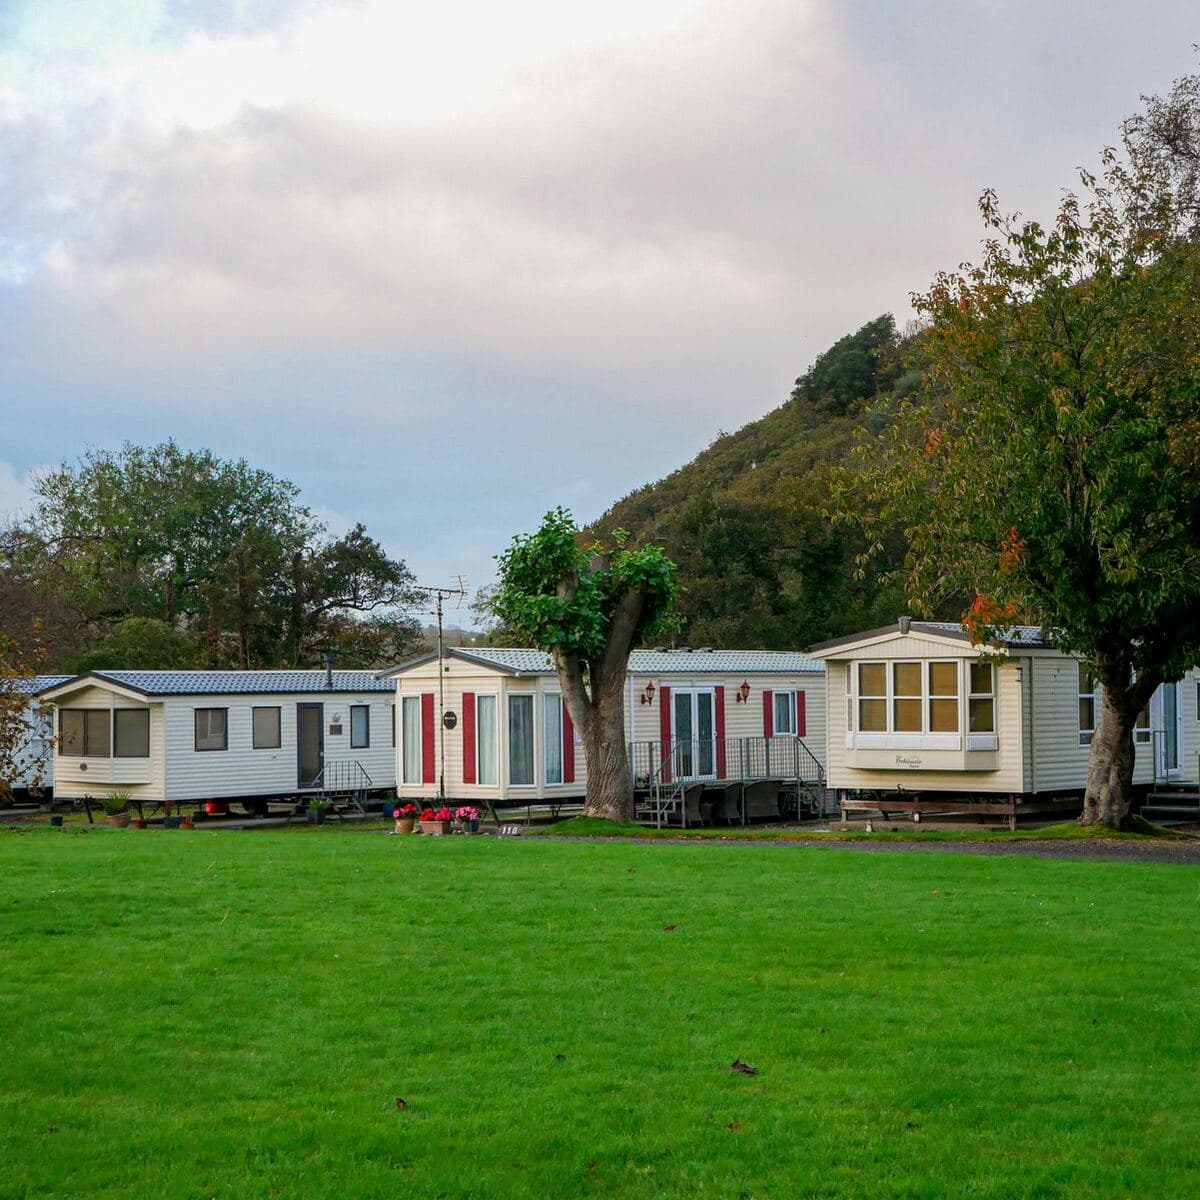
Older mobile homes can be insured in California; however, there are fewer insurers willing to take them, and most of those will only pay actual cash value rather than replacement cost. The dividing line is June 15, 1976: every manufactured home built after that date must be certified to HUD's federal construction and safety standards and carry a red HUD label, while earlier "mobile homes" were built before those standards existed.[1] As a result, specialty dwelling programs and the California FAIR Plan write many older units that standard home insurers would otherwise decline.
This guide is for owners and buyers of an older mobile or manufactured home in California, located in a park or on their own land. It covers how age affects your options, what insurers look for when you apply, where coverage comes from, and generally what it will cost. To get quotes, begin at our manufactured home insurance page.
Can you get insurance on a 30- or 40-year-old mobile home?
Yes, but the number of insurers drops as the home gets older. Many standard carriers set an age limit for new business, so a home from the 1980s or 1990s will often go to a specialty program. Green Shield, whose dwelling program lists manufactured homes in California among its target classes, shows both its DP-1 and DP-3 forms as available "up to 35 yrs; CA up to 40 yrs."[3] Its program also requires at least 100-amp circuit breakers and excludes knob-and-tube wiring, aluminum wiring, fuse panels and wood stoves as the primary heat source.[3] For many older units, those rules may prove more important than age itself.
What is the difference between a mobile home and a manufactured home?
The build date. HUD says that all manufactured homes built in the U.S. after June 15, 1976 must be certified by the manufacturer to its Manufactured Home Construction and Safety Standards, and each section carries a red certification label.[1] California's Department of Housing and Community Development describes the label as a 2-inch by 4-inch red metal plate on the outside rear of each section at floor level.[2] Homes built before that date are the ones insurers usually mean by "mobile home," and they are the hardest to place.
Find the label, or the data plate inside the home, before you ask for quotes. Insurers ask for the year built and the manufacturer, and the label is how they confirm it.
What do insurers ask about an older mobile home?
The same core questions every program uses, answered more carefully for an older home:
| Question | Why it matters |
|---|---|
| Year built and manufacturer | Sets eligibility; pre-1976 units have fewer options[1] |
| Tie-downs, or a permanent foundation | Wind and earthquake resistance; the FAIR Plan requires permanent anchoring[4] |
| Roof type and age | A frequent reason older homes are declined |
| Electrical panel and wiring | Breakers of at least 100 amps; no fuse panels, aluminum or knob-and-tube wiring on some programs[3] |
| Heating source | Wood stoves as primary heat are excluded on some programs[3] |
| In a park or on owned land | Park location affects fire protection and liability |
| Occupancy | Owner-occupied, rented, seasonal or vacant each price differently |
Who insures older mobile homes in California?
Three kinds of markets, in this order:
- Specialty manufactured-home insurers. National programs built for manufactured homes, such as Foremost's, write owner-occupied units with homeowners-style coverage, including additional living expense of 20% of the dwelling limit.[7]
- Dwelling fire programs. Green Shield writes manufactured homes in California on DP-1 or DP-3 forms, with other structures at 20% of the dwelling limit, contents at 50%, and liability up to $1 million available.[3] Our guide to DP-1 vs. DP-3 explains the two forms.
- The California FAIR Plan. It writes mobile homes that are permanently anchored to a foundation; an unanchored mobile home is ineligible.[4] Coverage is named perils only, with no liability, theft or water damage, so owners usually add a DIC policy.[8]
Menlo quotes older manufactured homes through Green Shield and the California FAIR Plan.
How much does insurance for an older mobile home cost?
In California, mobilehome policies averaged $1,164.64 a year in 2025 across 290,099 policies, according to the Department of Insurance's annual data call.[6] That average applies to all ages and values of homes, so an older unit in a high fire risk area can cost more. Mobilehome owners also had the highest earthquake take-up rate of any residential group, at 18.95%, with an average earthquake premium of $339.68.[6]
Deductibles can be percentage-based. For example, Foremost's updated manufactured home policy offers new-business deductibles ranging from 0.5% ($500 minimum) to 5% ($3,000 minimum) of the dwelling limit.[9] Ask each insurer whether its deductible is a flat dollar amount or a percentage.
Will insurance pay to replace an older mobile home?
Typically not the full replacement cost. Older units are commonly insured at actual cash value, which subtracts depreciation. The FAIR Plan's dwelling replacement cost option explicitly excludes mobile homes.[5] Ask whether a program offers replacement cost for your year and, if not, set the dwelling limit as close as possible to what a comparable home would cost to buy and place, not what you paid for your home years ago.
Frequently asked questions
What is the oldest mobile home that can be insured?
What makes a mobile home uninsurable?
Does the California FAIR Plan cover mobile homes?
Who registers mobile homes in California?
The Department of Housing and Community Development (HCD) titles and registers mobilehomes and manufactured homes, not the DMV. A home installed on a foundation system is no longer registered by HCD.[10]
This guide is for educational purposes and summarizes HUD and California HCD information, Department of Insurance data, California FAIR Plan documents and carrier program sheets. Eligibility and prices change, and your policy's terms control. Menlo Insurance Services (CA license 6020106) is a licensed broker and a registered FAIR Plan broker. It may earn a commission on a placement and does not guarantee that any coverage or price will be available. Some dwelling programs are written by non-admitted insurers, which are not backed by the California Insurance Guarantee Association. Each quote names its insurer and whether it is admitted.
The Bottom Line
An older mobile home can be insured, but the build date, anchoring, roof and wiring decide where.[1][3] Look for specialty manufactured-home and dwelling programs first, keep the FAIR Plan as the fallback for anchored homes, and expect actual cash value on older units.[4][5]
References
- 1.U.S. Department of Housing and Urban Development. “Manufactured Housing Homeowner Resources.” Accessed 2026-09-27. https://www.hud.gov/hud-partners/manufactured-home-resources ↩
- 2.California Department of Housing and Community Development. “Where to Look for an Insignia or HUD Label.” Accessed 2026-09-27. https://www.hcd.ca.gov/building-standards/mh/insignia/location ↩
- 3.Green Shield Risk Solutions. “Dwelling Fire: Specialty Lines program sheet.” 2026. https://6041899.fs1.hubspotusercontent-na1.net/hubfs/6041899/Green%20Shield%20Risk/Dwelling%20Fire-%20Specialy%20Lines.pdf ↩
- 4.California FAIR Plan Association. “Broker policy system, Dwelling Fire application (mobile home permanently anchored to the foundation), reviewed by Menlo.” Accessed 2026-09-25. https://www.cfpnet.com/ ↩
- 5.California FAIR Plan Association. “Optional Dwelling Replacement Cost Addendum (CFP-RCAD-2): mobile homes not eligible.” 2016. https://www.cfpnet.com/wp-content/uploads/2021/06/RCAD-2%2008%202016.pdf ↩
- 6.California Department of Insurance. “Earthquake Premium and Policy Count Data Call: Summary of 2025 Residential Totals (edition 7/03/2026).” 2026. https://www.insurance.ca.gov/0400-news/0200-studies-reports/0300-earthquake-study/upload/EQEXP2025Summary.pdf ↩
- 7.Foremost Insurance Group. “Manufactured Home Coverage Comparison.” 2017. https://6041899.fs1.hubspotusercontent-na1.net/hubfs/6041899/Carrier%20Store%20Resources/Foremost/Foremost%20Manufactured%20Home%20Coverage%20Comparison.pdf ↩
- 8.California FAIR Plan Association. “Dwelling policies.” Accessed 2026-09-27. https://www.cfpnet.com/policies/dwelling/ ↩
- 9.Foremost Insurance Group. “Manufactured Home Policy Highlights.” 2025. https://6041899.fs1.hubspotusercontent-na1.net/hubfs/6041899/Carrier%20Store%20Resources/Foremost/Manufactured%20Home%20Policy%20Highlights.pdf ↩
- 10.California Department of Housing and Community Development. “Registration & Titling.” Accessed 2026-09-27. https://www.hcd.ca.gov/mmh/registration-titling ↩