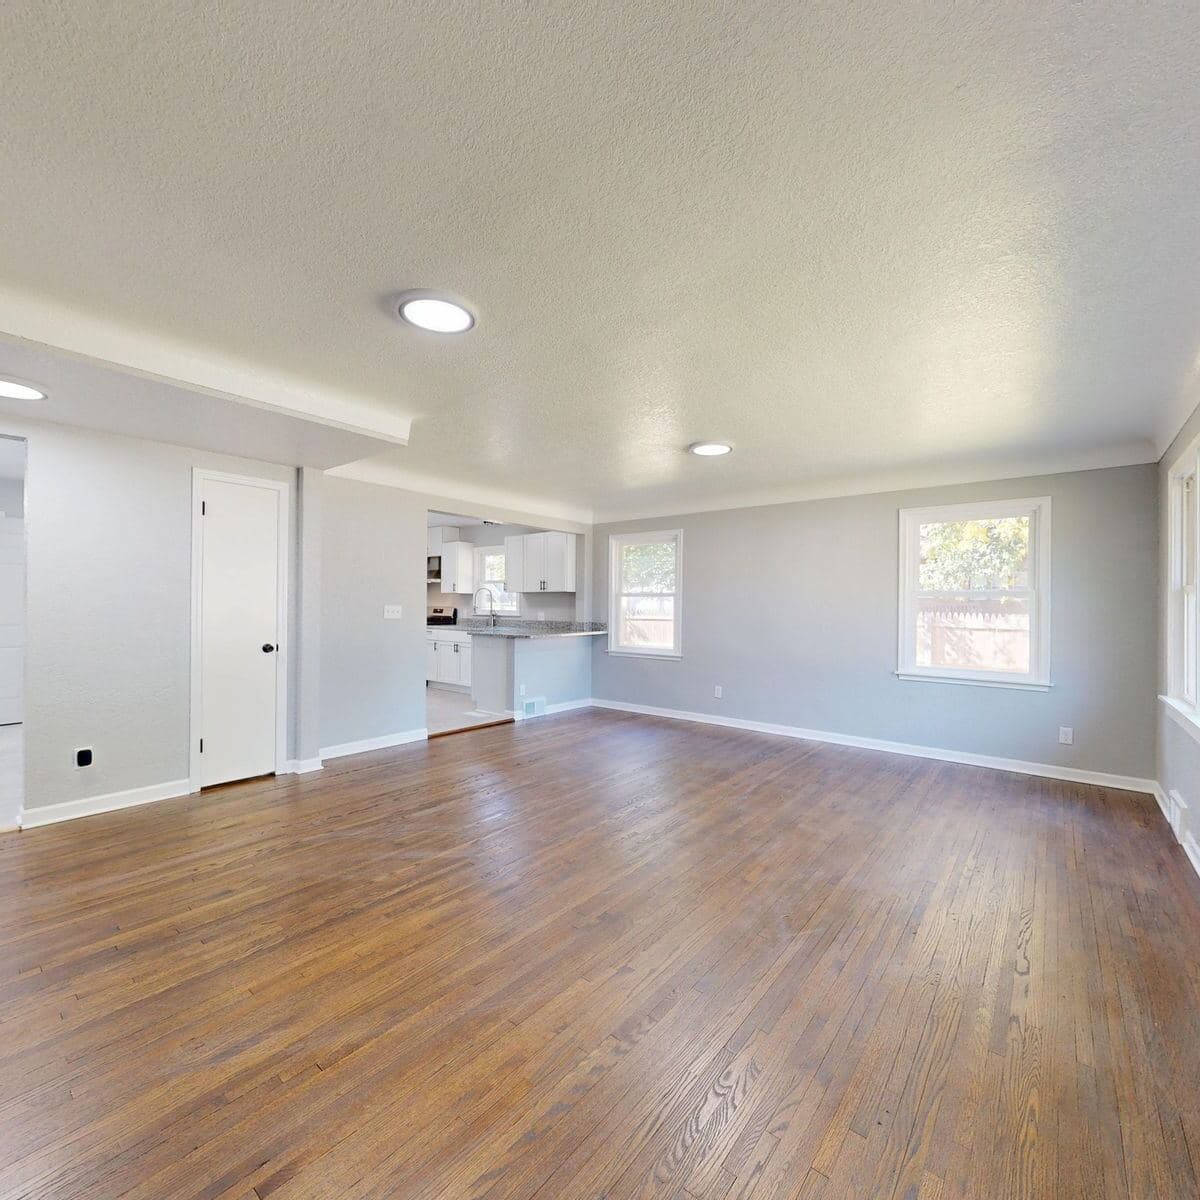
Yes, Pacific Specialty Insurance Company sells vacant home insurance in California. It writes it on its Basic Dwelling (DP1) policy for homes that "have remained unoccupied for more than 30 days," and it says the program is available in California, with plans to expand.[1] The DP1 covers nine named perils, including fire, windstorm and vandalism, on the dwelling, other structures and loss of use, and it pays actual cash value, not replacement cost.[2] You buy it through a Pacific Specialty agent. Menlo is not appointed with Pacific Specialty, so we can't quote it. We quote the California FAIR Plan, Delos, Green Shield and Aegis for vacant homes instead.
This guide is for a California owner with an empty house: listed for sale, just bought, inherited or under renovation. It covers what the Pacific Specialty policy covers and leaves out, who it fits, and how to get a quote. For how vacancy clauses work and how to name an estate or trust, read our guide to insuring a vacant or inherited home. To compare programs Menlo can quote, start on our vacant property insurance page.
Basic Dwelling (DP1) policy
The most basic dwelling fire form. It insures the house against a list of named perils and settles at actual cash value. Pacific Specialty's DP1 covers the main dwelling, other structures and loss of use.[2]
Does Pacific Specialty insure vacant homes in California?
Yes. Pacific Specialty says "vacant home insurance is available in the state of California" and that it plans to expand the coverage nationwide.[1] The company is based in Anaheim and describes more than 40 years in business.[3] It is also on the Department of Insurance's list of insurers that sell a DIC policy to pair with the California FAIR Plan.[4]
Who is the Pacific Specialty vacant policy for?
Owners of houses that have been empty more than 30 days. Pacific Specialty names the situations it has in mind: vacant homes for sale, new purchases not yet occupied, inherited properties held for sale, homes under renovation and properties in foreclosure.[1] It describes the DP1 as fitting homes that are "temporarily vacant and without personal assets," such as during repairs, a pending sale or between tenants.[2]
What does the Pacific Specialty DP1 cover?
Nine named perils on the house. Pacific Specialty lists them as fire or lightning, windstorm or hail, explosion, riot or civil commotion, aircraft, vehicles, smoke, vandalism or malicious mischief, and volcanic eruption.[2] The coverage applies to the main dwelling, other structures such as sheds, workshops and detached garages, and loss of use.[1][2]
| Coverage | In the Pacific Specialty DP1? | Why it matters on an empty house |
|---|---|---|
| Dwelling, nine named perils | Yes[2] | Fire, wind and the other listed causes of damage |
| Vandalism or malicious mischief | Yes, as a named peril[2] | Many vacant programs sell it only as an add-on |
| Other structures | Yes[1] | Detached garage, shed, workshop |
| Loss of use | Yes[2] | Lost rent or extra costs while repairs are made |
| Theft | Not a listed peril[2] | Stolen fixtures or materials aren't covered unless added |
| Water from plumbing or freezing | Not a listed peril[2] | A slow leak in an empty house can run for weeks |
| Liability | Not stated on the vacant page[1] | Ask the agent. Pacific Specialty notes owners can still be liable for injuries on a vacant property[5] |
| Settlement | Actual cash value[2] | Depreciation is subtracted from repairs |
Vandalism being a named peril is the notable difference. On Delos's vacant program, for example, vandalism is an endorsement you pay for, and the FAIR Plan needs a vacancy permit endorsement to cover it.[6][7]
What does it leave out?
Anything that isn't on the named-peril list. Theft and water damage from plumbing or freezing aren't among the nine perils, and actual cash value settlement means depreciation comes off a partial loss.[2] Pacific Specialty's public vacant pages don't state terms, limits, deductibles, liability options or prices, so get those from the agent in writing.[1]
Pacific Specialty also expects the owner to look after the house: regular inspections, lawn care and keeping the structure secured against unauthorized entry and deterioration.[5]
How do I get a Pacific Specialty vacant home quote?
Through a Pacific Specialty agent. Its vacant home page tells buyers to contact an agent or use its "Find a producer" search.[1] Have ready the date the house became empty and why, the plan (sale, rental, move-in or renovation), the owner's exact name as on the deed, the home's age, construction and roof, and any claims in recent years.
Menlo isn't appointed with Pacific Specialty, so we can't submit to it. If you want a second opinion from programs we can quote, the California FAIR Plan takes homes vacant up to a year, Delos writes vacant homes on a DP-3 form from a $1,500 minimum, and Green Shield takes residential vacancies up to 48 months.[8][6][9] Our comparison of the best vacant home insurance in California sets them side by side.
Frequently asked questions
Does Pacific Specialty sell vacant home insurance in California?
Yes, on its Basic Dwelling (DP1) policy, for homes unoccupied for more than 30 days.[1]
Does Pacific Specialty's vacant home policy cover vandalism?
Yes. Vandalism or malicious mischief is one of the nine named perils on its DP1.[2]
Does it cover theft or water damage?
Theft and water damage from plumbing or freezing are not among the nine named perils Pacific Specialty lists for the DP1.[2] Ask the agent whether anything can be added.
Is it replacement cost or actual cash value?
Actual cash value, according to Pacific Specialty's DP1 description.[2]
Can Menlo quote Pacific Specialty?
No. Menlo isn't appointed with Pacific Specialty. We quote vacant homes with the California FAIR Plan, Delos, Green Shield and Aegis.
This guide is for educational purposes and summarizes Pacific Specialty's public pages as of September 27, 2026 and other carrier documents. Programs, forms and availability change, and your policy's terms control. Menlo Insurance Services (CA license 6020106) is a licensed broker that is not appointed with Pacific Specialty, may earn a commission on placements with other insurers, and does not guarantee that any coverage or price will be available.
The Bottom Line
Pacific Specialty writes vacant California homes on its DP1 policy once a house has been empty more than 30 days.[1] It covers nine named perils, including vandalism, on the dwelling, other structures and loss of use, at actual cash value, and it leaves out theft and water damage.[2] You buy it from a Pacific Specialty agent. Menlo can't quote it, but we can quote the FAIR Plan, Delos, Green Shield and Aegis if you want to compare.
References
- 1.Pacific Specialty Insurance Company. “Vacant Home Insurance.” Accessed 2026-09-27. https://www.pacificspecialty.com/vacant-home-insurance/ ↩
- 2.Pacific Specialty Insurance Company. “DP1 Insurance Explained.” Accessed 2026-09-27. https://www.pacificspecialty.com/resource-center/faq/dp1-insurance-explained/ ↩
- 3.Pacific Specialty Insurance Company. “Pacific Specialty (home page).” Accessed 2026-09-27. https://www.pacificspecialty.com/ ↩
- 4.California Department of Insurance. “List of Insurers that Sell Difference in Conditions (DIC) Policies.” Accessed 2026-09-27. https://www.insurance.ca.gov/01-consumers/105-type/5-residential/carriersDICpolicies.cfm ↩
- 5.Pacific Specialty Insurance Company. “Vacant Property: Understanding Risks.” Accessed 2026-09-27. https://www.pacificspecialty.com/resource-center/insurance-term/vacant-property/ ↩
- 6.Delos Insurance Solutions. “Delos Vacant Home Product & Underwriting Overview, v1.1.” 2024. https://6041899.fs1.hubspotusercontent-na1.net/hubfs/6041899/Carrier%20Store%20Resources/Delos/65dce0b9e868b1e8437726e6_Vacant-Home-Product-and-Underwriting-Overview.pdf ↩
- 7.California FAIR Plan Association. “Dwelling Application Checklist and Application for Dwelling Insurance (ACORD 854 CA).” 2020. https://www.cfpnet.com/wp-content/uploads/2020/02/Dwelling%20Application%20REV%2001%2020.pdf ↩
- 8.California FAIR Plan Association. “Plan of Operation, Ed. 9/3/25, section IV.A.” 2025. https://www.cfpnet.com/wp-content/uploads/2025/10/CFPA-Plan-of-Operation-Ed.-9.3.25.pdf ↩
- 9.Green Shield Risk Solutions. “Vacant Property, Specialty Lines.” 2026. https://6041899.fs1.hubspotusercontent-na1.net/hubfs/6041899/Green%20Shield%20Risk/Vacant%20Property%20-%20Specialy%20Lines.pdf ↩