Homeowners insurance
For homes that fit a standard policy.
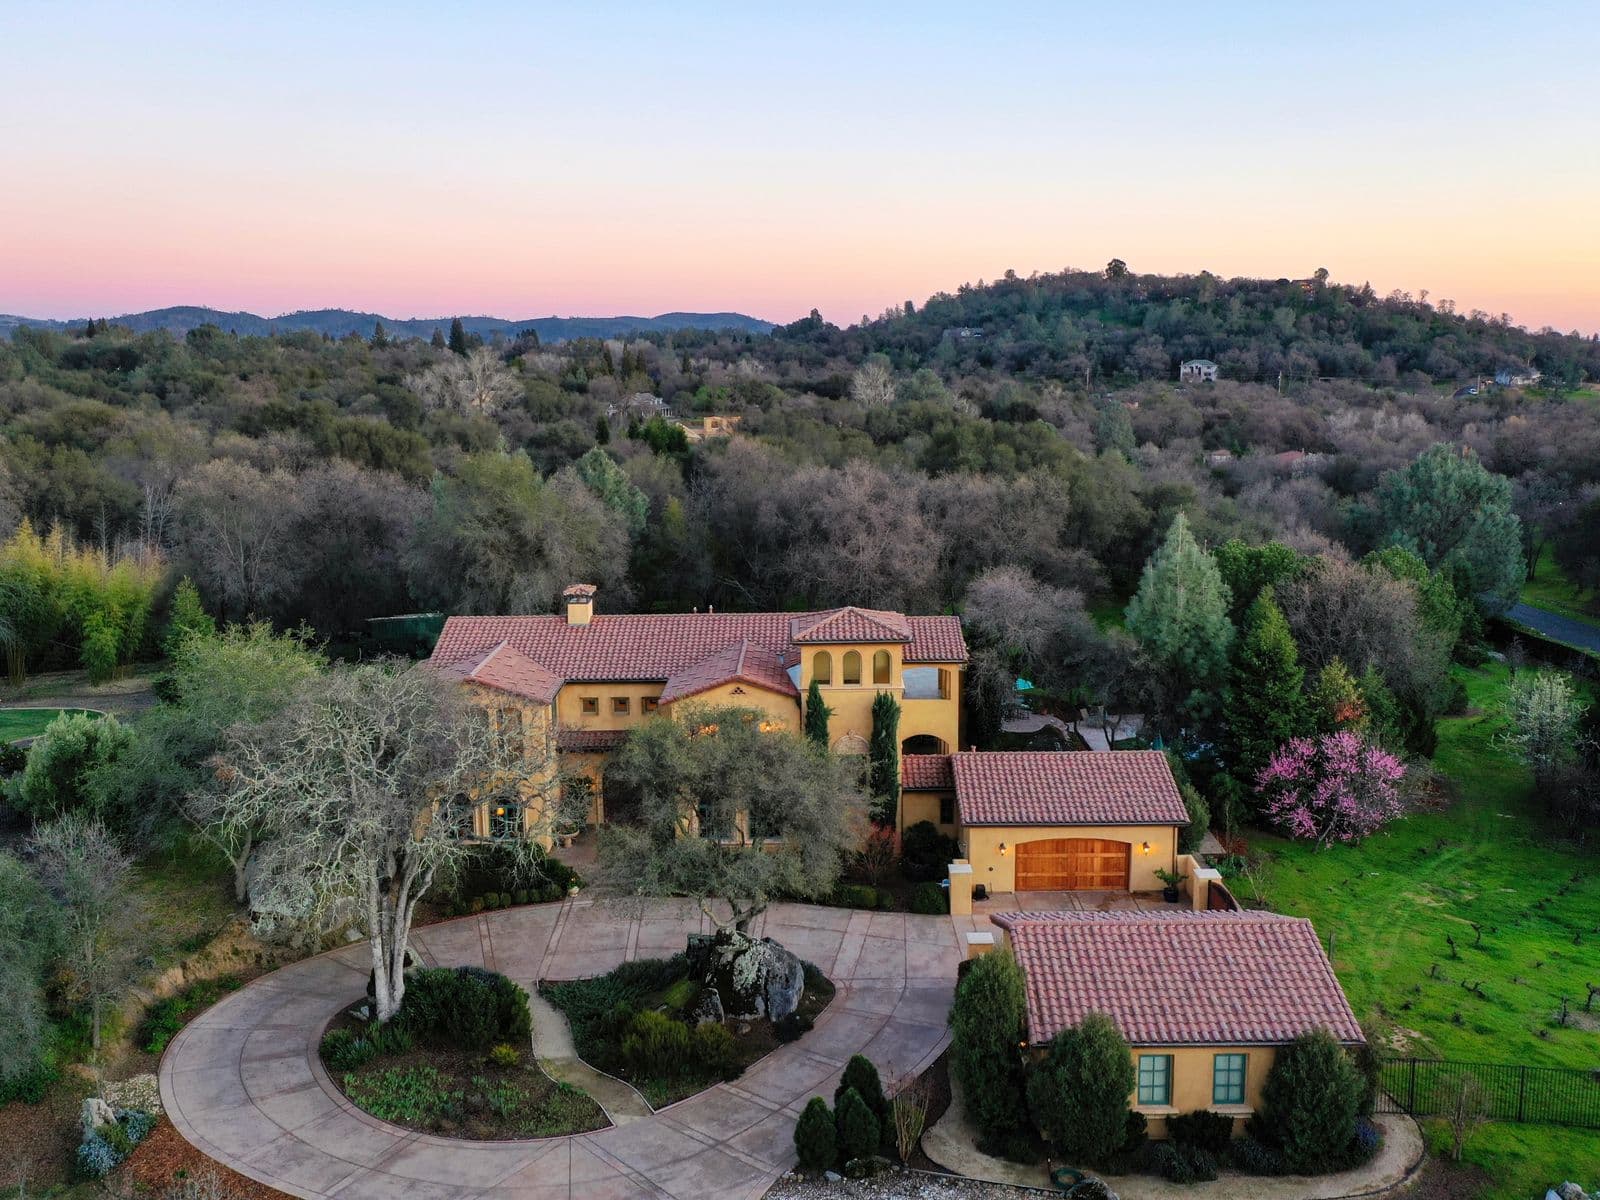
If rebuilding your home would cost more than about $1 million, a standard homeowners policy often runs out of room. We place homes like yours with specialty markets that write dwelling limits up to $7 million for owners who live in the house, full time or part of the year.

A few questions about your business or home.
We compare carriers and read the forms line by line.
We pick the best policy and get you covered.
These policies are for a home you live in, whether it is your main home or a place you spend part of the year. They are not written for rentals, vacant homes or houses in the middle of a remodel.
Dwelling limits run from about $1 million up to $7 million, and the whole policy can reach $10 million depending on the market.
Markets use their own wildfire models. Depending on where you live, one may ask for things like double paned windows, closed eaves and vent screens of 1/8 inch or less.
One market includes $100,000 of water damage and lets you buy up to $500,000 once an automatic water shutoff device is installed.
Personal liability usually runs from $100,000 up to $1 million, depending on the market.
The regular deductible is usually between $5,000 and $100,000, and larger homes need a higher minimum.
Expect a wildfire deductible of its own. With one market it starts at $25,000.
If you cancel early, at least 25% of the premium is kept, and policy and inspection fees are not refunded.
For homes that fit a standard policy.
Coverage without fire, next to a separate fire policy.
More liability above your home and auto.
For a home you rent to others.
Usually not. Homes at this value are written by surplus lines markets rated A+. We explain what that means for your policy before you decide.
Usually yes. One market inspects every home it insures and looks again at least every third renewal. The inspection fee is not refundable.
Not on these policies. Airbnb, Vrbo and longer leases usually make the home ineligible. If you rent it out, ask us about a landlord policy instead.
It can change how roof damage is paid. With one market, a composition shingle roof between 11 and 20 years old is paid at actual cash value, and an older one is excluded.
Tell us about the coverage you need and complete the application. We use those details to approach suitable markets and may ask follow-up questions. Requesting a quote does not put coverage in force.
A licensed broker can review eligibility and policy terms with you.