Insurance for Homeowners Associations
Insure your association's common areas and shared facilities. We request quotes for the association, not the individual homes.
Our commitment
Committed to doing insurance right, and doing it fast. Our vision: every property and project properly covered in minutes, with every rule followed.
Eight brokers, one team
Our eight brokers work together as one Menlo team, so you can reach a person who understands your account.
Independent brokerage
We hold appointments with multiple carriers, so the quote is shopped rather than served from one shelf.
Separate association responsibilities from residents' needs
A master association governs a planned community across multiple neighborhoods. A single family residential association or PUD request concerns its common areas and exposures, not the detached homes themselves.
Shared facilities
Describe the common areas, buildings and facilities the association operates, including the number of planned and completed units.
People working on site
Security, inspections and the use of independent contractors are part of the review. Have contractor insurance requirements available.
Residents' own protection
An association request does not replace a resident's personal policy. Review each household's belongings and liability separately.
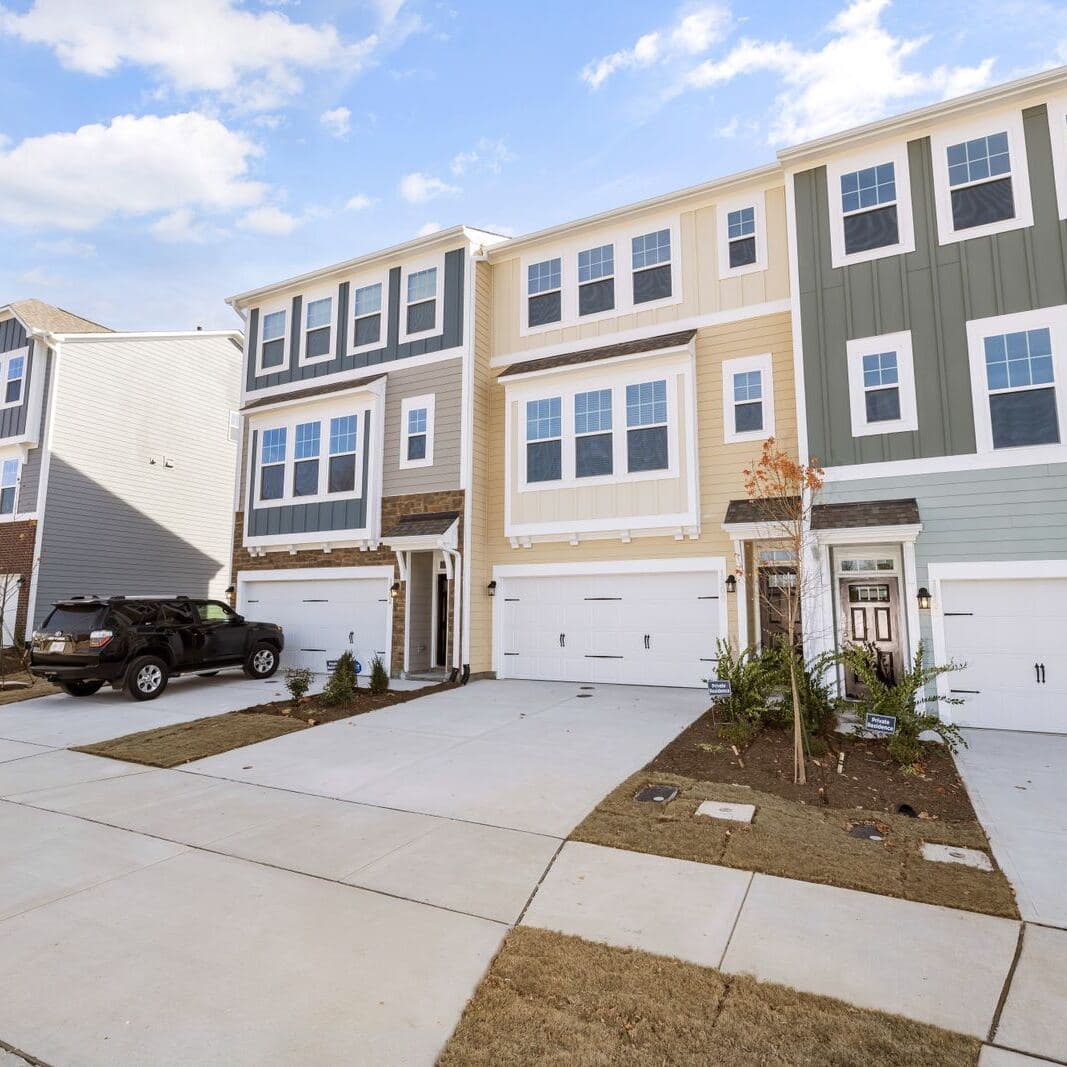
Start with the community your association serves
Describe the association's responsibilities and shared areas. The community type is a starting point for review, not a promise of coverage.
- Master associations
- Single family associations and PUDs
Details that shape the insurance review
- Community location
- Shared facilities and buildings
- Planned and completed units
- Security and inspections
- Prior insurance and losses
Questions we get asked
Does this insure each resident’s belongings?
No. This request concerns the association. Residents should review their own personal insurance separately.
Is coverage available in every state?
No. Product and state availability vary. The application and market review determine the options for your association.
Review your coverage options.
A licensed broker can review eligibility and policy terms with you.