From seed to sale
The programs write growers, processors, manufacturers, distributors, delivery services, labs and dispensaries. You only answer the questions for the work you do.
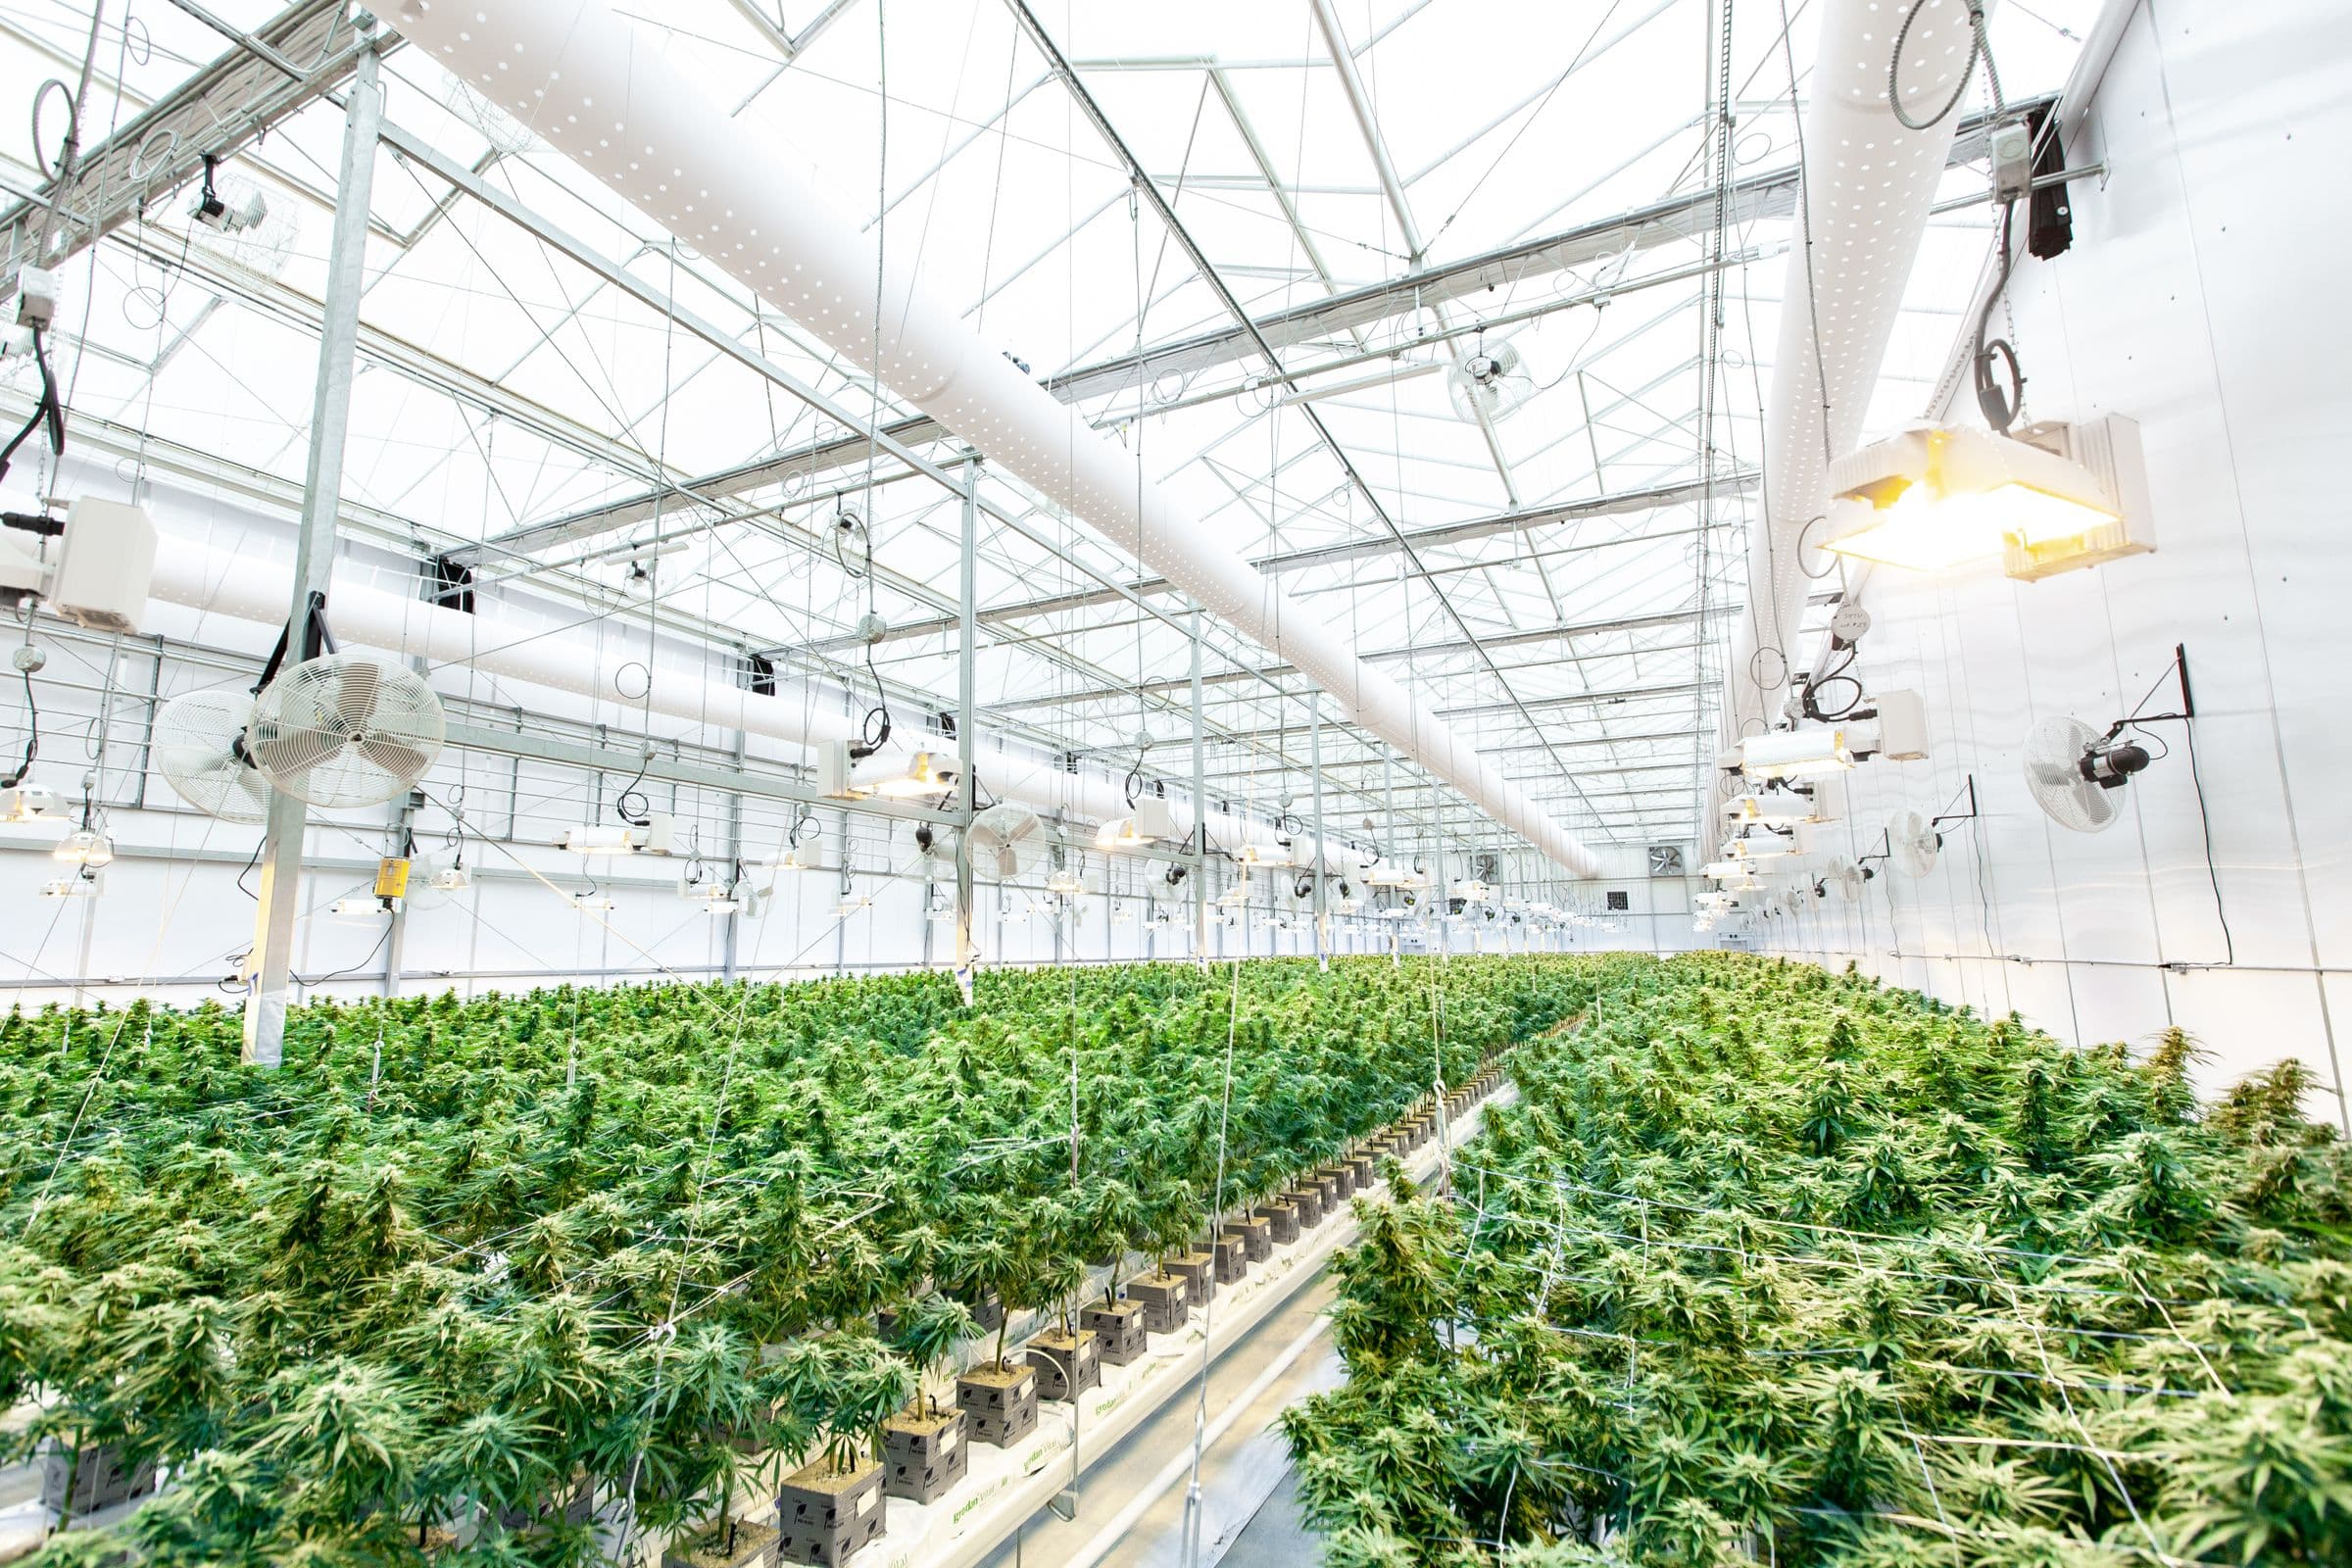
Get your dispensary, grow, lab or delivery business quoted with one application. We send it to several insurers.
Every annual license from the Department of Cannabis Control (DCC) except an event organizer's needs a surety bond of at least $5,000 per licensed premises on DCC Form 8113, and distributors must also carry general liability of $1 million per loss and $2 million aggregate. We place cannabis property, general and products liability with Blitz and CARMA, with property up to $10 million per location.
The programs write growers, processors, manufacturers, distributors, delivery services, labs and dispensaries. You only answer the questions for the work you do.
One package program we submit to can consider up to $10 million in total insured value at a single location. It takes a schedule if you have several.
You can ask about property, stock in transit, general and products liability, excess, workers comp, management liability, cyber and commercial auto.
Insurers look at your licenses, your security, how you handle product and your loss history, for the exact business and location being insured.
A few questions about your business or home.
We compare carriers and read the forms line by line.
We pick the best policy and get you covered.
Insurers ask a dispensary very different questions than they ask an extraction lab. Tell us what goes on at each location and what you want covered. The broker then follows up only on what applies to you.
If you have more than one building, you describe each one separately: how it's built, fire protection, security, recent work and values. Nothing gets mixed up on the schedule.
Pick the coverage you want, whether that's property, crop, equipment, delivery or liability. Skip anything that doesn't apply. The broker goes over the available terms with you.
If they apply to you, have details ready on your grow and lighting, delivery, extraction, product testing and past insurance.
Say yes and we request the $5,000 licensee bond with your application. A bond specialist reviews each request.
Each of these is a separate request. Not every insurer will take cannabis work on every line, so the broker checks each one.
Identify employees, their work and payroll for a separate workers compensation review.
Review the business's data, systems and cyber protection needs.
Describe business vehicles, drivers and delivery activities.
Some cannabis programs start at $500 per location plus taxes and fees for general liability alone. Products liability, property, the number of locations and your sales set the actual price.
No. Skip the sections that don't apply to you. The ones you keep only ask for what that coverage needs.
Yes. You add each location on its own, with its building, what happens there and its values.
Yes. A new cannabis or hemp business can describe what it plans to do. The insurer still reviews your licenses, your plans and the coverage you ask for.
Yes: the application asks if you need it. Say yes and we request the bond through our Goldleaf bond program along with your application. A bond specialist reviews each request, so approval isn't guaranteed.
We offer coverage in the states where we are licensed. Begin a quote with the address of your business or risk, and we'll let you know which markets can write that location before you spend much time on the questions.
Tell us about the coverage you need and complete the application. We use those details to approach suitable markets and may ask follow-up questions. Requesting a quote does not put coverage in force.
A licensed broker can review eligibility and policy terms with you.