Skip to content
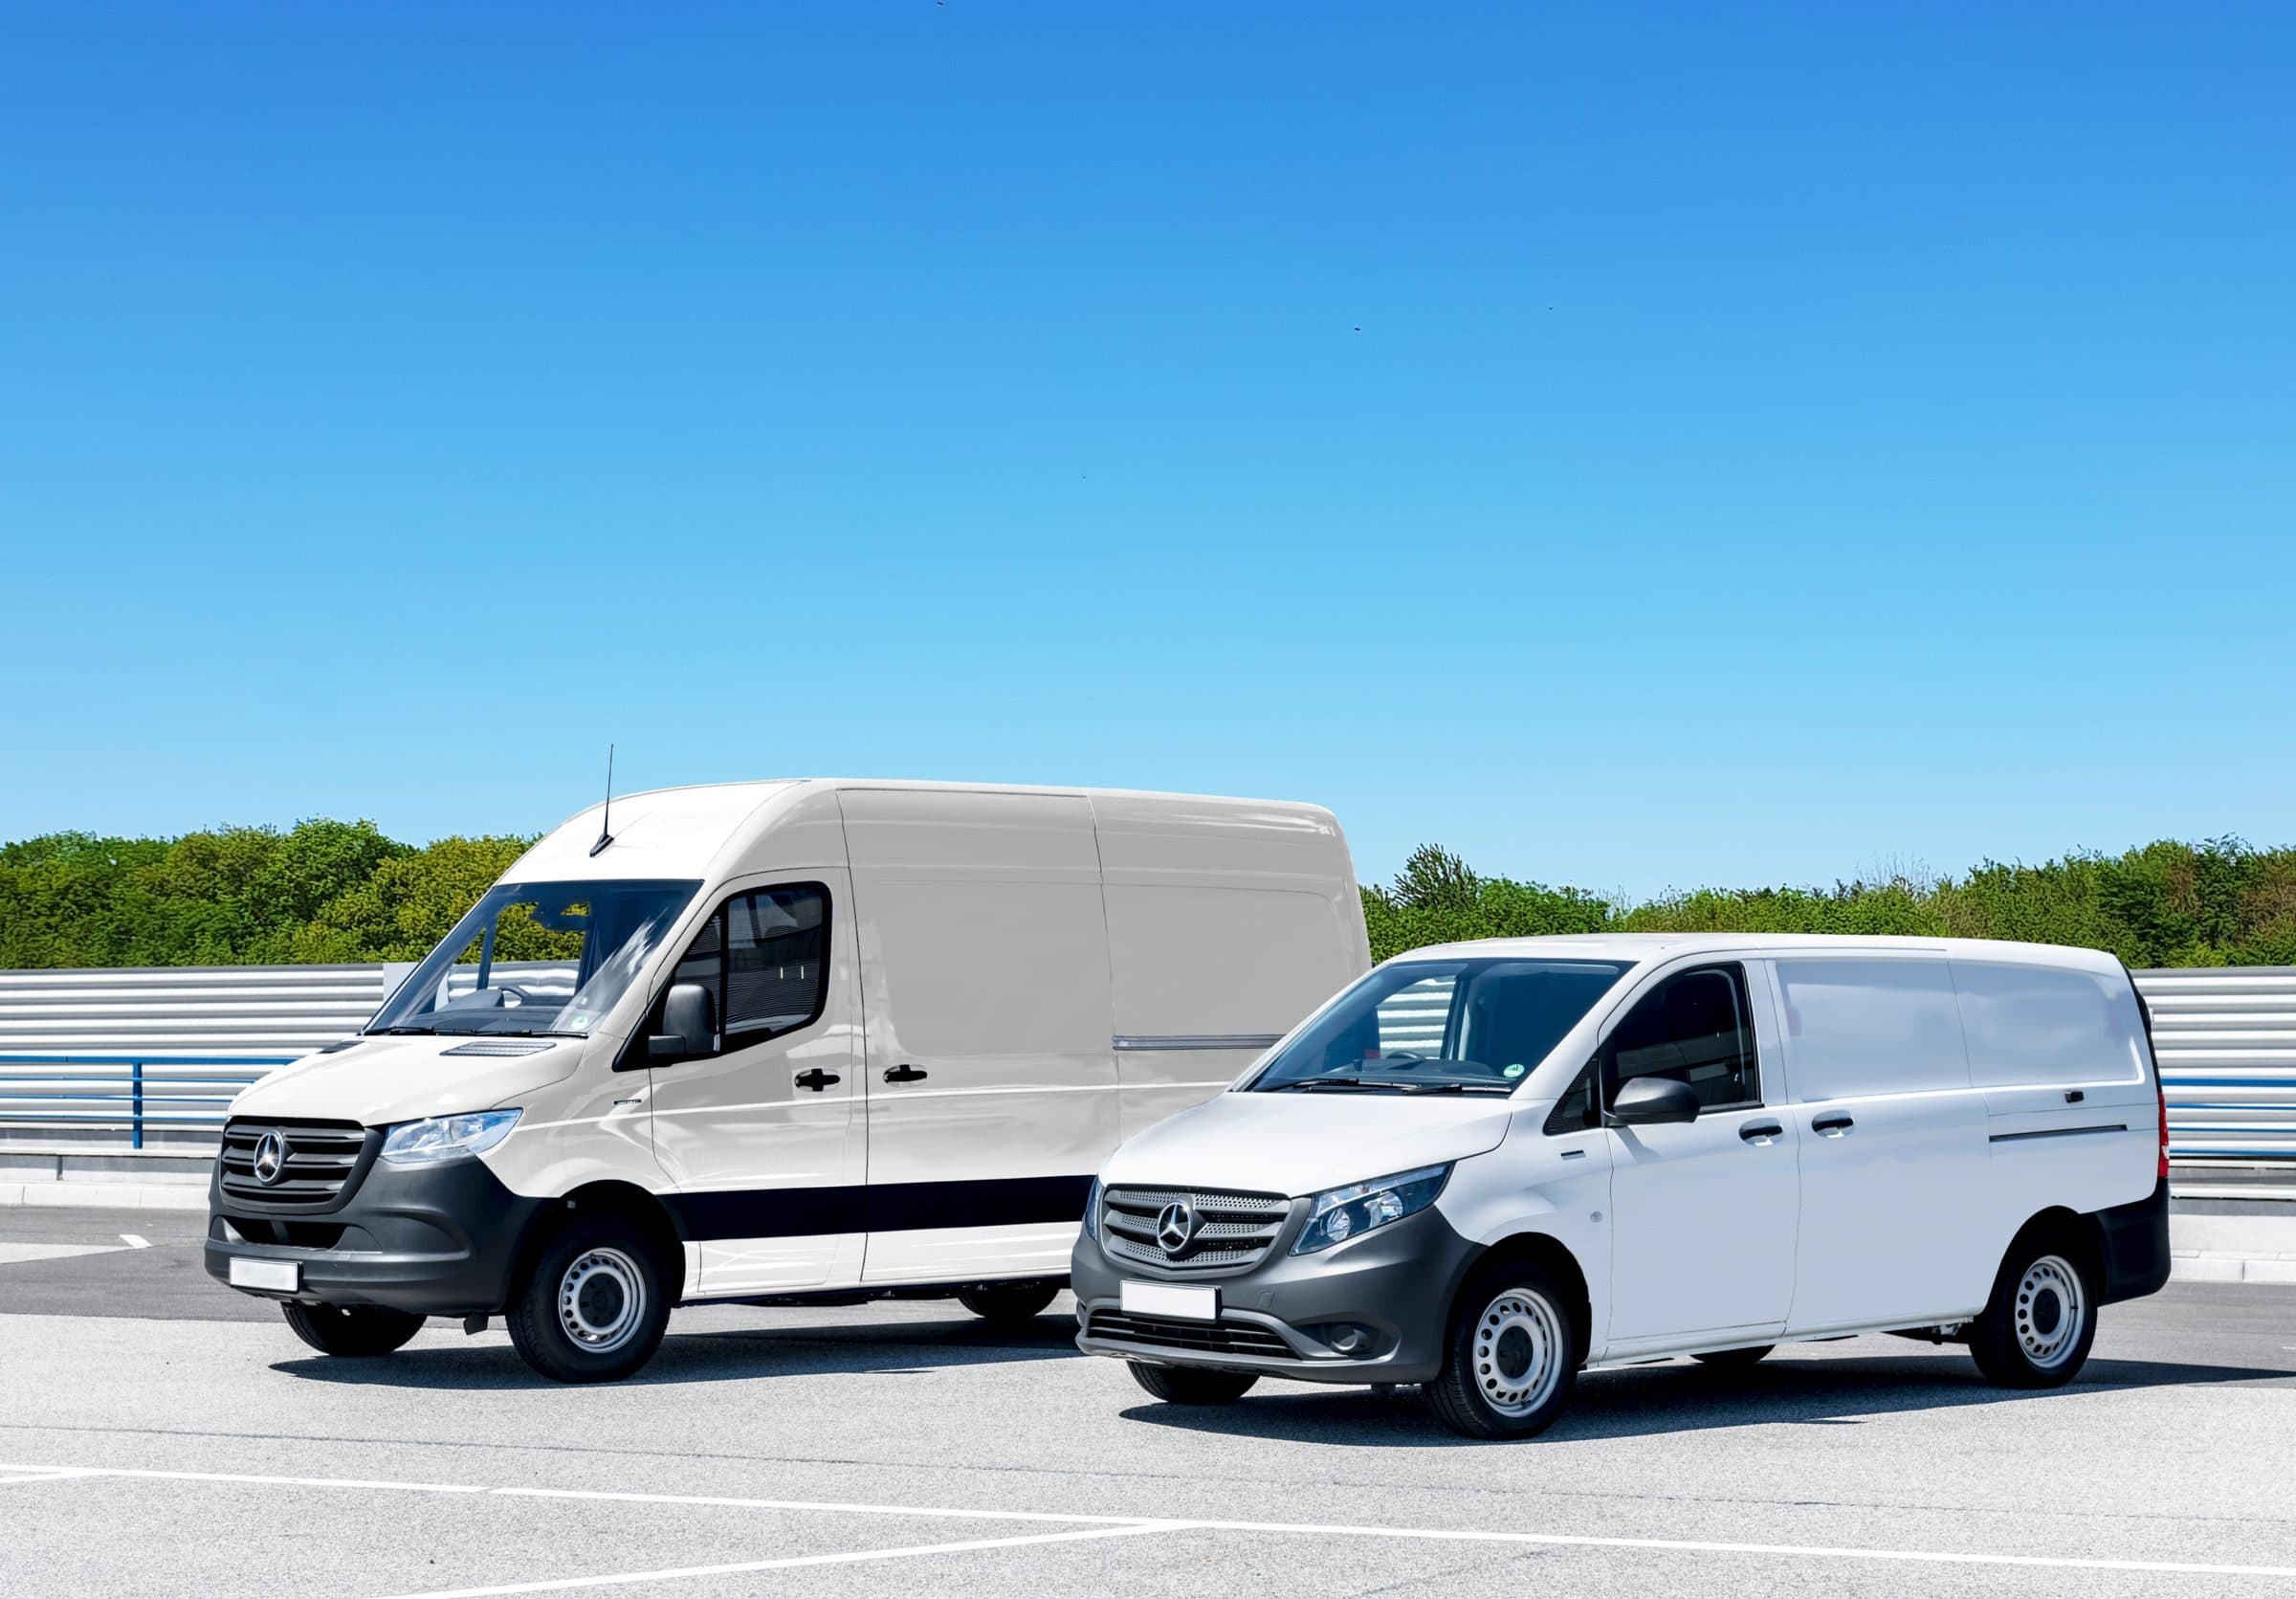
Two white work vans in a parking lot, business vehicles a commercial auto policy covers

Auto and Transportation Insurance

Insure your trucks, the cargo you haul and your filings. We shop carriers that fit your fleet and routes.

We shop the market for you, no broker fees

  • Progressive Commercial
  • Travelers
  • The Hartford
  • Great American
  • Chubb
  • ERGO NEXT
  • Kinsale
  • AmTrust

How it works

  1. One short form

    A few questions about your business or home.

  2. We shop the market

    We compare carriers and read the forms line by line.

  3. Quote and bind

    We pick the best policy and get you covered.

The risks behind each trip

  • Fleet liability

    A vehicle you own or operate causes injury or damage.

  • Cargo in transit

    Freight is damaged, stolen, or lost on the road.

  • Physical damage to units

    Your own tractors, trailers, and vans are off the road after a loss.

  • Driver injuries

    Long hours and loading work put drivers at risk.

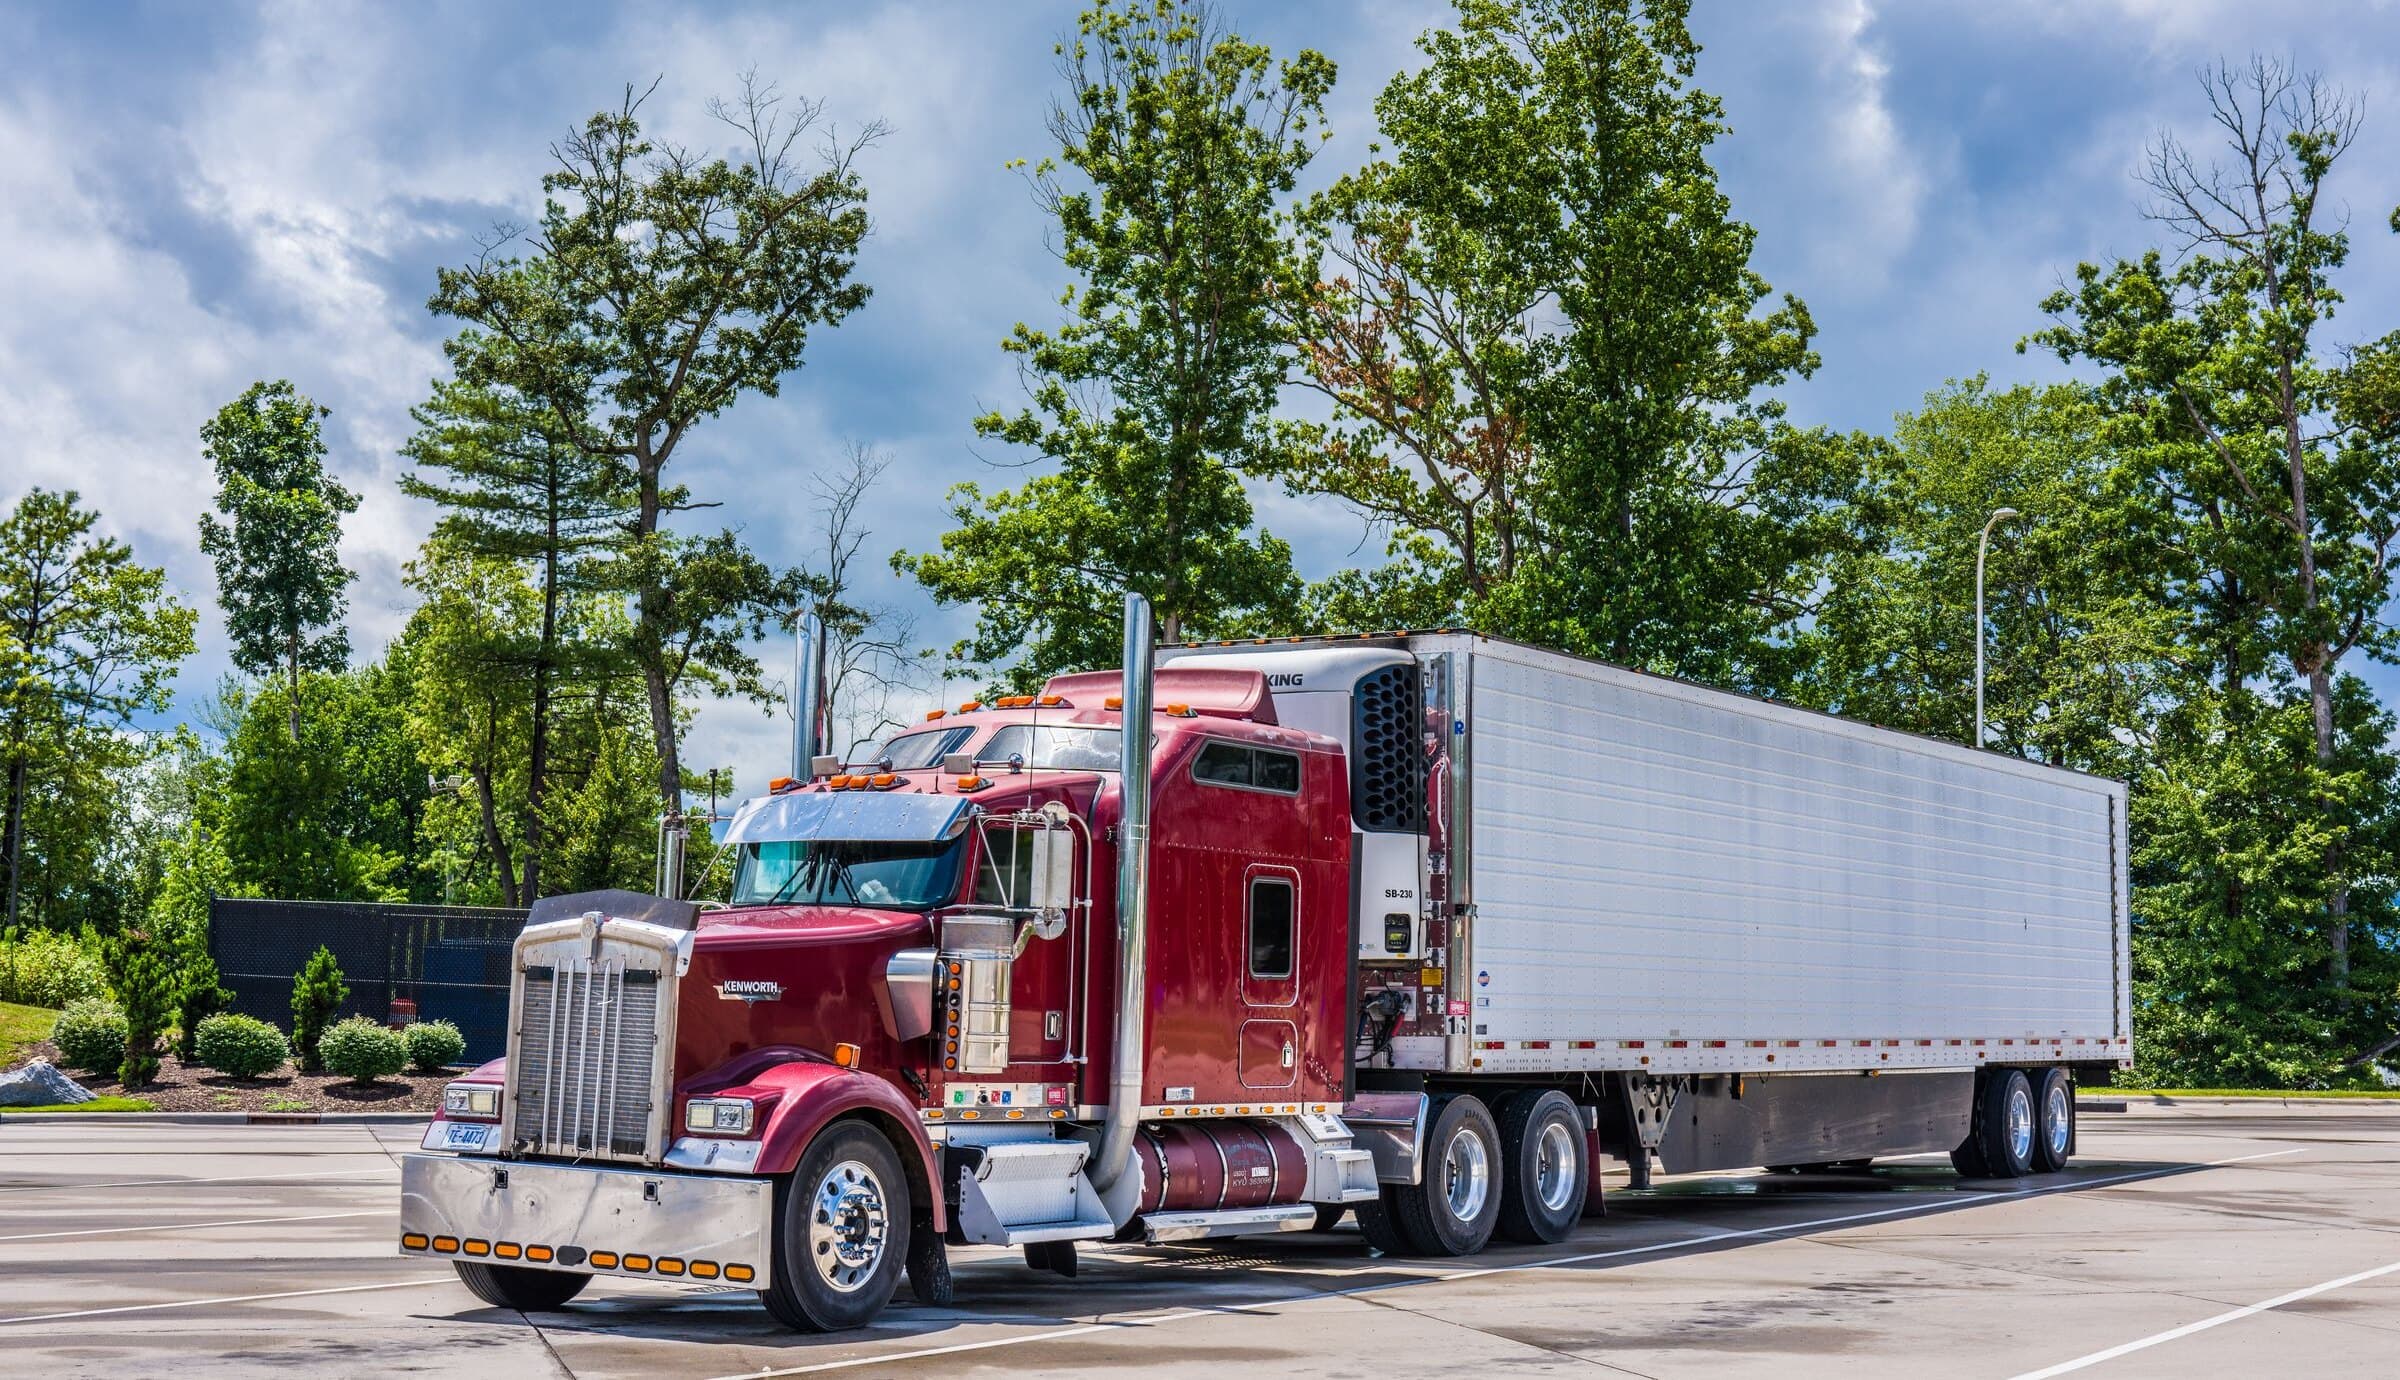
A semi truck with a refrigerated trailer

What changes your premium

These details help insurers assess your business and price the coverage. Terms and available options vary by insurer.

  • Vehicle types, values, and fleet size
  • Driver records, experience, and turnover
  • Operating radius and annual mileage
  • Cargo or passenger operations
  • Required filings and liability limits
  • Claims history and safety controls

What your vehicles carry matters

  • Local delivery and courier fleets
  • Long-haul trucking
  • Refrigerated freight
  • Flatbed and heavy haul
  • Dump trucks and aggregate hauling
  • Tow and roadside recovery
  • Last-mile contract delivery
  • Moving and household goods
  • Non-emergency medical transport
  • Shuttle and limousine
  • Charter and tour buses
  • Waste and recycling hauling
  • Auto transport and car carriers
  • Owner-operators running under their own authority

Coverage for vehicles, drivers and cargo

Commercial Auto

Every unit in the fleet needs liability and physical damage, plus the filing that proves it. Commercial auto answers an at fault accident involving one of your tractors, straight trucks, or vans, while collision and comprehensive repair or replace the unit itself. State and federal authority filings are made against this policy, so a lapse becomes an operating problem before it becomes an insurance problem.

General Liability

The road is only part of the exposure. General liability covers injury and property damage at the yard, the dock, and the office: a visitor hurt on your lot, a forklift into a customer's wall, damage you cause while loading. It is a separate policy from commercial auto, and claims that happen away from the vehicle land here.

Workers' Compensation

Drivers, dockworkers, and mechanics do physical work around heavy equipment, and comp is what pays their medical bills and wage replacement after an injury. Premium runs on payroll by class code, so how your staff is classified moves the number more than almost anything else on the policy. We settle the classifications when the policy is issued rather than at the year end audit.

Commercial Umbrella

Shippers and freight brokers increasingly write a combined limit into the contract that a primary auto policy cannot reach on its own. A commercial umbrella adds limit above auto and general liability and responds once the underlying policy is exhausted. Which policies sit underneath is a term of the umbrella form, so the two have to be built together rather than bought separately.

Excess and Surplus Lines

New authority, a thin loss history, or a fleet coming off a bad year will not get quoted in the standard market. Surplus lines carriers underwrite those files individually and can write terms an admitted form does not offer. We take the submission there with the loss runs, the driver list, and the safety picture an underwriter needs to price it.

Questions we get asked

Which policies do auto and transportation businesses usually need?

The right program depends on the operation, but the lines we most often evaluate are Commercial Auto, General Liability, Workers' Compensation, Commercial Umbrella, and Excess and Surplus Lines. We confirm which exposures are present before recommending a policy, so you do not pay for a line simply because it appears on a standard checklist.

What information do you need to quote auto and transportation insurance?

Have your vehicle and driver schedules, operating radius, commodities or passengers carried, required filings, annual mileage, and loss runs ready. A complete submission lets carriers evaluate the account on the actual operation and reduces follow-up questions before they can quote.

Can you help if a standard carrier already declined the account?

Often, yes. A decline does not guarantee another carrier will quote, but it tells us where the standard market stopped. We review the reason, improve the submission where the facts support it, and approach specialty markets when they are appropriate.

How do you compare the quotes you receive?

We compare the coverage form, limits, deductibles, exclusions, carrier financial strength, binding requirements, and total cost. The lowest premium is not the best option when the form removes the protection the business needs.

Start your quote online.

Fill in one short form or call us. No broker fees.