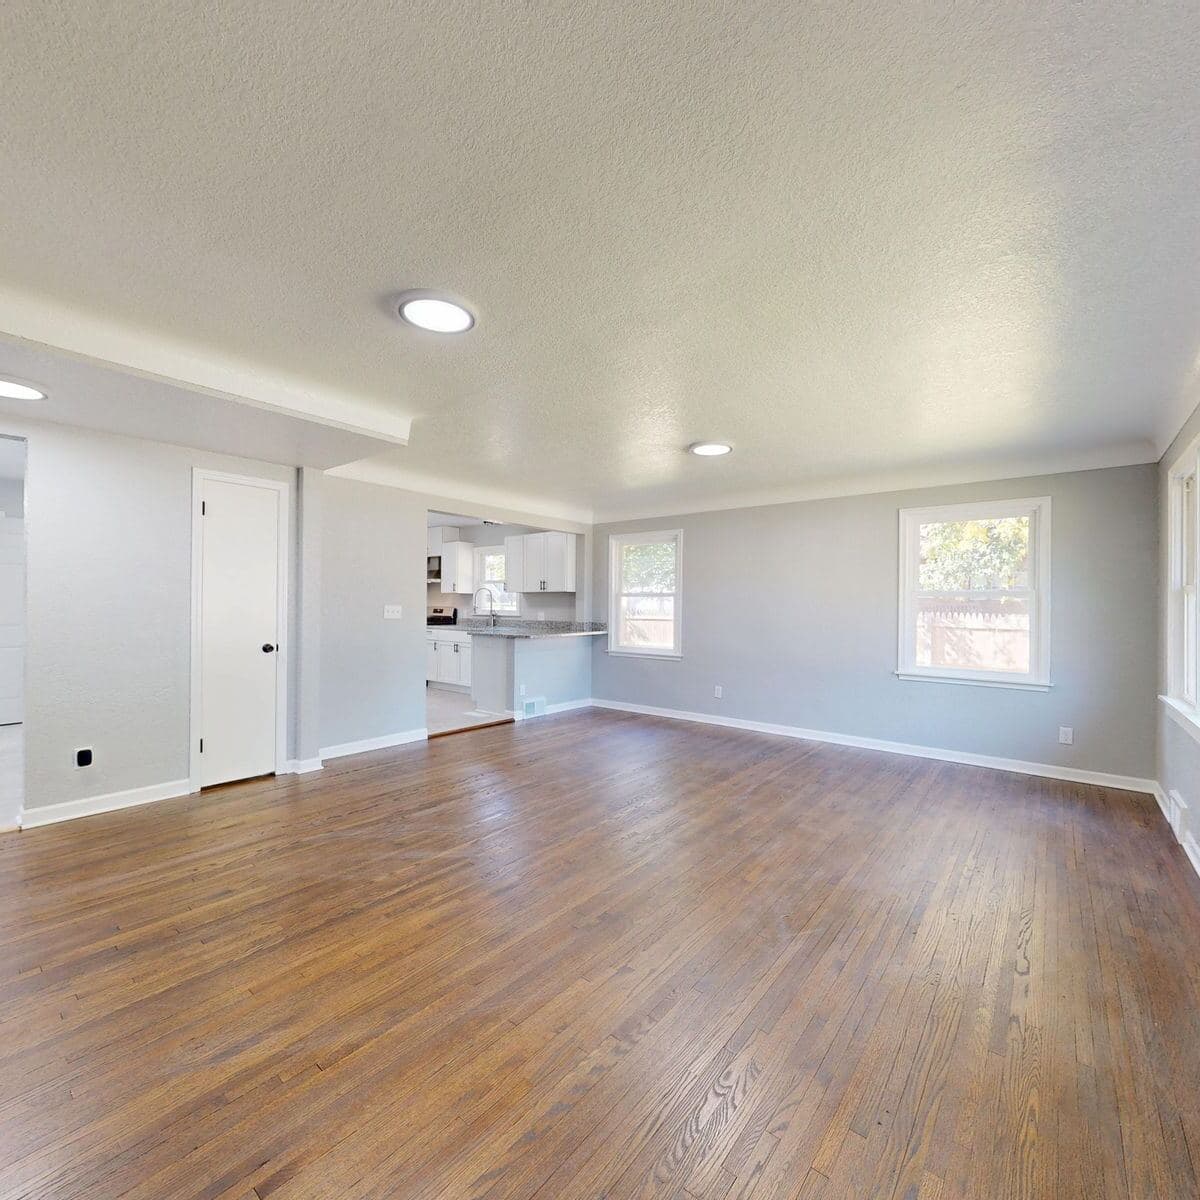
American Modern Insurance Group insures vacant homes through independent agents, on two dwelling programs. Dwelling Basic covers named perils on a house in fair condition or better. Dwelling Special is an open-peril form based on the DP-3 for homes in above-average condition.[1][2] Its vacant property coverage comes in 3-, 6- and 12-month terms with a pro-rated refund when the house sells, and vandalism, burglary, liability and builders risk are options you choose on the quote.[3]
For a California owner, one caveat comes first. American Modern's policies are issued by insurers licensed in California, and its materials name them.[2] The same materials also say a product "may not be available in your state." No public American Modern page confirms that its vacant program is open for a California address today.[1] Plan to confirm it on a live quote. If you need a policy in place before your current one's vacancy limit runs out, have a broker quote other vacant-home markets alongside it. Our vacant property insurance page explains how we do that.
American Modern vacant home insurance
Why does an empty house need a separate policy?
In California, the statutory standard fire policy says the insurer is not liable for a loss while a building "is vacant or unoccupied beyond a period of 60 consecutive days".[4] Many homeowners and landlord policies carry a vacancy condition of their own. Once the house has been empty past that limit, a fire, a break-in or a burst pipe may not be covered.
American Modern names the usual reasons an owner ends up here: the house is for sale, it's being renovated, or it's "part of an estate closing".[5] Each of those can last longer than anyone plans, which is why the term length matters.
What does American Modern's vacant policy cover?
The answer depends on which of the two programs your house lands in.
| Dwelling Basic | Dwelling Special | |
|---|---|---|
| Condition required | Fair or better[1] | Above average or better[2] |
| Dwelling coverage | Named perils, the causes of loss listed in the policy[3] | "All risk" for dwelling and other structures, subject to the policy's exclusions[2] |
| Loss settlement | Actual cash value, with an upgrade to repair cost in many states[3] | Replacement cost on the dwelling[2] |
| Home values | Not stated on the public page | $75,000 to $1 million, varies by state[2] |
| Water damage | Optional, $10,000 with a $5,000 mold sublimit[1] | Included at 10% of Coverage A with a $5,000 mold sublimit; can be raised[2] |
| Premises liability | Optional, $25,000 to $500,000[1] | Optional, $25,000 to $500,000[2] |
| Homes per policy | Up to 30[1] | Up to 30 in most states[2] |
Both programs include coverage for other structures at 10% of the dwelling limit, reasonable repairs, debris removal and a fire department service charge.[1][2] American Modern's vacant property page adds that emergency repairs, such as covering a roof after a storm, are included.[3]
Vandalism is the line to check first. American Modern says physical damage or defacement of the home "is included with the comprehensive program, but optional for basic program".[3] On a named-peril quote, a policy without the vandalism option leaves the most common vacant-home loss uncovered.
If the house qualifies for Dwelling Special, the settlement difference is real. Actual cash value takes depreciation off every repair. Replacement cost doesn't. Our guide to actual cash value vs replacement cost walks through the math.
Theft, burglary and copper pipes
American Modern explains a distinction most vacant-home buyers learn only after a claim. A theft endorsement "applies whether someone enters through a garage you leave open or forget to lock, or whether they kick in the side door." A burglary endorsement pays only when forced entry leaves visible damage, such as a broken window.[3]
Its limited burglary option covers stolen personal items and things attached to the house, and the company names "a heat pump or even copper piping" as examples.[3] If a would-be thief rips out drywall and leaves without the pipes, that is vandalism, a separate coverage.[3] On an empty house, ask which of the three your quote includes. A policy with none of them covers the fire and wind risk and little else.
Can you renovate while it's insured?
Yes, with the right option. American Modern lists builders risk as an add-on that covers "the value of improvements, alterations or repairs" during a renovation.[3] Without it, the new cabinets and roof you're paying for may sit outside the dwelling limit you insured. Tell the agent the scope and budget of the work before you bind, since a house under construction is a different risk from one that is simply empty.
Who issues the policy?
An American Modern insurer. The company says its policies "are written by one of the licensed insurers of American Modern Insurance Group, Inc.", including American Modern Home Insurance Company, which does business in California as American Modern Insurance Company (license 2222-8), and American Modern Property and Casualty Insurance Company (California license 6129-1).[2] American Modern is part of the Munich Re group.[6] American Modern Property and Casualty also appears on the California Department of Insurance's March 2025 list of insurers that answered the Commissioner's notice on contents claims from the Los Angeles wildfires, a sign that it writes residential property in the state.[7]
Your declarations page names the issuing company, and that company pays the claim. Look up its rating yourself; our AM Best ratings guide explains the scale.
How do you get a quote?
Through an independent agent appointed with American Modern. The company sells through agents, and its consumer pages send you to an agent search or its phone line.[3] Before the call, have:
The reason and the timeline
For sale, estate, renovation or between tenants, and how long you expect the house to stay empty. That picks the term: 3, 6 or 12 months.[3]
The house
The options you want
Premises liability, vandalism, theft or burglary, personal property left inside, and builders risk if work is planned.
The California question
Ask the agent to confirm, on a live quote for your address, that the vacant occupancy is available in California. Don't rely on the national product page.
Menlo Insurance Services is a licensed California broker. We don't claim an appointment with American Modern here. What we can do is shop your empty house across the vacant-home markets we work with, including admitted dwelling fire and surplus lines programs, and show you the terms side by side. Request a dwelling fire quote and mark the house as vacant.
Frequently asked questions
Does American Modern insure vacant homes?
Yes. American Modern writes vacant homes on its Dwelling Basic and Dwelling Special programs, through independent agents, for houses that are for sale, being renovated or part of an estate.
Does American Modern write vacant homes in California?
Its issuing companies are licensed in California, but American Modern says products and options may not be available in every state, and it doesn't publish California availability for the vacant program. Confirm it on a live quote for your address.
How long can an American Modern vacant policy run?
American Modern writes vacant property for 3, 6 or 12 months. If the house sells or someone moves in, you can cancel and get a pro-rated refund of the unused premium.
Is vandalism covered on an American Modern vacant policy?
It depends on the program. American Modern says vandalism is included with the comprehensive program and optional on the basic program. Check your quote for it.
What is the difference between theft and burglary coverage?
Theft coverage applies however the thief got in, including an unlocked door. Burglary coverage pays only when forced entry leaves visible damage, such as a broken window or a jimmied door.
This guide is for educational purposes and summarizes American Modern's public product materials and California Department of Insurance records. Your policy's terms, conditions and endorsements control. Menlo Insurance Services (CA license 6020106) is an independent broker, may earn a commission, and does not guarantee that any carrier will quote or bind a given home.
The Bottom Line
American Modern insures vacant homes on two programs chosen by the home's condition: Dwelling Basic on named perils, Dwelling Special on an open-peril, replacement cost form. The terms run 3, 6 or 12 months with a pro-rated refund, which suits a house that should sell soon. Vandalism, theft or burglary, liability and builders risk are the options that make the policy fit an empty house. The issuing companies are licensed in California, but confirm on a live quote that the vacant program is open for your address, and have a second market quoted in case it isn't.
References
- 1.American Modern Insurance Group. “Dwelling Basic.” https://agents.amig.com/content/munichre/amiggrp/agents/storefront/en/home/residential-solutions/dwelling-basic.html ↩
- 2.American Modern Insurance Group. “Dwelling Special product sell sheet (23002, © 2023).” https://agents.amig.com/content/dam/munichre/amiggrp/pdf/23002-DS_Sellsheet-012022_FA.pdf ↩
- 3.American Modern Insurance Group. “Vacant Property Details.” https://blog.amig.com/insurance/vacant-property/vacant-property-details/ ↩
- 4.California Legislative Information. “California Insurance Code § 2071 (standard form fire policy).” https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?lawCode=INS§ionNum=2071 ↩
- 5.American Modern Insurance Group. “Vacant Homes.” https://agents.amig.com/content/munichre/amiggrp/agents/storefront/en/home/residential-occupancy/vacant-homes.html ↩
- 6.Wikipedia. “American Modern Insurance Group.” https://en.wikipedia.org/wiki/American_Modern_Insurance_Group ↩
- 7.California Department of Insurance. “Insurance Company Responses to Commissioner Lara's 2/6/25 Notice on Personal Property Coverage (as of 3/5/25).” https://www.insurance.ca.gov/0400-news/0100-press-releases/2025/upload/Insurer-Responses-to-Contents-Inventory-Issue-as-of-030525.pdf ↩