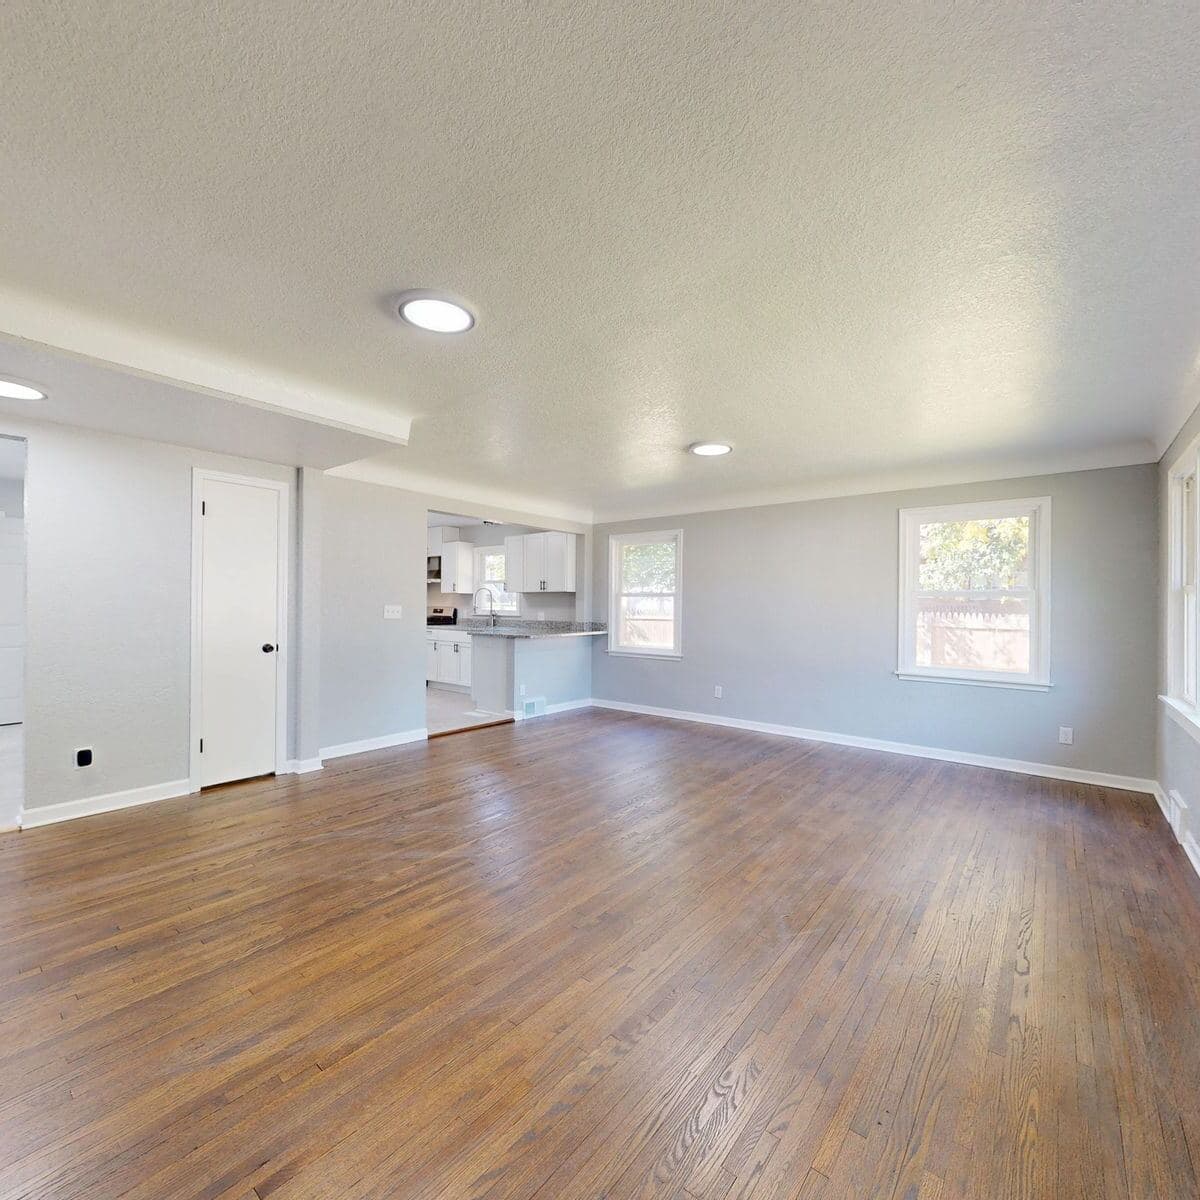
Yes, Foremost writes vacant homes in California again. Foremost is the specialty-home company of the Farmers Insurance Group, and its Dwelling Fire Vacant policy reopened to new California customers on March 15, 2025, after the company had stopped taking new vacant business in the state in August 2023.[1][2] The base policy insures the house against a short list of named perils. Vandalism, liability, personal property and broader coverage are optional, so the quote you get depends on what you add.[3]
If your house is empty because it's for sale, between tenants, going through probate or waiting on a renovation, this is the Farmers answer. You buy it through an agent, not online. Below: what the policy covers, what it leaves out unless you add it, and what the agent will ask you for. If you'd rather have a broker compare several vacant-home markets at once, see our vacant property insurance page.
Foremost Dwelling Fire Vacant
Why does an empty house need its own policy?
Because your homeowners policy stops working. California's standard fire policy, the statutory baseline for property insurance in the state, says the insurer is not liable for a loss while a building "is vacant or unoccupied beyond a period of 60 consecutive days".[9] Many homeowners and landlord forms are tighter than that. Foremost's own consumer guide puts the usual limit at "between 30 to 60 days" of vacancy.[4]
Past that point, the losses an empty house is most exposed to may not be covered at all: a break-in, vandalism, a pipe that leaks for weeks before anyone notices. A vacant dwelling policy is written on the assumption that nobody is there. That's why it costs more, and why the coverage starts narrow.
Is Foremost writing vacant homes in California right now?
Yes. On August 1, 2023, Foremost stopped accepting new business for several specialty property types in California, vacant homes among them, and called the pause temporary.[2] In December 2024, Farmers announced a phased return. The Farmers release says "Foremost Dwelling Fire Landlord and Dwelling Fire Vacant insurance will reopen for new customers effective March 15, 2025."[1] Farmers then removed its monthly cap on new California homeowners policies in November 2025.[10]
Two cautions. Reopening means Foremost accepts applications again. It does not mean every address qualifies. Wildfire exposure, condition and value still decide. And this program closed to new California business in 2023 and came back in 2025, so check availability when you need the policy, not from an old article.
What does a Foremost vacant home policy cover?
The base policy covers the dwelling. Foremost's consumer page describes it as named-peril coverage for "fire, explosion, lightning, windstorm and hail damage".[3] Its agent overview of the Dwelling Fire One form adds riot or civil commotion, aircraft, vehicles, and smoke or smudge.[8] Anything not on that list is not covered.
Everything else is a choice you make on the quote:
| Coverage | In the base policy? | What it does for an empty house |
|---|---|---|
| Dwelling, named perils | Yes | Pays for fire, wind, hail, lightning, explosion and the other listed perils[3][8] |
| Vandalism and malicious mischief | No, optional | Pays for deliberate damage by someone else. Foremost points out that some insurers won't offer it on an empty home[4] |
| Comprehensive dwelling coverage | No, optional where available | Broadens the dwelling to "most direct, abrupt and accidental physical losses" unless excluded; varies by state[3] |
| Other structures | No, optional | Detached garage, shed, fence[8] |
| Personal property | No, optional | Furniture or appliances left in the house, named perils[8] |
| Limited theft on personal property | Optional in many states | Theft of contents, with limits[5] |
| Liability | No, optional | Someone is hurt on the property and blames you[3] |
| Replacement cost | No, optional | Pays repair cost without depreciation[3] |
Loss settlement matters more than people expect. Foremost's base vacant policy pays an agreed amount on a covered total loss and actual cash value on a partial loss, which means depreciation comes off repairs. You can buy replacement cost as an option.[5] Our guide to actual cash value vs replacement cost shows how big that gap can get on an older roof.
Water is where to read the form closely. The named-peril list doesn't include a slow leak or a burst pipe, and an empty house is where those go unnoticed. Ask the agent whether the comprehensive endorsement is available for your address and what it says about water and freezing.
Who is the insurer, and who pays a claim?
A Foremost company, not a surplus lines market. Foremost Insurance Group is a trade name for several underwriting companies, including Foremost Insurance Company Grand Rapids, Michigan, Foremost Property and Casualty Insurance Company and Foremost Signature Insurance Company, all part of Farmers.[6] The California Department of Insurance lists Foremost Insurance Company Grand Rapids, Michigan as authorized in California since August 28, 1961, with a normal, unlimited license that includes fire.[7]
That makes the policy admitted business, which carries the California guaranty fund backing that surplus lines policies don't. If you're comparing a Foremost quote to one from a specialty market, our guide to admitted vs non-admitted carriers explains what changes. Your declarations page names the exact company. That company pays your claim.
Will your house qualify?
Foremost's published guidance describes a wide window. Its vacant dwelling quick facts say homes for sale, homes for rent and vacant manufactured homes are eligible, with "no restrictions based solely on the age of the home or the amount of time the home has been vacant", values from $5,000 to $1,000,000 in most states, and policies in the name of an LLC or a trust.[5] Condition is the real test. The agent overview says:[8]
- The agent must take and keep photos before the policy is issued.
- Foremost underwrites your loss history at every property you have owned, including this one.
- Homes with existing claim damage aren't accepted until repairs are finished.
- Missing roof shingles or missing siding make a home unacceptable.
- The house has to stay rated as vacant until someone actually moves in.
- Vacant homes valued over $500,000 need to be in above-average condition.
Those agent documents carry 2016 and 2017 edition dates, and the California program guide controls. Treat them as a sense of what Foremost looks at, not a checklist that guarantees approval.
How do you get a Foremost vacant home quote?
Through a licensed agent. Foremost sells through agents rather than online, and its site sends you to a local agent or its phone line.[3][4] Have this ready:
Why the house is empty and for how long
For sale, between tenants, estate, renovation. Say if work is planned, because Foremost asks agents to note renovations.[8]
The house itself
Year built, square footage, construction, roof age and condition, and the value you want to insure. Recent photos of every side help, and the agent will need them anyway.
Your history
Prior claims at any property you've owned, prior carriers, and any nonrenewals.
The coverages you want
Decide on vandalism, liability and theft before you compare prices. A quote without vandalism looks cheaper because it covers less.
Who owns it
An individual, a trust, an LLC or an estate. Foremost can write homes in the name of an LLC or a trust.[5]
Menlo Insurance Services is a licensed California broker. We don't claim an appointment with Foremost here, but we do shop vacant homes with the markets we work with, including admitted dwelling fire and surplus lines programs for houses the standard market turns down. To compare, request a dwelling fire quote and tell us the house is vacant.
Frequently asked questions
Does Farmers insure vacant homes in California?
Yes, through Foremost, its specialty-home company. Farmers reopened Foremost Dwelling Fire Vacant to new California customers effective March 15, 2025. Eligibility still depends on the address, the home's condition and wildfire exposure.
Does Foremost vacant home insurance cover vandalism?
Only if you add it. The base policy covers named perils such as fire, lightning, windstorm, hail and explosion. Vandalism and malicious mischief is an optional coverage, and Foremost notes that many insurers don't offer it on empty homes at all.
Can I get a 3-month or 6-month Foremost vacant policy?
Foremost's agent materials describe an annual policy with a pro-rated refund if you cancel early, subject to a minimum earned premium. If the house sells in two months, you cancel and get the unearned part back.
What happens when a tenant moves in?
In most states Foremost lets the agent endorse the policy from vacant to rental use without canceling and rewriting it. Tell your agent before the move-in date so the policy matches how the house is used.
Is a Foremost vacant policy admitted in California?
Foremost policies are issued by Foremost companies, and Foremost Insurance Company Grand Rapids, Michigan is authorized by the California Department of Insurance. Your declarations page names the exact issuing company.
This guide is for educational purposes and summarizes Foremost and Farmers public materials, some of them agent documents with older edition dates. Your policy's terms, conditions and endorsements control. Menlo Insurance Services (CA license 6020106) is an independent broker, may earn a commission, and does not guarantee that any carrier will quote or bind a given home.
The Bottom Line
Foremost writes vacant homes in California again, since March 15, 2025. The base policy is a named-peril dwelling fire policy with agreed-value settlement on a total loss and actual cash value on partial losses. For an empty house, the options do most of the work: vandalism, liability, theft and, where available, comprehensive coverage. The insurer is an admitted Foremost company. Get the quote through an agent, pick your add-ons before you compare prices, and bind before your current policy's vacancy limit runs out.
References
- 1.Farmers Insurance Newsroom. “Recognizing an Improved Insurance Marketplace in California, Farmers Insurance to Expand Its Coverage Options in the State (Dec. 11, 2024).” https://newsroom.farmers.com/2024-12-11-Recognizing-an-Improved-Insurance-Marketplace-in-California,-Farmers-Insurance-R-to-Expand-Its-Coverage-Options-in-the-State ↩
- 2.ABC10. “Another insurance company has changed how it's doing business in California (2023).” https://www.abc10.com/article/entertainment/television/programs/to-the-point/farmers-insurance-limiting-new-homeowners-policies-california/103-8ef55b37-02f1-454a-ad97-f6650e5c5095 ↩
- 3.Foremost Insurance Group. “Vacant Home Insurance.” https://www.foremost.com/insurance/vacant-home/ ↩
- 4.Foremost Insurance Group. “Vacant Home Insurance Explained.” https://www.foremost.com/learning-center/vacant-home-insurance.asp ↩
- 5.Foremost Insurance Group. “Foremost Quick Facts: Vacant Dwelling (form 9014418, 11/16).” https://www.foremostagent.com/assets/products/Vacant.pdf ↩
- 6.Foremost Insurance Group. “About Foremost.” https://www.foremost.com/about-foremost/ ↩
- 7.California Department of Insurance. “Company Profile: Foremost Insurance Company Grand Rapids, Michigan.” https://interactive.web.insurance.ca.gov/companyprofile/companyprofile?event=companyProfile&doFunction=getCompanyProfile&eid=3577 ↩
- 8.Foremost Insurance Group. “Dwelling Fire and Specialty Homeowners Overview (form 9014436, 05/17).” https://cp.foremost.com/nss/products/pdf/Dwelling-Fire-and-Specialty-Homeowners-Overview.pdf ↩
- 9.California Legislative Information. “California Insurance Code § 2071 (standard form fire policy).” https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?lawCode=INS§ionNum=2071 ↩
- 10.Farmers Insurance Newsroom. “Farmers Insurance to Remove Cap on Writing New Homeowners Insurance Policies in California (Nov. 21, 2025).” https://newsroom.farmers.com/2025-11-21-In-Major-Move-to-Expand-Growth,-Farmers-Insurance-R-to-Remove-Cap-on-Writing-New-Homeowners-Insurance-Policies-in-California-and-Submits-New-Rating-Plan ↩