Vacant home insurance
The vacant property request continues with the home application for a house, condo or 2–4 unit building.
Don't leave your empty commercial building uninsured. Get its property and liability quoted while it sits fully vacant.
A fully vacant store, office, warehouse or building of five or more apartments can be insured for property and liability while it sits empty. The programs we use look at how long it has been empty, its prior use, security, utilities and planned work. One allows up to 24 months of vacancy, and terms of 3, 6, 9 or 12 months can be requested.
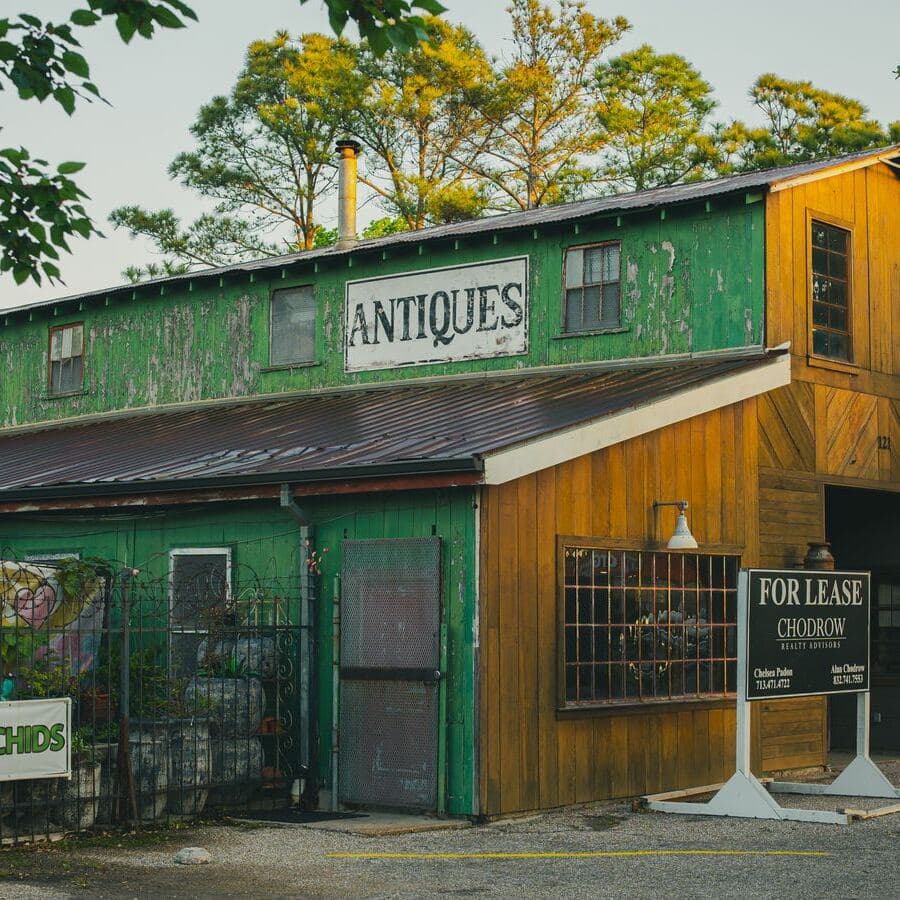
Insurers price a vacant commercial building on much more than its value. Vacancy duration, prior use, security, utilities and planned work help describe the property. The coverage requested and the property's circumstances still require underwriting review.
Describe construction, building and roof age, floor area, inspections, utilities and how the property is secured.
Identify building values, any business personal property or other structures, deductibles and whether premises liability is needed. Optional coverages are requests for review, not automatic inclusions.
Explain planned renovation or construction, contractor involvement, prior insurance and losses. List any mortgagees, loss payees or additional insureds that need to be considered.
You can request 3, 6, 9 or 12 months. The term offered depends on underwriting.
The vacant property request continues with the home application for a house, condo or 2–4 unit building.
Use the land request for undeveloped property with no buildings.
Review work on an existing building separately from the fact that it is empty.
No. This application is limited to fully vacant commercial property. An empty house, condo or 2–4 unit building starts on the vacant property page, which continues with the home application. Partly occupied property and farms need a separate scope review; do not describe them as fully vacant commercial property to use this form.
Yes, the application lets you request 3, 6, 9 or 12 months. The available term, coverage and conditions are subject to underwriting; selecting a term does not guarantee an offer.
Planned work is reviewed, so describe the work, its estimated cost and whether a contractor will perform it. Structural work and the contractor's liability coverage have separate questions. Answering them does not establish that the work is eligible.
No. It collects information for broker review. Required documents, carrier delivery, underwriting and any binding requirements still need handling. Completion is not an automatic carrier submission, an instant price or coverage in force.
A licensed broker can review eligibility and policy terms with you.